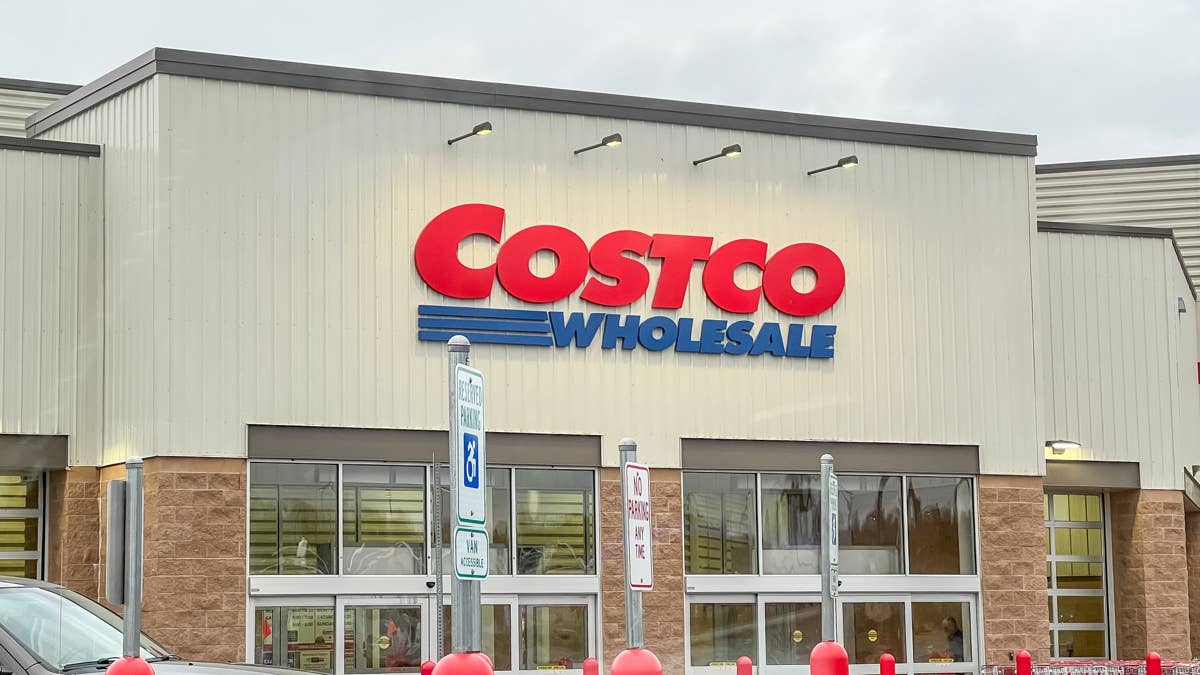
Costco has always struck me as an unusual retail business. Customers pay an annual membership fee just for the privilege of shopping there. And the crazy part is that the model has helped build a fiercely loyal customer base.
Between the bulk discounts, the famous $1.50 hot dog deal it’s offered since the mid-1980s without raising the price, and its treasure-hunt shopping experience, Costco has turned an ordinary warehouse store into an unexpectedly exciting destination for shoppers.
This time, the people who own the company got their own bulk deal. Jim Cramer reacted on the “Mad Money” Lightning Round on Nov. 10.
We just got a $30 special dividend in a stock we purchased. And those of us who for a moment thought that maybe it was overvalued, shame on us. Glad that my Charitable Trust stuck with it. It's a buy.
Costco’s (COST) business is doing extremely well, as reflected in its share performance. It closed at $1,092.21 on Nov. 12, after printing a new all-time intraday high of $1,102.84. It is up 27.40% year to date and 96.86% over three years.
Also Read: Costco’s longtime shoppers may not love what comes next
The Costco dividend Cramer is celebrating
Costco announced the $30-per-share special cash dividend on Nov. 10, according to TheStreet. It is payable Dec. 4 to shareholders of record as of Nov. 24, and the total payout is approximately $13.3 billion.
The board also reauthorized a common-stock repurchase program of up to $4 billion, running through November 2030. It replaces a 2023 program under which Costco bought back $3.1 billion of stock. Cramer also posted on X (the former Twitter).
“COST! Special dividend big buyback!!!! YES!!!”
More Costco:
- Costco’s latest bulk deal is for shareholders, not shoppers
- Costco members are paying more for gas and filling up anyway
- Costco’s longtime shoppers may not love what comes next
Cramer said that when he briefly thought Costco was overvalued, he was wrong. He’s made a career of telling viewers when to sell or buy. So, a public “shame on us” tells us that he read that wrong.
His admission also offers a glimpse into his Charitable Trust’s position. Cramer owns the stock and, despite previously questioning its valuation, chose to hold on to it.
A $30 payout on a $1,092 share is less than 3% of the price. For a retailer, I think handing shareholders $13.3 billion in cash tells us about how much the business generates.
Is Costco overvalued?
My honest answer is that it is undeniably expensive by traditional retail metrics, yet investors have rational, structural reasons for paying that premium.
According to Yahoo Finance, Costco trades at a trailing P/E of 52.39, a forward P/E of 47.66, a PEG ratio of 4.03, and a price-to-book of 13.47. These are growth-stock numbers for a business that sells groceries and gas.
A PEG above 2 usually means you are paying a lot for each point of growth, and 4.03 is way past that.
Related: How a Costco partner’s bankruptcy could benefit its biggest rival
But the underlying business earns the premium. Fiscal 2026 net sales were $297.2 billion, up 10.1%. Full-year diluted EPS was $20.76, up 14%.
In the fourth quarter, net sales rose 11.2% to $93.9 billion, and comparable sales rose 11.4%, or 9.4% excluding gas and currency, according to Costco’s Q4 and fiscal year 2026 results.
Digitally enabled comparable sales grew 19.5%. One caveat I would flag is that the Q4 EPS of $6.75 included a one-time benefit of about $0.15 from IEEPA tariff refunds, so the underlying growth is slightly lower than it looks.
The latest sales update is just as strong. October shows net sales were $24.50 billion, up 12.6% from $21.75 billion a year earlier, and the first nine weeks of the fiscal year came to $54.52 billion, up 12.8%.
Overall, my view is that Costco is priced for near-perfect execution. It is not a bargain.
If you already own it, I would hold. If you are buying new money at an all-time high, size it modestly, because a stock at 47 times forward earnings has little room for a disappointing month.
Why Costco stock keeps working
I remember covering a similar shopping-habit story when Synergy CHC lost its Costco contract. That filing showed how much a supplier depends on Costco, with 58% of Synergy’s revenue tied to one customer.
The reverse is also true. Costco’s power comes from sending millions of members through 945 warehouses and keeping them loyal.
Of those, 653 are in the U.S. and Puerto Rico, with international footprints in Canada, Mexico, Japan, the U.K., Korea, Australia, and beyond. The membership model gives it steady, predictable income, which is why the market treats it more like a subscription business than a store.
For someone who has shopped there, the lesson is the same as with any good consumer stock: The product is trust.
Members believe the price is fair, so they come back. And the special dividend just returned that trust to owners in cash.