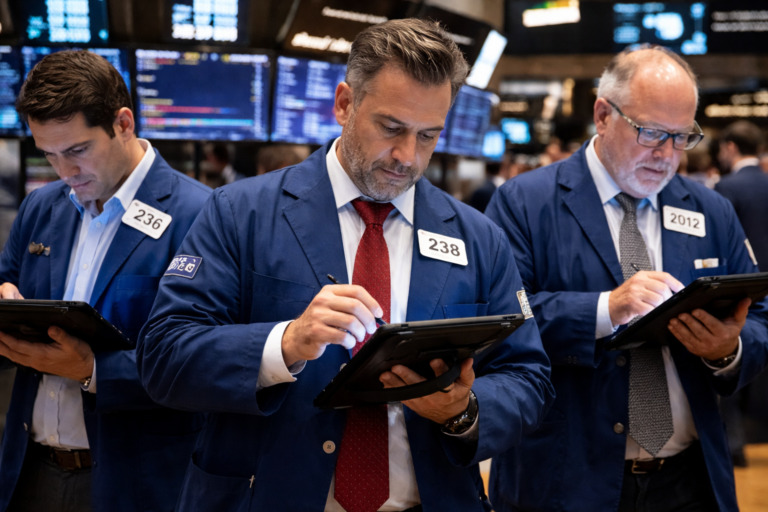
US stocks fell sharply on Friday, with the Nasdaq Composite recording its largest one-day percentage decline since June 5 as disappointing results from Intel and Amazon intensified concerns about the returns on massive artificial intelligence investments.
The technology-heavy index dropped 2.86% to 25,437, while the S&P 500 declined 1.82% to 7,580.07. The Dow Jones Industrial Average fell 1.09% to 51,770.31.
Selling pressure spread across semiconductor stocks and major technology companies as investors reassessed the outlook for AI-related spending.
The declines also reflected concerns about whether companies can generate sufficient returns from the infrastructure being built to support the technology.
All three major indexes ended the week lower. The S&P 500 and Nasdaq also recorded monthly losses in October, while the Dow finished the month higher.
Intel and Amazon results weigh on technology stocks
Intel shares plunged around 29% after the chipmaker issued a weaker-than-expected revenue forecast for the fourth quarter. The company expects revenue of $15 billion to $16 billion, below analysts’ estimates of $17.1 billion.
The forecast followed third-quarter adjusted earnings of 52 cents per share, ahead of expectations of 40 cents.
The company reported negative free cash flow of $42.4 billion and maintained its 2026 capital expenditure forecast of $220 billion.
The weakness extended across the semiconductor sector.
The Philadelphia Semiconductor Index recorded a monthly loss, while Advanced Micro Devices fell 11%. Nvidia and Broadcom declined 4% and 5%, respectively.
SanDisk lost 13%, despite reporting better-than-expected fiscal first-quarter results.
The broader technology sell-off also affected AI infrastructure companies.
CoreWeave shares fell more than 37% in October, while Nebius posted a monthly decline of 34%. The Roundhill Memory ETF, which includes Micron and Seagate Technology, lost 20% during the month.
Investors reassess AI spending and returns
The latest declines reflect growing scrutiny of the financial commitments behind the AI boom.
Investors are increasingly focused on whether large technology companies and infrastructure providers can translate substantial capital expenditure into sustainable returns.
Alphabet shares recorded their worst day on record on Thursday after missing third-quarter earnings and revenue expectations and reporting negative free cash flow of $9.07 billion.
Meanwhile, concerns about financing have weighed on neocloud companies that provide computing infrastructure for AI data centres.
CoreWeave has faced rising bond yields, adding to investor concerns about debt levels across the sector.
The shift in sentiment has prompted investors to move away from some technology stocks and towards more defensive sectors.
Consumer staples and healthcare shares advanced on Friday, with Walmart and Coca-Cola each gaining more than 1%. Merck and Amgen also rose.
October ends with mixed performance across Wall Street
Despite Friday’s losses, third-quarter corporate earnings have remained broadly positive.
Of the 299 S&P 500 companies that had reported results, 82% exceeded consensus expectations, according to LSEG data.
Analysts now expect S&P 500 earnings to grow 31.6% year over year in the quarter.
Energy companies Exxon Mobil and Chevron also beat quarterly profit expectations, benefiting from higher refining margins amid energy supply disruptions linked to the US-Israeli war with Iran and Russia’s war in Ukraine.
However, the technology-led weakness weighed on the broader monthly performance.
The Nasdaq was heading towards a 5% October decline, its steepest monthly fall since March 2025. The S&P 500 was on track to lose less than 1%, while the Dow was poised to gain around 2%.
Central banks weigh rate hikes amid sticky inflation, while tech sell-offs and energy costs drag precious metals to yearly lows.
Fed Officials Divided on Pace of Monetary Tightening Amid Sticky Inflation
Federal Reserve officials are currently navigating strong domestic economic momentum, with third-quarter Gross Domestic Product growing at a robust 3.4% year-over-year. Core Personal Consumption Expenditures (PCE) inflation remains elevated at 3.1% year-over-year, leading policymakers to agree that further policy restraint is needed. However, officials differ significantly on the required pace and urgency of implementation. St. Louis Fed President Alberto Musalem and Dallas Fed President Lorie Logan have signaled the need for additional rate hikes soon—with Logan calling for two more quarter-point increases—arguing that current financial conditions remain too loose. Conversely, Richmond Fed President Thomas Barkin and Fed Chair Kevin Warsh favor a more cautious, gradual approach to address broad-based cost pressures and demand-driven inflation spurred by supply chain strains from the AI investment boom.
Precious metals experienced a severe downturn, with gold falling to a year-to-date low of $3,880 and silver sliding below $50 to its lowest level since November 2025. Typically functioning as safe-haven assets during periods of market turmoil, both metals failed to benefit from a broader risk-off environment triggered by technology stock sell-offs and concerns over heavy artificial intelligence spending returns. Instead, bullion and silver prices were heavily pressured by expectations of further Federal Reserve interest rate hikes, a recovering US Dollar, elevated energy costs, and potential forced liquidations as investors scrambled to cover losses elsewhere in the market.
Global Central Banks Navigate Divergent Inflationary Pressures and Currency Trends
Central banks across major global economies are weighing distinct regional economic conditions against persistent inflation risks. The Bank of Japan (BoJ) kept its policy rate unchanged at 1.25%, but for the first time acknowledged that its 2% inflation target has been met, leaving market participants anticipating a rate hike to 2.00% by next summer. Meanwhile, the European Central Bank (ECB) paused its rate hikes at 2.50% while projecting inflation to remain above target, leaving a December rate increase firmly on the table despite internal growth concerns. Concurrently, robust third-quarter Eurozone GDP growth of 0.4% quarter-over-quarter supported the Euro, even as ongoing French fiscal worries and softening German annual CPI inflation to 2.8% complicated the broader regional economic outlook.
Top economic events for next week:
10/31/2026 01:30:00 – NBS Manufacturing PMI This high-impact data release for the Chinese Yuan provides a critical snapshot of the health and sentiment within China’s manufacturing sector. As the world’s second-largest economy, its manufacturing performance heavily influences global commodity demand and broader international market sentiment.
10/31/2026 01:30:00 – NBS Non-Manufacturing PMI Released alongside the manufacturing index, this high-impact metric measures activity in China’s service and construction sectors. It is vital for assessing domestic demand and economic momentum within China, affecting risk appetite globally.
11/02/2026 07:00:00 – Retail Sales (YoY) This high-impact European indicator tracks the year-over-year change in the value of retail sales within the Eurozone. It serves as a primary gauge of consumer spending strength, which constitutes a major driving force behind overall economic growth and inflationary trends in the region.
11/02/2026 15:00:00 – ISM Manufacturing PMI As a high-impact US indicator, the ISM Manufacturing PMI is widely watched by traders and the Federal Reserve. It measures business activity in the US manufacturing sector, offering strong signals regarding economic health, inflationary cost pressures, and future monetary policy directions.
11/03/2026 03:30:00 – RBA Interest Rate Decision This high-impact event outlines the Reserve Bank of Australia’s stance on monetary policy. Changes or forward guidance regarding interest rates directly influence the valuation of the Australian Dollar and dictate borrowing costs across the domestic economy.
11/03/2026 03:30:00 – RBA Rate Statement Released simultaneously with the interest rate decision, this statement provides detailed insights into the central bank’s economic outlook, inflation assessments, and future policy trajectory, triggering sharp volatility in AUD pairs.
11/03/2026 04:30:00 – RBA Press Conference Following the rate decision, the RBA Governor’s press conference offers direct elaboration on policy choices and answers to journalists’ questions. It is crucial for clarifying the central bank’s stance and shifting market expectations for upcoming meetings.
11/03/2026 05:00:00 – US Midterm Elections Classified as a high-impact political event for the US Dollar, the midterm elections can dramatically shift the political landscape in Washington. The outcome influences future fiscal spending, regulatory policies, legislative priorities, and overall market confidence.
11/03/2026 07:30:00 – Consumer Price Index (YoY) This high-impact Swiss release measures annual inflation changes. Because price stability is the Swiss National Bank’s core mandate, this metric heavily impacts inflation expectations and dictates future monetary policy actions for the Swiss Franc.
11/03/2026 16:00:00 – BoC’s Governor Macklem speech Featuring the head of the Bank of Canada, this high-impact speaking engagement provides vital commentary on Canada’s economic outlook and monetary policy direction. Markets closely parse the speech for clues regarding upcoming interest rate adjustments and economic resilience.
The subject matter and the content of this article are solely the views of the author. FinanceFeeds does not bear any legal responsibility for the content of this article and they do not reflect the viewpoint of FinanceFeeds or its editorial staff.
The information does not constitute advice or a recommendation on any course of action and does not take into account your personal circumstances, financial situation, or individual needs. We strongly recommend you seek independent professional advice or conduct your own independent research before acting upon any information contained in this article.
Whether large chains or family-owned neighborhood joints, seafood restaurants have continued to face significant challenges throughout 2026.
Casual dining Florida chain Red Lobster closed 36 of its restaurants in different corners of the country last year as part of a wider shrinking of its footprint after emerging from Chapter 11 bankruptcy at the end of 2024.
Other seafood chains, including Bahama Breeze and Joe’s Crab Shack, have also shuttered dozens of locations due to similar struggles with skyrocketing ingredient and other operating costs. For some of the larger chains, sale-leaseback real estate deals also locked them into high monthly rent payments, even amid falling traffic.
Cook’s Seafood permanently closes both California restaurant locations
For smaller family-owned restaurants, the situation is often even more dire.
Opened in 1928 by a local policeman with a dream of running a seafood restaurant, Cook’s Seafood was a Menlo Park neighborhood staple long before the suburb between San Francisco and San Jose became a hub of Silicon Valley innovation.
Bill Cook originally opened Cook’s Seafood as a counter selling fish and chips but expanded to a full-service after seeing a few years of early success.
Up until now, it operated both as a market selling fresh fish and seafood and a restaurant serving fish and chips, fresh catch of the day, and seafood classics such as lobster rolls and clam chowder.
As reported by local media outlet Palo Alto Online, several employees at both the original location and a second one that opened in 2025 in Pleasanton, across the San Francisco Bay, received a text message saying that both locations were being shut down.
“We are sad to inform you that after 98 years, we have closed all Cook’s Seafood locations Wednesday, Oct. 28, 2026,” Dan Dowler, who had been working at the restaurant as a counter clerk since 1972, reportedly received via text.
“Our family thanks you for all your years of service, and we’re sorry for saying this so late tonight. But we don’t want you to drive to work tomorrow, as the building is closed. We’ll send out more updates later today.”
Cook’s Seafood has been operating as a fish counter since 1928.
Cook's Seafood
“This year has been very difficult for restaurants”: Cook’s Seafood on abrupt closures
Local residents also photographed a similar message posted on a printout in the windows of the two locations, InMenlo noted. A representative of the restaurant could not be immediately reached for comment. Calls to the two locations redirected to voicemail.
Without elaborating further, the statement issued by the Cook’s Seafood team named a “year [that] has been very difficult for restaurants” as the reason for the decision to shutter.
The abrupt closure of a neighborhood staple hit hard for both many of Cook’s Seafood longstanding employees and members of the community with generational memories of going to the restaurant for fresh fish.
“My very frugal mother only bought seafood from Cook’s when I was growing up in Menlo Park,” resident Linda Hubbard told Palo Alto Online. “And I’ve followed in her footsteps. Always the best, it will be missed.”
Amazon shares AMZN fell sharply in after-hours trading on Thursday after the company reported third-quarter revenue and earnings below Wall Street expectations, while its $220 billion capital expenditure plan renewed concerns about the cost of its artificial intelligence expansion.
The stock declined more than 4% after falling 4.3% during regular trading.
Amazon reported revenue of $201.9 billion for the quarter, up 12% year over year but below analysts’ expectations of $202.2 billion, according to FactSet.
Net income fell to $20.7 billion, or $1.89 per share, from $21.2 billion, or $1.95 per share, a year earlier. Analysts had expected earnings of $1.97 per share.
The results came as investors continued to assess whether major technology companies can generate sufficient returns from their substantial AI infrastructure investments.
AWS growth beats estimates as spending concerns persist
Amazon Web Services (AWS) remained a bright spot, with revenue rising 39% year over year to $46 billion, exceeding analysts’ expectations of $45.47 billion.
The growth rate also surpassed Wall Street’s forecast of 37.8%.
Chief Executive Andy Jassy defended the company’s infrastructure spending, saying in a statement that Amazon’s investments in AWS were delivering growth.
He also said the company expects AWS revenue growth of more than 40% in 2027 and 2028.
However, the company’s spending plans continued to weigh on investor sentiment.
Amazon maintained its forecast of approximately $220 billion in capital expenditure for 2026, with much of the investment directed towards AI infrastructure and data centres.
Capital expenditure reached $75.9 billion in the third quarter.
The spending contributed to a cash outflow of $42.4 billion over the trailing 12 months, compared with a cash inflow of $14.8 billion in the year-earlier period.
Amazon’s increased investment reflects the resources required to expand computing capacity as demand for AI services grows.
However, the resulting pressure on cash flow has become a key consideration for investors evaluating the company’s long-term returns.
Retail sales and profits fall short of expectations
Amazon’s North American sales increased 6% year over year to $112.9 billion, missing analysts’ forecast of $113.2 billion.
Revenue from its online stores business rose 2% to approximately $68.5 billion.
The company said the timing of Prime Day, which moved into the second quarter in several major countries, affected its third-quarter revenue growth.
Advertising revenue growth also slowed to 12%, partly because of the shift in the shopping event. Amazon expects advertising growth to rebound to the high teens in the fourth quarter.
Net income was also affected by a comparison with the previous year.
Amazon said third-quarter 2025 profit included $9.5 billion in pretax gains on its investment in AI company Anthropic.
For the fourth quarter, Amazon forecast revenue of $240 billion to $247 billion, representing growth of 12% to 16%.
The guidance includes some expected negative effects from currency fluctuations. The company also projected operating income of $28.5 billion to $33.5 billion.
Future AI investment raises cash flow questions
Although Amazon did not provide capital expenditure guidance for 2027, Evercore ISI analysts forecast spending could reach $320 billion next year, alongside negative free cash flow of $57 billion.
That outlook highlights the financial demands of the AI infrastructure race, even as AWS delivers faster growth.
Amazon’s spending strategy also comes amid broader scrutiny of data-centre expansion and the resources needed to support it.
The company has pledged more than $1 billion over five years towards communities hosting its data centres.
For investors, the central question remains whether strong cloud growth can translate into sustainable cash generation as Amazon continues to invest heavily in AI infrastructure.
Amazon has printed the quarter, and the tape did not pay it. Net sales were $201.9 billion, up 12 percent. AWS net sales increased 39.3 percent to $46.0 billion, the fastest growth in nearly five years, at a $184 billion annualized run rate. Operating income was $28.1 billion and the margin was 13.9 percent, which the company called its highest ever. Net income still fell, to $20.7 billion, or $1.89 a diluted share, from $21.2 billion, or $1.95. The release says that decrease is driven primarily by pre-tax gains of $9.5 billion in the third quarter of 2025 from the Anthropic investment.
The cash session did not need a miss against Amazon’s own July range to sell the stock. Sales of $201.9 billion sit inside the $197.0 billion to $202.0 billion guide. Operating income of $28.1 billion is $1.6 billion above the $26.5 billion top of that guide. Nasdaq’s quote page lists the Thursday cash close at $243.79, down $10.81, or 4.25 percent, from Wednesday’s official close of $254.60, and stamps it “Closed at Oct 29, 2026 4:00 PM ET.” At 4:31 p.m. ET the same page showed an after-hours last of $229.13, down $14.66, or 6.01 percent, from that close. The historical daily file, fetched after the close, still ends on Wednesday. The year-end path does not move until that file does.
From the Wednesday close of $254.60, the 44 sessions through 31 December 2026 still put the bull at $336.10, the base at $265.99, and the bear at $227.58. Those three prices are the last 90 daily log-returns. They are not a rerun on the after-hours print. The after-hours sale is $1.55 above the bear and $25.47, or 10.0 percent, under Wednesday. It is a print. It is not a new distribution. Alphabet’s third quarter is the parallel that already traded: Google Cloud up 103 percent, free cash flow negative, and Class C’s Thursday cash close at $282.32, down $39.57, or 12.29 percent, from Wednesday’s $321.89.
Quick take. AWS accelerated and operating income cleared the July top. Trailing free cash flow went to an outflow of $42.4 billion, from an inflow of $14.8 billion a year earlier, and the 2026 cash-capex line stayed at approximately $220 billion. The bull is still $336.10 and the bear is still $227.58, because both are chained to Wednesday’s $254.60 close.
Key facts
AMZN’s last official close in the Nasdaq historical file is Wednesday 28 October 2026 at $254.60. The quote page lists Thursday’s cash close at $243.79, down 4.25 percent, and an after-hours last of $229.13 at 4:31 p.m. ET. Nasdaq.
Bull $336.10, base $265.99, bear $227.58. Mean log-return mu is 0.00099508 and sample standard deviation sigma is 0.02351213 on the last 90 daily log-returns. N is 44 sessions from the Wednesday close through 31 December 2026. FinanceFeeds calculation on the saved historical file. Thursday is not in that file.
The 20-day average is $255.17 and the 50-day average is $255.12, both measured on closes through Wednesday. Thursday’s cash close is $11.38 under the 20-day average. The after-hours print is not in either average.
Third-quarter net sales were $201.9 billion, up 12 percent from $180.2 billion, or 13 percent excluding a $0.9 billion foreign-exchange headwind. AWS sales were $46.0 billion, up 39.3 percent. Operating income was $28.1 billion, against $17.4 billion. Net income was $20.7 billion, or $1.89 a share. Amazon third-quarter release, 29 October 2026.
Trailing twelve-month operating cash flow was $168.3 billion, up 29 percent. Free cash flow was an outflow of $42.4 billion, against an inflow of $14.8 billion a year earlier. The release says the change is driven primarily by a $94.8 billion increase in purchases of property and equipment, net of proceeds, and that the increase primarily reflects artificial-intelligence investment.
Fourth-quarter guidance, as of 29 October, is net sales of $240.0 billion to $247.0 billion, growth of 12 percent to 16 percent, and operating income of $28.5 billion to $33.5 billion, against $25.0 billion a year earlier. The company continues to expect 2026 cash capital expenditures of approximately $220 billion. Same release.
Andy Jassy said AWS posted “over 39% year-over-year revenue growth in Q3 ($184 billion revenue run rate) and projected revenue growth rates of over 40% both in 2027 and in 2028.” Same release.
Alphabet Class C closed Thursday at $282.32, down 12.29 percent from $321.89. The FinanceFeeds Google distribution is still anchored to Tuesday’s $316.83 close.
What the Wednesday close still prices
The formula uses the last completed bar in the historical file. That file, fetched after Thursday’s cash close, still ends on Wednesday 28 October at $254.60. The high that day was $255.36 and the low was $251.98. Volume was 34,915,860 shares. Thursday’s $243.79 is the cash close on the quote page. The after-hours sale of $229.13 is a later print on the same page. Neither number is a row in the file the chart uses, so neither number enters the bull, the base, or the bear.
The path uses the last 90 daily log-returns in that file. The mean, mu, is 0.00099508. The sample standard deviation, sigma, dividing by 89, is 0.02351213. N is 44 sessions after Wednesday through 31 December 2026, skipping only Thanksgiving and Christmas. Early closes still count. Thursday is one of those 44 sessions. It has traded. It has not replaced the spot.
The arithmetic is unchanged. Base equals $254.60 times e to the power of 44 times 0.00099508, which is $265.99. Bull equals $254.60 times e to the power of 44 times mu plus 1.5 times sigma times the square root of 44, which is $336.10. Bear equals $254.60 times e to the power of 44 times mu minus sigma times the square root of 44, which is $227.58. The square root of 44 is 6.63325. Bull is 32.0 percent above the Wednesday close. Base is 4.5 percent above it, or $11.39. Bear is 10.6 percent below it. A mean daily log-return of 0.00099508 is too small to reach $336.10 without the volatility term.
Amazon official Nasdaq daily closes through Wednesday 28 October 2026. Bull $336.10, base $265.99 and bear $227.58 are the 44-session path from the $254.60 close. Thursday’s $243.79 cash close is on the Nasdaq quote page and is not yet a row in this historical file. The 4:31 p.m. ET after-hours print of $229.13 is not plotted. Source: Nasdaq historical prices, fetched 29 October 2026. Chart: FinanceFeeds.
The 20-day average through Wednesday is $255.17 and the 50-day is $255.12. The five sessions through Wednesday ran from $246.45 to $258.41. Thursday’s cash range was $241.24 to $249.14, so the low undercut that band by $5.21, and the $243.79 close finished inside the day. The after-hours sale at $229.13 is $12.11 under the cash low and $1.55 above the bear. From the 31 December 2025 close of $230.82, Wednesday was up $23.78. Thursday’s cash close gives $12.97 of that back.
Case
Price
Versus the $254.60 close
What has to be true
Bull
$336.10
+32.0 percent
The 90-day drift holds and the path finishes 1.5 standard deviations above it. Thursday’s cash close and the after-hours print both trade the other way.
Base
$265.99
+4.5 percent
The drift compounds and nothing else does. A $243.79 cash close is $22.20 under this price. Getting back there is a retracement, not the print the release just produced.
Bear
$227.58
-10.6 percent
The same drift, one standard deviation lower, over the rest of the year. The 4:31 p.m. ET sale at $229.13 is $1.55 above it. One after-hours trade is not the year-end path.
The prior English pair was a $320.39 bull and a $210.55 bear from the 23 October close of $248.00. Both ends have moved by more than a dollar. This base, $265.99, is what a near-zero drift looks like from $254.60. The release does not replace it.
What the release actually printed
The quarter ended 30 September 2026. Net sales were $201.9 billion, against $180.2 billion, up 12 percent. Excluding a $0.9 billion foreign-exchange headwind, growth was 13 percent. Prime Day sat in the second quarter for most large countries this year and entirely in the third quarter of 2025. The company says that excluding the shift, third-quarter growth would have been about 400 basis points higher. North America sales were $112.9 billion, up 6 percent. International sales were $43.1 billion, up 5 percent, or 8 percent excluding foreign exchange. AWS sales were $46.0 billion, up 39 percent in the segment paragraph and 39.3 percent in the headline. The segment table is $45,984 million, against $33,006 million.
Operating income was $28.1 billion, against $17.4 billion. North America contributed $8.7 billion, against $4.8 billion. International contributed $1.6 billion, against $1.2 billion. AWS contributed $17.8 billion, against $11.4 billion. The AWS table is $17,773 million on $45,984 million of sales, against $11,434 million on $33,006 million, a margin of about 38.7 percent against about 34.6 percent. Net income of $20.7 billion is the operating result with last year’s investment gain taken out.
The cash statement is the number that rhymes with Google. Operating cash flow for the twelve months ended 30 September was $168.3 billion, against $130.7 billion, up 29 percent. At 30 June that trailing operating figure was $161.403 billion, so the cash from operations did not crack. Free cash flow did. The highlight puts the trailing outflow at $42.4 billion, against an inflow of $14.8 billion a year earlier, and says the bridge is a $94.8 billion increase in property purchases, net of proceeds, primarily for artificial intelligence. At 30 June the trailing outflow was $7.604 billion. The same window is now $42.4 billion.
The cash-flow table supports the highlight. Purchases of property and equipment were $77,259 million in the quarter, against $35,095 million, and $215,192 million over the trailing twelve months, against $120,131 million. Proceeds from sales and incentives were $1,381 million in the quarter and $4,535 million over the trailing twelve months. Trailing operating cash of $168,300 million, minus purchases net of those proceeds, is an outflow of about $42.4 billion. Quarterly purchases of $77.259 billion were $31.275 billion larger than AWS sales of $45.984 billion. Depreciation and related amortization, a line that also includes capitalized content and leases, was $20,949 million in the quarter, against $16,796 million. Proceeds from long-term debt were $48,102 million in the quarter and $115,100 million in the first nine months.
“Our AWS investment in functionality and infrastructure is working, with over 39% year-over-year revenue growth in Q3 ($184 billion revenue run rate) and projected revenue growth rates of over 40% both in 2027 and in 2028,” Andy Jassy, Amazon’s president and chief executive, said. He also said: “There has never been a trillion dollar revenue business, and we may have two of them in the next 5-10 years.” The 40 percent line is a revenue projection. It is not a new capex dollar. The guidance paragraph says the company continues to expect 2026 cash capital expenditures of approximately $220 billion. That is the same figure he used on the a16z podcast, reported by DatacenterDynamics, and the figure FinanceFeeds reported on 31 July when the plan moved up from about $200 billion. The release did not raise it.
Fourth-quarter guidance, dated 29 October, is net sales of $240.0 billion to $247.0 billion, growth of 12 percent to 16 percent, with about 60 basis points of foreign-exchange drag. Operating income of $28.5 billion to $33.5 billion, against $25.0 billion in the fourth quarter of 2025. Advertising grew 12 percent year over year excluding foreign exchange in the third quarter, which the company tied to Prime Day timing, and the company expects high-teens advertising growth in the fourth quarter. The release does not put a dollar on that 12 percent. The guide assumes no extra energy-derivative remeasurement and no new acquisition, restructuring, or settlement. The uncertainties named above the guide include tariffs and trade policy, memory chips, energy prices, and customer demand.
Google’s close, and the capex line that did not move
Alphabet’s quarter is the template the afternoon was trading. Google Cloud grew 103 percent to $30.7 billion. Purchases of property and equipment were $51.4 billion. Free cash flow was negative $9.1 billion. The 2026 spending range stayed at $195 billion to $205 billion, and the finance chief said 2027 would be significantly higher without a new dollar. Class C’s cash close on Thursday was $282.32, down 12.29 percent from $321.89. After-hours at 4:33 p.m. ET was $280.58, only $1.74 under that close. Google did the damage in the cash session.
Amazon’s version is not the same percent. AWS added $12,978 million of sales. Google Cloud’s increase, off a quarter that more than doubled to $30.7 billion, is larger. Amazon’s quarterly property purchases were $77.259 billion, against Alphabet’s $51.4 billion, and Amazon’s trailing cash outflow is $42.4 billion, against Alphabet’s quarterly outflow of $9.1 billion. Apply Class C’s 12.29 percent drop to Wednesday’s $254.60 and the product is $223.31, or $4.27 under the bear. Amazon’s cash close did not print it. The after-hours sale at $229.13 stops $1.55 short. The release kept the 2026 dollar. The tape sold the equity anyway.
Chris Camillo wrote, at 2:35 p.m. ET, before the numbers: “You can be dead right about the business and still get absolutely crushed trading AI earnings right now. $AMZN could blow away every expectation tonight and get punished for raising capex to meet unprecedented demand.” The status is on X. Operating income did clear the company’s own top. The release did not raise the $220 billion line. The punishment arrived without that raise. At 3:04 p.m. ET, The Option Premium wrote that the spark was the capex guide: “If it comes in like Microsoft’s, the squeeze is on. If it comes in like Google’s, the trap’s for the bulls.” The status is on X. The post does not give Microsoft’s figure. Amazon’s guide kept a dollar and still described a heavier build, which is the part of the Google tape that was about 2027 rather than about a new 2026 number.
What the tape did with a beat
Two clocks, two stocks. Class C closed at $282.32, down $39.57. Amazon closed at $243.79, down $10.81, with a cash range of $241.24 to $249.14 and volume of about 75.0 million shares on the quote page, against 34.9 million on Wednesday. After the close the paths split again. Class C was $280.58 at 4:33 p.m. ET. Amazon was $229.13 at 4:31 p.m. ET, bid $229.00 and ask $229.39, down 6.01 percent from its own cash close and 10.0 percent from Wednesday.
M. Mohan had posted that AWS had to deliver 42 percent growth. After the number he wrote: “I dont think Amazon $AMZN LLM works. 39% AWS growth!” The status is on X. The 42 percent was his bar. The 39 percent is the release. At the same minute MoonBoy Capital wrote that the stock was “down 6% after hours,” which matches the 6.01 percent Nasdaq showed at 4:31 p.m. ET. The status is on X.
The bull still needs the volatility term. Mu does not get to $336.10 on its own, and a cash close at $243.79 moves the starting point the wrong way if Friday’s historical bar replaces Wednesday. The bear does not require a 13 percent day. It requires the drift minus one standard deviation over the remaining sessions. One after-hours trade at $229.13 can cover a large piece of that distance and still not be the official Friday close. Until the historical file prints a new last bar, the bull is $336.10, the base is $265.99, and the bear is $227.58.
This is not financial advice.
Frequently asked questions
What is the Amazon stock prediction through 31 December 2026?
From the Nasdaq historical close of $254.60 on 28 October 2026, the bull is $336.10, the base is $265.99, and the bear is $227.58 over 44 sessions. Thursday’s cash close and the after-hours print are not in that file. The path is a volatility calculation on the last 90 daily log-returns, not a bank target.
What did the third-quarter report change?
Sales were $201.9 billion, inside the July range. Operating income was $28.1 billion, above the July top of $26.5 billion. AWS grew 39.3 percent to $46.0 billion. Net income fell to $20.7 billion because the year-ago quarter included a $9.5 billion Anthropic gain. Trailing free cash flow was an outflow of $42.4 billion. The 2026 cash-capex expectation stayed at approximately $220 billion.
Why does Google’s result still matter?
Google Cloud grew faster, and Class C still closed down 12.29 percent at $282.32. Amazon grew AWS more slowly, spent $77.259 billion on property and equipment in the quarter, and reported a deeper trailing cash outflow. The cash session fell 4.25 percent. After-hours then took the stock to $229.13, near the bear, without a higher 2026 capex dollar.
Is $336.10 the analyst target?
No. Yahoo Finance’s one-year mean on the quote page fetched before the release was $332.41, which is $3.69 under the bull and a different horizon. The bull is 44 sessions of Amazon’s own daily returns through Wednesday. This update does not publish a new street mean.
Does Thursday’s close replace the bull and the bear?
Not yet. The quote page lists a $243.79 cash close and a $229.13 after-hours sale. The historical file used for the formula still ends at $254.60. A later official bar can replace the spot. An after-hours trade cannot. The $229.13 sale is $1.55 above the bear and is not the year-end path.
Did Amazon raise the $220 billion plan?
The 29 October guidance says the company continues to expect 2026 cash capital expenditures of approximately $220 billion. Jassy projected AWS revenue growth of over 40 percent in 2027 and in 2028. That is a growth rate, not a higher spending dollar. The spending that did change is the trailing free-cash-flow outflow, now $42.4 billion.
For years, TJ Maxx and Marshalls have pulled in more bargain-hunting shoppers than Ross Stores. However, that may be starting to change.
On Oct. 26, UBS said a new strategy under CEO James Conroy could finally help Ross catch up to its biggest rival. Because of that, the firm upgraded Ross Stores (ROST) from Neutral to Buy and raised its price target to $315 from $239.
If you are not familiar with Ross, the company sells items under two brands, Ross Dress for Less and dd’s DISCOUNTS. The company buys extra inventory from brands and vendors at low prices, then resells them at even lower prices than regular retail.
What UBS analysts see in the stock
Ross wants its sales to catch up to its rival, and last year, the company got a new CEO to help achieve that goal.
Back in 2017, Ross and TJX made roughly the same amount of sales per square foot of store space. However, by the end of 2025, TJX’s number had increased by 44%, while Ross’s had grown by just 24%, TradingView reported.
However, UBS analyst Jay Sole thinks investors are underestimating how fast Ross’s latest CEO can close that distance. “We think the market doesn’t appreciate how much ROST closing this gap will drive comp growth in FY27 and beyond,” Sole wrote.
He believes that with the CEO’s plans, Ross should grow its sales by about 8.5% per year over the next two years, about 260 basis points above what Wall Street generally expects.
Ross Stores is trying to narrow its sales-per-store gap with TJ Maxx under CEO James Conroy.
How Ross Stores CEO James Conroy plans to turn things around
Conroy became Ross’s CEO on Feb. 2, 2025. Before he took on the chief executive role, he was in charge of Boot Barn, a company he grew from a mid-sized western-wear chain into a national name. Now he plans to help Ross improve its sales.
The first way he plans to do that is by getting better merchandise. Ross is adding more recognizable brands and a steadier mix of “good, better, and best products” to its lineup. Investing.com reported that this shift has already boosted the sales of women’s apparel.
The CEO is also focusing more on marketing, and Sole said the marketing shift is “probably the one most underappreciated by the market.”
He noted that Ross used to spend only 0.4% of sales on ads, while TJX spent 1.1%. However, Conroy is investing more in social media and streaming ads to attract younger shoppers.
In addition, the company is paying more attention to the stores themselves, including things like faster checkout and cleaner aisles. It even moved more staff from back rooms to the sales floor.
Why value shoppers keep picking discount stores
A UBS Evidence Lab survey found that 79% of U.S. consumers say value for money is the main reason they pick a retailer, Yahoo Finance reported.
And with the current economic situation, every dollar matters.
According to the National Retail Federation, discount stores rank as one of the top destinations for 2026 holiday shopping.
And because the price tag at Ross is 20% to 60% below the department-store average, Ross should keep pulling in shoppers looking to cut costs compared with pricier chains such as Macy’s and Kohl’s.
What to consider before buying ROST stock
Ross’s sales grew well from the second half of 2025 into the first half of 2026. However, sales growth usually slows down after a company experiences a big year. That means it might be hard for Ross to get better numbers than it did during this period.
Also, I believe that if diesel prices keep climbing due to the war in the Middle East, Ross will have to spend more to move goods from suppliers to its stores, which will affect its profits.
Even with those risks, UBS sees ROST increasing by about 37% from its Oct. 23 close of $229.30. In addition, the stock already trades near 26 times forward earnings for fiscal 2026, which means a lot of the good news is already priced in.
So if you’re thinking of buying the stock, it might be better to wait for a pullback, or at least the next earnings report in late November, to get a better entry point.
Oracle shares ORCL rose more than 11% on Wednesday after the company reaffirmed its fiscal 2027 outlook and issued long-term financial targets, offering investors greater clarity on the expected returns from its artificial intelligence infrastructure spending.
At its financial analyst day in Las Vegas, the cloud and database company said it expects revenue of at least $90 billion and adjusted earnings of $8.10 per share for fiscal 2027.
Analysts had expected earnings of $8.14 per share and revenue of $90.45 billion.
Oracle also outlined its ambition to expand revenue significantly over the next several years, while forecasting a return to positive free cash flow as capital expenditure begins to decline.
The outlook comes as investors scrutinise the company’s substantial investment in AI data centres and its ability to finance expansion while meeting its financial commitments.
Oracle targets $225B revenue by fiscal 2030
Oracle expects revenue to grow at a compound annual growth rate of 35% between fiscal 2026 and fiscal 2030, reaching at least $225 billion in the final year.
The figure was higher than the $217.7 billion figure expected by Wall Street analysts according to FactSet data.
For fiscal 2030, the company also forecast adjusted operating margins above 40% and adjusted earnings of more than $21 per share.
The targets reflect Oracle’s efforts to expand beyond its traditional database software business and become a major provider of computing infrastructure for AI workloads.
The company is building data centres to serve OpenAI and other customers, placing it at the centre of growing demand for AI computing capacity.
However, the scale of this expansion has raised concerns about the costs involved and the time required to generate sufficient cash returns.
Oracle also faces scrutiny over its reliance on OpenAI, a loss-making customer, as it expands its infrastructure business.
Free cash flow expected to turn positive in fiscal 2028
Chief Financial Officer Hilary Maxson said Oracle expects free cash flow to turn positive in the second half of fiscal 2028 and exceed $30 billion in fiscal 2029.
The projection is more favourable than market expectations.
Investors had anticipated that free cash flow would remain negative in fiscal 2029, according to Bloomberg data.
Oracle expects capital spending to peak between fiscal 2027 and fiscal 2028 before slowing in fiscal 2029.
The company said the reduction in spending would help it generate more cash internally.
Maxson said Oracle expects to begin self-funding its growth in fiscal 2029, potentially reducing its reliance on external financing as its AI infrastructure investments mature.
The forecast is significant because the company’s spending requirements have become a central concern for investors assessing whether its AI expansion can produce sustainable financial returns.
Oracle limits planned capital raises to $20B
Oracle said it expects to raise $20 billion from capital markets between fiscal 2027 and fiscal 2030, excluding refinancing.
The planned amount comprises $10 billion in equity and $10 billion in debt.
The company also expects vendor financing, customer-provided hardware and prepayments to reduce its upfront cash requirements.
These arrangements could help Oracle manage the funding demands associated with its data-centre expansion while limiting additional capital raises.
The company’s ability to control financing needs and generate cash will remain important as it pursues its long-term revenue targets.
A 25 percent revenue print does not decide GOOG. Alphabet reported third quarter revenue of $127.6 billion on 28 October 2026, up 25 percent, and $365 million under the $127.942 billion FactSet carried the day before. Diluted earnings per share were $2.12, against $2.87 a year earlier and FactSet’s $3.01. Google Cloud revenue was $30.7 billion, up 103 percent, ahead of the 89.8 percent FactSet expected. Purchases of property and equipment were $51.4 billion, and free cash flow was negative $9.1 billion. Class C closed at $316.83 on Tuesday 27 October, and that close is the one in this distribution. From there, 45 sessions through 31 December 2026, the path is a $360.67 bull, a $294.19 base, and a $256.83 bear. The third quarter release does not put a dollar on 2027 capex. FactSet’s note still has that consensus at $312.217 billion. These three prices are the last 90 daily log-returns. They are not an analyst target, and they use Class C only.
The miss against the earnings line is the equity book, not Cloud. The release says a net loss on equity securities of $8.7 billion cut diluted earnings per share by $0.55. Adding that $0.55 back to $2.12 leaves $2.67, still $0.34 under FactSet’s $3.01. Cloud operating income was $11,121 million on $30,709 million of revenue, a 36.2 percent margin, up from 35.6 percent in the second quarter. Ashkenazi had warned that rented capacity would press margins. The printed margin did not fall. Cash did. Free cash flow was negative $5.9 billion in the second quarter and negative $9.1 billion in the third. Trailing twelve month free cash flow in this release is $19.7 billion, against June’s $53.3 billion.
Key facts
GOOG, Alphabet Class C, closed at $316.83 on Nasdaq on Tuesday 27 October 2026. The 20-day average of the saved closes is $337.25 and the 50-day average is $338.50. Nasdaq historical file, downloaded 28 October 2026.
The prior five sessions’ high was $341.00 and the low was $313.51. Tuesday’s close sits $24.17 under that high and $3.32 above that low.
On 23 July 2026 the close was $318.34, down $23.57, or 6.89 percent, from the 22 July close of $341.91. That session is the largest of the last 90 daily log-returns.
Second quarter 2026: revenue $119.8 billion, up 24 percent. Google Cloud $24.8 billion, up 82 percent, operating income $8.8 billion, margin 35.6 percent against 20.7 percent a year earlier. Capex $44.9 billion. Free cash flow negative $5.9 billion. Anat Ashkenazi, 22 July 2026 earnings call.
2026 capex guidance is $195 billion to $205 billion, up from $180 billion to $190 billion. Ashkenazi said capex is still expected to increase significantly in 2027, with details later. Same call.
Google Cloud remaining performance obligations were $513.9 billion of a $519.5 billion company total as of 30 June 2026. Just over half is expected as revenue over 24 months. Alphabet Form 10-Q for the quarter ended 30 June 2026.
Third quarter 2026 release, filed 28 October: revenue $127,577 million, up 25 percent. Diluted EPS $2.12. Google Cloud $30,709 million, up 103 percent. Search and other $63,350 million, up 12 percent. Property and equipment purchases $51,355 million. Free cash flow negative $9,065 million. Alphabet Exhibit 99.1, 28 October 2026.
FactSet, 27 October 2026, on X: third quarter revenue consensus $127.942 billion, earnings per share $3.01, Cloud growth 89.8 percent, Search growth 14.8 percent. Full year 2027 capex consensus $312.217 billion, up 54.7 percent.
The close is not waiting on a revenue beat
The table in the release prints revenue of $127,577 million, against $102,346 million a year earlier. That is the 25 percent the company cites, and it is $365 million under FactSet’s $127.942 billion. Operating income was $40,576 million, up 30 percent, and the release puts the operating margin at 31.8 percent. Other income was a loss of $8,221 million, against a gain of $12,759 million a year earlier. The second quarter had the opposite mark: earnings per share of $9.11 included a net gain of $98.0 billion, mostly unrealized gains on equity securities. This quarter the equity book cut the earnings line. The operating result, and the $51.4 billion of property and equipment, are what the capex debate is about.
The highest close after 23 July in the saved file is $375.35 on 4 August 2026. From that close to Tuesday’s $316.83 is a decline of $58.52, or 15.59 percent. The rally that followed the capex raise has been given back. The shares are $1.51 under the close that first absorbed the raise.
Tuesday also sits under both moving averages on the chart. The 20-day average is $337.25, so the close is $20.42 below it. The 50-day average is $338.50, so the close is $21.67 below it. The highest high in the year of daily bars is $404.47 on 18 May 2026. Tuesday is $87.64, or 21.67 percent, under that high. The lowest low in the same window is $264.94 on 27 October 2025.
None of those levels is Wednesday’s price. Nasdaq’s quote page, fetched while the cash session was still open, showed a last sale of $320.86 at 3:29 p.m. Eastern on 28 October, up $4.03, or 1.27 percent, with the market status marked Open. That print is not a close and it is not an input to the bull, the base, or the bear. The formula uses Tuesday.
Nasdaq official daily closes for GOOG through Tuesday 27 October 2026. The series was downloaded from the Nasdaq historical endpoint, which names the exchange NASDAQ-GS. The top panel includes the daily lows. FinanceFeeds chart, 28 October 2026.
What Alphabet has already said about AI spending
On the 22 July call Ashkenazi said second quarter capex was $44.9 billion, with the vast majority in technical infrastructure for AI. About 60 percent of that infrastructure spend was servers and about 40 percent was data centers and networking equipment. She raised the 2026 range to $195 billion to $205 billion, from $180 billion to $190 billion, mostly on faster delivery of capacity. She said 2027 capex is still expected to rise significantly, with the dollar later.
That 2026 range is more than double the $91 billion to $93 billion range given for 2025. FactSet’s 2027 consensus is $312.217 billion. The exhibit still does not publish it. On X before the release, KawzInvests noted the same gap.
Pichai’s October comments explain why a refused number and a large order book can sit together. Kantrowitz quoted him on X: “The compute we have today is a function of decisions I made in 2024.” A customer asking now for compute in 2027 is, in Pichai’s words, “incredibly difficult to do.” He also said Cloud is forgoing short-term revenue to keep compute for frontier model work. A strong Cloud print and a capacity complaint can both be true. The backlog is not a promise that this year’s cash flow turns positive.
Remaining performance obligations in the 10-Q were $519.5 billion at 30 June 2026, of which $513.9 billion was Google Cloud. The call rounded that to $514 billion and said it had grown by more than $50 billion in the quarter. Just over half is expected as revenue over 24 months, which is not a third quarter cash receipt. Ashkenazi said TPU systems in customer data centers will produce only a small share of revenue in 2026, with the vast majority in 2027. A 2027 chip-revenue ramp is not the 2027 capex dollar the company has not given.
“As we previously shared, we continue to expect our CapEx to increase significantly in 2027, and we’ll provide more details at a later date,” Ashkenazi said in July. The third quarter exhibit does not add that date or that dollar.
Cloud customers, and the other reports tonight
On the July call Pichai said nearly 90 percent of the Fortune 100 were using Gemini Enterprise, naming PepsiCo, HSBC, Morgan Stanley, and Pfizer. Those names sat inside a capacity constraint. The third quarter Cloud print of 103 percent is what got through it.
Search slowed relative to the preview, and Cloud did not. Search and other was $63,350 million, up 12 percent, against the 14.8 percent FactSet expected. YouTube ads were $11,207 million, up from $10,261 million. In the second quarter Search and other was $63,271 million, up 17 percent, and YouTube ads were $11,055 million, up 13 percent. Ashkenazi had said the third quarter would start to lap last year’s Search acceleration.
Microsoft’s year-end path, from the 23 October close, is a separate distribution. The overlap is whether 2027 spending gets a number. Nvidia’s session into this print is the other side of the invoice. Alphabet’s servers are an order for accelerators, including the Nvidia systems Pichai said sit alongside Google’s own TPUs.
Power is the part of the bill that is not a chip. Constellation’s 6 October move followed a Google contract for 890 megawatts and $4.3 billion. That purchase is not a line in the July capex range. It is the sort of commitment that keeps 2027 spending high even if one Cloud quarter disappoints.
“Our cloud business is at any given moment in time forgoing short-term revenues because we are making compute tradeoffs to support frontier AI development,” Pichai said, as posted by Alex Kantrowitz on 21 October. On the July call he said the company had become more bullish on the returns over the past year. The bullishness and the withheld revenue are the same policy.
The distribution through 31 December
The prices in the headline are one formula on one series, not FactSet’s revenue estimate and not a published analyst target. Take the last 90 daily log-returns in the saved Nasdaq file, ending with Tuesday’s close. The log-return is the natural log of one close divided by the prior close. The mean, mu, is -0.00164721. The sample standard deviation, sigma, dividing by 89, is 0.02024604. The largest absolute return in the window is 23 July, a log-return of -0.07143, the move from $341.91 to $318.34. That day was not dropped.
N is 45. The sessions from this close through 31 December 2026 are 28, 29, and 30 October (3), the November weekdays except Thanksgiving on Thursday 26 November (20, and the early close on Friday 27 November still counts), and the December weekdays except Christmas on Friday 25 December (22, and the early close on Thursday 24 December still counts). Three plus 20 plus 22 is 45. The base is the close times e to the power of N times mu. The bull adds 1.5 sigma times the square root of N. The bear subtracts 1.0 sigma times the square root of N. The square root of 45 is 6.70820. Rounded to the cent, the base is $294.19, the bull is $360.67, and the bear is $256.83.
The base is under the close because mu is negative. That describes the last 90 sessions, including the July drop and the give-back from $375.35 on 4 August. The bull at $360.67 is 13.84 percent above $316.83 and sits under the 18 May high of $404.47. The bear at $256.83 is 18.94 percent below the close and under the chart window low of $264.94.
Case
Price
Versus $316.83
What has to be true
Bull
$360.67
+13.84 percent
45 sessions of the recent drift plus 1.5 sigma. The 2026 range is not raised again the way it was on 22 July.
Base
$294.19
-7.15 percent
Drift only. The mean of the last 90 daily log-returns stays the path.
Bear
$256.83
-18.94 percent
Drift minus 1.0 sigma. A 2027 dollar at or above FactSet’s $312.217 billion, or another raise of the 2026 range, is the fundamental version of this path.
The pair does not reuse an English FinanceFeeds title. The 15 October Class A piece used $420.44 and $289.20. Older Class C pages used $475 and $300, $485 and $295, and $460 and $235. None of those bulls is within a dollar of $360.67, and none of those bears is within a dollar of $256.83.
The financing tension behind the range
Alphabet is not funding the build from operating cash flow alone. The second quarter release reported net proceeds of $49.6 billion from stock and mandatory convertible preferred, and $20.3 billion from notes. The at-the-market program had sold nothing as of 30 June. June cash and marketable securities were $242.5 billion, and long-term debt was $98.2 billion.
Third quarter operating cash flow was $42.3 billion against property and equipment purchases of $51.4 billion, so free cash flow was negative $9.1 billion. Trailing twelve month free cash flow was $19.7 billion. Nine-month purchases were $131,953 million. Set against the July range of $195 billion to $205 billion, that leaves $63,047 million to $73,047 million for the fourth quarter. The release does not reprint that range and does not number 2027. In the quarter the company sold 12 million Class A shares for net proceeds of $4.3 billion and 24 million Class C shares for $8.1 billion, with $27.6 billion still unsold on the at-the-market program, and it issued notes for net proceeds of $28.7 billion. Cash and marketable securities were $265.1 billion at 30 September. Long-term debt was $125.1 billion.
The third quarter of 2025 included a $3.5 billion European Commission charge. Excluding it, Alphabet said the margin was 33.9 percent against a reported 30.5 percent. This quarter’s operating margin of 31.8 percent is a different comparison, and the release does not attribute it to that fine. Jeff Dean’s August departure is a talent item, not a line in this revenue table. Pichai’s release quote says the company is on a half-trillion dollar revenue run rate. Ashkenazi’s 2027 dollar is still not in the exhibit.
What happens next
The first dated test is now the official close on Thursday 29 October. The release is in. Revenue was $365 million under FactSet, diluted earnings per share were $2.12 against a $3.01 consensus, Cloud growth was 103 percent, and free cash flow was negative again. The exhibit does not raise the July capex range and does not number 2027. July’s drop followed a higher guide, not a missed revenue number. This print is a different mix. The bull at $360.67 is still 45 sessions of drift and volatility, not Thursday’s print.
The second test is the 2027 sentence, which the exhibit still does not contain. A later figure at or above FactSet’s $312.217 billion would make the July tape the precedent, and $256.83 the distribution’s downside. The cash version of that path is already on the page: free cash flow went from negative $5.9 billion to negative $9.1 billion, and nine-month property and equipment purchases are $131,953 million. A figure well under that consensus would not rewrite mu. It would say the Street’s 2027 number was ahead of the company.
The Cloud margin marker did not print the way the preview framed it. Operating income of $11,121 million on revenue of $30,709 million is 36.2 percent, up from 35.6 percent, not down. The release also says TPU system sales were a meaningful contributor to Cloud growth, which is a different sentence from July’s warning that this year’s TPU revenue would stay small. Through 31 December the base case remains $294.19, because the last 90 sessions have a negative mean. This is not financial advice.
Frequently asked questions
What is the GOOG stock prediction after the third quarter print?
From the Nasdaq close of $316.83 on 27 October 2026, the path through 31 December is a bull of $360.67, a base of $294.19, and a bear of $256.83. The three prices use 45 sessions and the last 90 daily log-returns through Tuesday. They are not a Wall Street target. The third quarter release is already in, and it does not change this formula.
How does AI spending change the GOOG prediction?
The third quarter release spent $51.4 billion on property and equipment and printed free cash flow of negative $9.1 billion. It does not replace the July guide of $195 billion to $205 billion for 2026, and it does not number 2027. FactSet’s 2027 consensus is still $312.217 billion. The bear is the path if that figure arrives at or above the Street number and the recent tape persists.
Why is the bull $360.67 when older targets were much higher?
The bull is the close times an exponential of the recent drift plus 1.5 standard deviations over 45 sessions. It is 13.84 percent above $316.83. Older FinanceFeeds pages used $420.44, $460, $475, and $485 off earlier prices and different methods. Those pairs are not this calculation. A Street average from June or August is a separate number.
What did GOOG do the last time capex was raised?
On 22 July 2026 the range went from $180 billion to $190 billion up to $195 billion to $205 billion, on a day Cloud revenue was reported up 82 percent. The close that day was $341.91. The next close, 23 July, was $318.34, down 6.89 percent. The shares later reached $375.35 on 4 August and then fell to Tuesday’s $316.83.
Is Wednesday’s live price the one in this prediction?
No. At 3:29 p.m. Eastern on 28 October, with the Nasdaq cash session still open, the last sale on the quote page was $320.86, up 1.27 percent. A live sale is not an official close. The chart ends on Tuesday 27 October at $316.83, and the bull, base, and bear use that close only.
Does this cover GOOGL as well as GOOG?
No. GOOG is Class C capital stock. The 15 October FinanceFeeds piece used Class A, ticker GOOGL, and a Wednesday 14 October close of $347.64. That maths is not repeated here. The two classes can trade at different prices, so a Class A close is not a substitute for the Class C series on this chart.