Author

admin

Browsing

Eating healthy is becoming increasingly difficult for Americans as grocery bills rise. Even shoppers who prioritize organic and natural products are reconsidering their spending.

Sprouts Farmers Market is feeling that pressure as customers become more selective about their grocery purchases.

But rather than scaling back, the specialty grocer is introducing new products, expanding affordable prepared meals, and preparing a nationwide pricing overhaul to make healthier food more accessible.

Sprouts launched more than 1,400 unique products during its third quarter, according to its Oct. 28 earnings presentation.

It also reported strong adoption of its loyalty program and opened a record 15 stores.

Now, incoming CEO Nick Konat has confirmed plans to reduce prices on healthy and holiday essentials nationwide, with a broader pricing strategy to follow in January 2027.

Sprouts faces affordability challenge

Recent foot traffic data suggests Sprouts’ existing stores began to stabilize after a difficult first half.

According to an Oct. 21 Placer.ai report, visits to established locations declined just 0.1% year over year in the third quarter, compared with a 4.1% decline in the previous quarter.

However, performance varied across major markets:

  • Florida: Visits increased 2.2%.
  • California: Visits rose 1.1%.
  • Arizona: Visits declined 0.6%.
  • Texas: Visits fell 3.2%.

Placer.ai found stronger performance in markets where shoppers’ household incomes were closer to their state’s median income, suggesting that Sprouts may be becoming a regular grocery destination in some communities rather than an occasional specialty stop.

Still, affordability remains a challenge. In an Oct. 23 research note, UBS analysts estimated that roughly half of Sprouts’ customer households earn less than $100,000 annually, despite the retailer’s relatively affluent customer base.

That pressure was reflected in Sprouts’ latest results. Total sales increased 5% to $2.3 billion, helped by new stores, but comparable-store sales declined 0.9%.

Transactions at existing stores fell 3.3%, while average transaction size increased 2.5%, indicating that fewer shopping trips were partially offset by higher spending per transaction.

The company expects comparable sales to decline another 2% to 4% during the fourth quarter.

During its Oct. 28  Q3 2026 earnings call, Konat acknowledged that weaker shopping frequency was no longer limited to less-engaged, lower-income customers.

Sprouts is beginning to see even its core customers purchase fewer items and make slightly fewer trips.

Sprouts plans nationwide grocery price cuts and changes

This slowdown has prompted Sprouts to develop a more substantial response.

“Our current pricing strategy has not delivered against that goal,” Konat said, referring to making healthy eating more affordable.

Sprouts plans to introduce lower prices on selected healthy and holiday staples across the country before rolling out a rebuilt national pricing strategy in January.

During the call, Konat identified three areas where the company intends to improve affordability:

  • Lower-priced entry options: Products such as Sprouts Brand cage-free eggs and raw almonds
  • Frequently purchased essentials: More competitive pricing on conventional produce
  • Premium healthy-food staples: Items important to Sprouts shoppers, including organic grass-fed beef

Actual price reductions and savings amounts have not yet been announced.

“This is not a shift to broad-based discounting,” Konat said.

Instead, the company wants to improve prices on products customers regularly buy while keeping its specialty assortment.

Sprouts’ earlier pricing experiments produced mixed results. Discounts helped customers purchase more items in certain categories but did not consistently increase the frequency of return visits.

The latest strategy will cover a much broader selection, with pricing adjusted according to the market and the products shoppers consider most important.

Sprouts will cut prices and add more assortments.

krblokhin / Getty Images

Sprouts expands healthier products and affordable meals

Product innovation is core to the retailer’s strategy.

The 1,400-plus items launched in the third quarter followed approximately 1,300 additions in the previous quarter.

Sprouts has been expanding organic, protein-rich, high-fiber, and seed-oil-free options, alongside products addressing specific nutritional needs.

During its July earnings call, management highlighted additions including Pasturebird chicken and Better Than Pop.

The chain has also been promoting prepared meals as alternatives to restaurant takeout.

Previously announced offerings include:

  • $29.99 family meals for four
  • Fresh-made salads below $9
  • Wellness bowls priced below $10
  • Fresh-baked organic sourdough bread for $4

Prices and availability may vary by location.

Konat said innovation is performing well in the frozen foods, bakery, and deli departments, particularly in products that combine health, convenience, freshness, and value.

Interestingly, broader eating trends may favor Sprouts.

A Cornell University study found that households using GLP-1 medications reduced grocery spending by an average of 5.3% within six months, with particularly sharp declines in snacks and sweets.

While some healthier products gained popularity, the findings suggest consumers may be eating differently without necessarily spending more on groceries.

That raises a question for Sprouts. How can a retailer specializing in healthier food persuade shoppers to visit more often?

Sprouts improving produce prices and freshness

Produce remains another major focus.

Sprouts acknowledged growing competition from conventional supermarkets, particularly in produce categories where shoppers can easily compare prices.

Konat said the company has performed well in organic produce but sees room to improve pricing on conventional fruits and vegetables.

More Retail:

The retailer is also working to improve freshness and reduce waste.

Management explained that slower product turnover can affect produce quality, making it important to sell fresh items more consistently.

Sprouts plans to simplify some in-store processes and improve inventory management to address the issue.

The retailer also faced disruption from the cyclospora outbreak earlier this year.

As TheStreet reported in July, a major Taco Bell supplier pulled lettuce after concerns about contaminated produce.

Sprouts estimated that the broader disruption reduced third-quarter comparable-store sales by 0.6 percentage points, although it did not identify that supplier’s recalled lettuce as a product sold in its stores.

During the latest call, management said the disruption peaked around August and early September and has gradually eased, although it remains a slight headwind.

Sprouts bets on loyalty rewards and personalized savings

Loyalty programs are becoming increasingly important as retailers compete for shoppers making fewer trips.

As TheStreet recently reported, convenience-store loyalty members visit their preferred retailers more frequently than nonmembers, although satisfaction with rewards apps has declined.

Grocery chains are pursuing similar strategies. Safeway and Vons recently reduced the price of their paid grocery memberships while removing several benefits.

Sprouts takes a different approach through its free Sprouts Rewards program. Members earn five points per dollar on eligible purchases, with 1,000 points redeemable for a $2 reward.

The program also offers personalized coupons, exclusive promotions, and bonus-point opportunities.

Konat said Sprouts is preparing to make greater use of customer data to develop more relevant product recommendations, offers, and shopping experiences.

The company wants to move beyond simply promoting individual dietary attributes, such as gluten-free products, toward helping customers find solutions for broader wellness goals, including gut health.

Sprouts expands delivery and considers store improvements

Despite weaker sales at established locations, Sprouts continues to expand.

The company opened 15 stores during the third quarter, bringing its total to 504 locations across 25 states. It still expects 42 net-new stores in 2026.

But existing stores could also see changes. Konat said Sprouts is evaluating ways to refresh older locations, improve how customers discover new products, and better highlight fresh foods.

Tests are being prepared, although the company has not announced a chainwide remodeling schedule.

Online shopping is another bright spot. Sprouts reported 12% e-commerce growth during the third quarter, with digital orders accounting for more than 16% of total sales.

As TheStreet previously reported, the retailer also partnered with Shipt to offer same-day delivery from more than 500 stores, complementing Instacart, DoorDash, and Uber Eats.

The changes come ahead of a leadership transition in January 2027, when Konat will succeed Jack Sinclair as CEO.

For shoppers, Sprouts’ next chapter promises more affordable healthy essentials, new specialty products, personalized savings, and potentially refreshed stores.

The first changes will begin as early as the holiday shopping season, and the broader nationwide pricing strategy is scheduled for January.
Latest Retail News

Visa Inc (V) delivered another quarter of double-digit growth late on Tuesday, reporting fiscal Q4 revenue of about $12.14 billion and adjusted earnings per share (EPS) of $3.48.

Revenue increased 13% from a year earlier, while adjusted EPS came in up 17% – both ahead of $12.09 billion and $3.44 a share consensus.

The earnings release demonstrate continued strength in digital payments, although investors face a more demanding question after Visa stock’s recent rally – how much of that resilience is already reflected in its price?

Spending held up, but Visa growth moderated in Q4

Visa’s payments volume increased 9% in constant currencies during the September quarter, easing from 10% growth in the preceding quarter.

That suggests spending remained resilient, although the pace moderated after a stronger spring.

For investors, the distinction matters.

Continued expansion supports Visa Inc.’s transaction-driven business – but a modest slowdown makes it harder to build an investment case around accelerating consumer demand.

Revenue nonetheless grew faster than payments volume.

That’s encouraging, but the two measures are not interchangeable: V’s revenue also reflects pricing, transaction characteristics, and services beyond basic payment processing.

The investment takeaway is that healthy spending remains a foundation for earnings.

Sustaining faster revenue growth requires Visa to keep increasing what it earns from its broader network, alongside attracting more payment activity.

Cost discipline offers encouraging signal for Visa stock

Visa’s earnings presentation showed adjusted operating expenses climbing 12%, slightly below its 13% revenue increase.

On an adjusted constant-dollar basis that also removes acquisition effects, revenue increased 12%, and expenses rose 11%.

That indicates modest operating leverage, with sales expanding faster than the costs needed to support them.

The comparison with the previous quarter is constructive. Q3 adjusted expenses had soared 17%, outstripping revenue growth of roughly 14%.

For Visa shares, restoring that relationship matters because sustained cost growth above revenue eventually compresses profitability.

This quarter offers evidence of improvement – although the narrow gap leaves “limited room” for complacency.

Further progress would strengthen the argument that Visa Inc can deliver attractive earnings growth without depending on faster consumer spending.

A solid quarter still needs a sensible purchase price

Valuation remains the hurdle for prospective buyers. Ahead of the release, V stock traded at about 27x forward earnings, compared with roughly 23x in March.

That creates an asymmetric challenge: dependable execution can support the business while still producing an underwhelming share-price return if expectations are already ambitious.

All in all, the quarter strengthens the case for keeping Visa on a long-term watchlist.

It offers less justification for buying at any price.

Investors considering a position should assess subsequent earnings-estimate revisions against the purchase multiple.

A higher profit forecast would provide firmer support for the shares; an unchanged forecast would leave future returns more dependent on an already generous valuation.

The post Visa Q4 profit jumps: can earnings keep pace with the stock? appeared first on Invezz

Gold can be expected to rise further toward the next resistance level 4100.00 (former support from the start of October).

  • Gold reversed from round support level 4000.00
  • Likely to rise to resistance level 4100.00

Gold recently reversed up from the support zone between the round support level 4000.00 (which has been reversing the price from June, as can be seen from the daily Gold chart below), support trendline of the daily down channel from September and the lower daily Bollinger Band. The upward reversal from this support zone created the daily Japanese candlesticks reversal pattern Bullish Doji, which stopped the earlier impulse wave (C) of the primary ABC correction 2 from the end of August.

Given the strength of the support level 4000.00 and the cautiously bullish sentiment seen across the precious metal markets today as the oil pullback eases US inflation fears, Gold can be expected to rise further toward the next resistance level 4100.00 (former support from the start of October).

The subject matter and the content of this article are solely the views of the author. FinanceFeeds does not bear any legal responsibility for the content of this article and they do not reflect the viewpoint of FinanceFeeds or its editorial staff.

The information does not constitute advice or a recommendation on any course of action and does not take into account your personal circumstances, financial situation, or individual needs. We strongly recommend you seek independent professional advice or conduct your own independent research before acting upon any information contained in this article.

Your traditional grocery chain costs more than shopping at Walmart, Aldi, and Costco.

That’s something we’ve seen doing live price comparisons at TheStreet that’s backed up by a more extensive study done by Consumer Reports.

In addition, grocery giants Kroger and Albertsons both admit that they can’t compete on price.

“We are not in the game of being the cheapest because we do not have the lowest costs. But we can provide the best value,” Kroger CEO Gregory Foran said during his chain’s second-quarter earnings call.

Albertsons CEO Susan Morris said almost exactly the same thing during her company’s Q2 earnings call.

“Our goal is not to be the cheapest guy in town, but rather to have the right balanced value proposition that resonates with the customers that we serve uniquely by market,” she said.

Price Chopper, a smaller chain that’s a major player in the Northeast, does not agree. It has launched a new banner designed to be the cheapest option for grocery shoppers.

Price Chopper’s new brand offers price transparency

Retailers rarely offer transparency when it comes to prices. That’s at least partially because on many items, the markup is fairly high, or would seem high to consumers who don’t understand all the costs of running a store.

Back in my retail days, for example, many products were “keystoned,” which means sold at double the price we acquired them for. That’s a 50% retail margin, and it helped cover the fact that some items we sold, Legos being the largest brand, were sold at manufacturer-set prices that gave us a 30% margin.

Since our operating overhead was around 40%, we actually needed to sell some items over that number to offset the ones that fell below it.

Retailers generally don’t share their markup or retail margin numbers; the Peterson Institute for International Economics (PIEE) publishes a study showing markup and margins for 13 national chains, with Costco and Walmart having the lowest markups.

  • Costco markup 14.4%, margin 3.6%
  • Walmart markup 32.2%, margin 4.2%

Only Kroger had a lower markup among grocery chains than Walmart, coming in at 28.6% while only showing a margin of 2.1%. Aldi and Lidl, two discount grocery chains with a national footprint were not on the list.

“Markups are calculated by subtracting the cost of goods sold from sales, then dividing the result by the cost of goods sold. Retail margins are calculated as operating income divided by sales. The markup average is 48%, and the retail margin average is 6%,” according to PIIE.

Costco marks goods up less than Walmart, but only makes a slightly lower margin because of its lower operating costs and cheaper cost of acquiring goods.

Price Chopper’s new store, ChopMore by Price Chopper, offers full pricing transparency.

“You pay cost plus 10% at checkout,” the company shared on its website.

Price Chopper launches a discount brand

Price Chopper’s ChopMore model looks a lot like the business model being used by Mark Cuban’s Cost Plus Drugs, which marks up all the prescriptions it fills by 15%.

“We calculate our 15% markup by multiplying the price we pay for the medication by 0.15. This gives us the markup we add to the original price. For example, if the medication costs us $50, the markup would be $50 x 0.15 = $7.50. We then add that $7.50 to the original $50, plus any pharmacy labor and shipping fees,” the company shared on its website.

That’s an online-only company without the costs associated with running a storefront. Operating a grocery chain that does not charge a membership fee like Costco and only marking items up 10% seems like a very challenging business model

Price Chopper’s parent company said it’s able to offer such ChopMore discounts by cutting expenses in other areas.

“Stack it high and sell it low. No marketing, no ads, no gimmicks, no loyalty cards,” Executive Vice President John Cosentino told KCUR. “Some products are in bins. Pallet drops on the endcaps. So it’s a different way of merchandising. Quicker, less labor.”

More retail:

The new store, which replaced a traditional Price Chopper, will operate with fewer employees.

“The former Price Chopper store in the space had about 100 employees a year ago. ChopMore now has about 60. But the company did not lay off workers. Instead, it gradually downsized through attrition,” Startland News reported.

Price Choopper is going for even lower prices at ChopMore.

Shutterstock

10% is a really low markup

As a former retailer, I have a hard time believing that ChopMore can operate profitably on a 10% margin.

“Look, a 10% markup sounds great until you realize that’s only about a 9% gross margin. From that little slice, you’ve got to pay the employees, keep the lights on, cover rent, credit card fees, and pay for all the food that spoils before somebody buys it,” RTM Nexus CEO Dominick Miserandino told TheStreet.

There’s a reason, he noted, that retailers generally mark their prices up higher than that.

“The only way this works is by moving an enormous amount of merchandise and keeping expenses incredibly low. Costco has membership fees helping its economics,” he wrote. “Price Chopper doesn’t have that cushion here. They need shoppers coming back constantly, and they need those shelves turning over fast. One bad month could eat up whatever profit they’ve made.”

TheStreet Co-Editor-in-Chief Todd Campbell spent nine years in the grocery business working for Stop & Shop, another leading supermarket chain in the Northeast, and thinks the ChopMore could work.

“Price Chopper seems to be making a market share play to gain scale. Grocery operates on razor-thin margins, which is why so many have turned to lower-cost private label, like Aldi,” said Campbell. “It’s tough to turn a profit on a 10% markup without cutting services and embracing a bare-bones model.”

Even then, he added, with Walmart and Costco’s pricing power, “ChopMore may not be the cheapest option.”

Related: Ollie’s, Five Below, and Dollar General see troubling sales trend

Galaxy Digital stock has slumped sharply in recent months and is now hovering at its lowest level since April last year. It dropped to $14.68, more than 68% below its 2025 peak, erasing billions of dollars in market value. The decline may continue in the near term as crypto prices fall and AI jitters intensify.

Galaxy Digital stock technicals points to more downside

The daily chart shows that GLXY stock has come under pressure in the past few months, moving from a high of $36.11 in June to the current $14.68. 

A closer look shows that the stock has dropped below the important support level of $16.67, its lowest level in February and April, respectively. The stock formed a death cross pattern, which happens when the 50-day and 200-day moving averages cross each other. 

Galaxy Digital remains below the Supertrend indicator, a sign that bears are in control. Also, the Average Directional Index (ADX) has soared to 28.2, its highest level since May 18 this year. The rising ADX is a sign that the downward trend is gaining momentum. Therefore, the stock will likely continue falling, potentially to the important support level of $10. 

GLXY stock chart | Source: TradingView

Galaxy Digital is facing crypto and AI headwinds

GLXY faces twin headwinds, which explains its continued downward trend. One of the risks is the ongoing crypto market retreat that has affected Bitcoin and other altcoins.

The most recent results showed that its revenue dropped by 15% to $8.71 billion as the crypto winter continued. Its net loss came in at over $85 million, and this trend will likely continue as long as the crypto market is wavering. 

Galaxy Digital is also falling because of the ongoing fears about the artificial intelligence industry. This is important because the company is spending millions of dollars building data centers, with CoreWeave, the embattled neocloud being its biggest client. CoreWeave, despite its $104 billion backlog, is facing substantial risks, pushing its bond yields to 15%.

The next important catalyst for Galaxy Digital will be its upcoming earnings report, which will provide more color on its business. The average estimate among analysts is that its third quarter revenue will be $12.1 billion, down by 70% from a year earlier. For the year, analysts expect its revenue will be $52.5 billion, down by 37% from last year. 

Still, the options market suggests that the stock will rebound after earnings. It has a put/call ratio of 0.26, with most of the call options being concentrated at $16, up by 10% from the current level. 

Another positive is that some analysts believe that the stock will rebound in the near term. Maxim Group sees the stock rising to $36, while Piper Sandler expects it to jump to $25. Citigroup and Morgan Stanley is expected to hit $28 and $43, respectively. 

The post Galaxy Digital stock is crashing: will its earnings turn the tide? appeared first on Invezz

Apart from central banks, US PCE and US and EU GDP fill out a packed week of data.

The week ahead features a range of important events on the economic calendar, most notably the meetings of the Federal Reserve (Fed) and the European Central Bank (ECB). With no news of major new American attacks on Iran over the weekend, for now the conflict in the Gulf is out of focus as traders concentrate on monetary policy and GDP from various countries. This article looks ahead at the releases in the next few days then briefly analyses the charts of gold and euro-dollar.

The Bank of Canada (BoC), Reserve Bank of New Zealand (RBNZ), Fed, ECB and Bank of Japan (BoJ) are all meeting over the next few days with the BoC and RBNZ both expected to hike rates. The probability of the Fed holding is very high at around 90%; for now, participants are pricing in hikes by both the Fed and ECB in December. The BoJ’s meeting has perhaps the most intrigue surrounding it given the disagreement among the board about the pace of hiking, so it’d be possible to see some indication of another hike towards the end of the year or early 2027.

At least one more hike by the Fed before the end of the year is favourable with a cumulative probability of around 80% according to CME FedWatch:

Although there was a brief surge in the likelihood of a hike this week immediately after 14 October’s stronger inflation, with hold and single hike briefly being about 50-50, this subsided quite quickly. Kevin Warsh’s recent comments about economic conditions matching expectations overall and an overall slower job market reduce the pressure on the Fed to hike quickly although inflation might continue to rise given oil’s recent gains.

In the eurozone traders have concentrated on yields from bonds and civil instability in France over recent weeks with the euro suffering against most currencies. Friday’s GDP data, eurozone-wide and from various major individual countries, is expected to be somewhat weaker on the whole. Global political news shifted to the results of Brazilian and Serbian elections on Monday while traders are looking ahead to the British budget on Wednesday and of course the American midterms next week.

Gold back at $4,000 but immediate continuation doubtful

After a relatively large intraday loss on 22 October, gold has held around $4,000 as participants await the Fed’s meeting on Wednesday and the possibility of hostilities in the Gulf heating up again. With no significant changes to expectations for American rates by the end of the year in recent days, the focus is also on American GDP and PCE coming on Thursday 29 October.

$4,000 seems to be a strong support for now at least as the area of summer’s triple bottom and only slightly below the 38.2% weekly Fibonacci retracement. Now that the slow stochastic signals oversold and the price is close to selling saturation from Bollinger Bands, a bounce might be more likely than a strong push lower in the runup to the Fed’s meeting.

$4,100 would be a possible short-term target slightly below the 20 SMA. Volume is likely to remain relatively low in the next couple of days as most participants avoid large volumes ahead of major news and data. Advance GDP for last quarter on Thursday 29 October is also a key release given that expectations of around 3.2% are quite high considering the context from jobs and inflation.

Key data this week

Bold indicates the most important releases for this instrument.

Tuesday 27 October

  • 12.30 GMT: American durable goods (September) – consensus 1.5%, previous nil

Wednesday 28 October

  • from 18.00: meeting and press conference of the Federal Reserve – consensus 3.75-4% (no change)

Thursday 29 October

  • 12.30: American GDP (Q3 advance) – consensus 3.2%, previous 2.2%
  • 12.30: American annual headline PCE (September) – consensus 3.6%, previous 3.4%
  • 12.30: initial jobless claims (24 October) – consensus 200,000, previous 194,000

Euro-dollar holding around $1.12 ahead of central banks’ meetings

The euro has suffered in most of its pairs in recent weeks as yields from French bonds increased above 5% and have held near there while markets are also worried about France’s fiscal situation. The ECB is likely to hold rates on Thursday 29 October but a hike seems possible in December. The current differential then is likely to remain 1.25-1.5% in favour of the dollar for the next couple of months.

$1.12 seems to be a support with the price having lacked momentum to push clearly below there in the last fortnight despite stronger American inflation and the situation in France. The large tail of 14 October’s candlestick suggests demand in this zone. Given the fundamental situation, though, possible gains in the next few days are unlikely to be more than a short-term bounce unless upcoming data are particularly surprising.

With no sign of saturation as the slow stochastic is slightly closer to neutral than overbought, the price could bounce to around $1.13 or possibly slightly higher before resuming the overall downtrend. However, this depends on a variety of data due in the next few days, so it’s important to watch the reaction to GDP, inflation/PCE and, to a lesser extent, the German job report as well as the central banks’ meetings.

Key data this week

Bold indicates the most important releases for this instrument.

Tuesday 27 October

  • 12.30 GMT: American durable goods (September) – consensus 1.5%, previous nil

Wednesday 28 October

  • from 18.00: meeting and press conference of the Federal Reserve – consensus 3.75-4% (no change)

Thursday 29 October

  • 12.30: American GDP (Q3 advance) – consensus 3.2%, previous 2.2%
    • 12.30: American annual headline PCE (September) – consensus 3.6%, previous 3.4%
    • 12.30: initial jobless claims (24 October) – consensus 200,000, previous 194,000
  • from 13.15: meeting and press conference of the European Central Bank – consensus 2.5% (deposit rate; no change)

Friday 30 October

  • 6.30: French quarterly GDP (Q3, preliminary) – consensus 0.1%, previous nil
  • 7.45: French annual headline inflation (October, preliminary) – consensus 3.2%, previous 3.1%
  • 8.55: German unemployment (October) – consensus 6.4%, previous 6.4%
  • 9.00: German quarterly GDP (Q3, flash) – consensus 0.1%, previous 0.3%
  • 10.00: eurozone-wide quarterly GDP (Q3, flash) – consensus 0.2%, previous 0.6%
  • 10.00: eurozone-wide unemployment (September) – consensus 6.4%, previous 6.4%
  • 13.00: German annual headline inflation (October, preliminary) – consensus 3%, previous 3.3%

For the latest analysis, ideas for trading and more, follow Michael on X: @MStarkExness.

The opinions in this article are personal to the writer; they do not represent those of Exness. This is not a recommendation to trade.

Between severe weather hitting the islands that make up Hawaii and high prices in an economic environment that leaves many watching their discretionary spending more carefully, traveler numbers to the state have declined throughout 2026.

According to numbers released by the state’s Department of Business, Economic Development and Tourism, the 772,039 visitors who came to the state in August 2026 represent a 5.6% decrease from the same month a year ago. The $1.59 billion they spent amounts to a 9.7% decrease.

As a result, a number of businesses in the tourism industry have faced a challenging year. Still others have had challenges going back years.

Hawaii Ocean Plaza files for Chapter 11 bankruptcy

Hawaii Ocean Plaza filed for voluntary Chapter 11 bankruptcy protection, listing between $10 and $50 million in liabilities and the same amount in assets, a case filed in California Central Bankruptcy Court revealed.

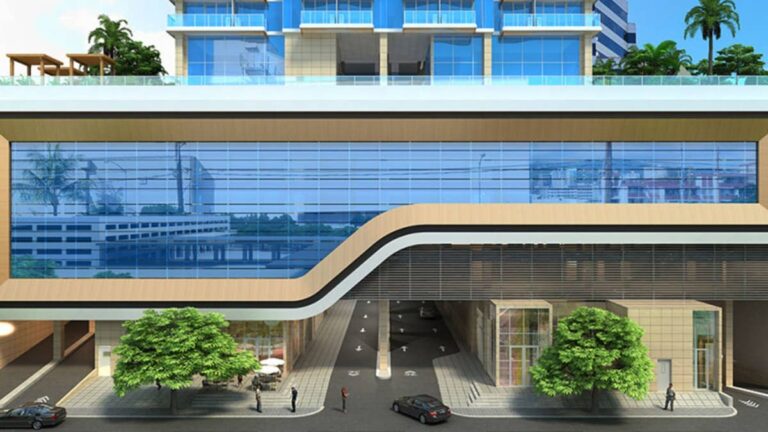
Hawaii Ocean Plaza is the company behind the 40-story mixed-use development project on Kapiolani Boulevard next to the large Ala Moana Center outdoor shopping mall in Honolulu. The building was envisioned as having 175 hotel rooms and 216 residential units.

Related: Former operator of Sheraton hotel files for Chapter 11 bankruptcy

Plans for the new tower presented by developer Johnson Fang were approved by the City and County of Honolulu in 2017, but construction stalled over the years amid mounting debt and lapsed permits, KITV4 reported.

By 2023, foreign investors who had initially backed the project began filing lawsuits over lack of progress.

Some of these investors claimed they were promised visas in exchange for pumping more than $1 million into the project, KITV4 noted. Yet overgrown weeds, broken fencing, ripped tarp, and general disarray were observed at the site where construction was supposed to begin.

“When these investors invested either half a million or a million dollars into this EB 5 [immigration investment] program, the understanding was that the developer would build the project and they would hire the lawyers,” wrote Andrew Daisuke Stewart, the attorney representing Japanese investor Kiyohito Nishibayashi, according to KITV4.

Early renderings show the original vision for Hawaii Ocean Plaza.

Hawaii Ocean Plaza

What went wrong with the Hawaii Ocean Plaza residential and hotel development project?

As of October 2026, 27 foreign investors are involved in litigation related to the project, an X post from RK Consultants confirmed.

Earlier in October, the Hawaii Supreme Court rejected an investor request for a writ of certiorari, the legal term for a request to have a case sent up from a lower court. This came as multiple interconnected lawsuits from both individual investors and corporate entities accused the company behind the development project of fraud.

More Travel News:

Hawaii Ocean Plaza and Johnson Fang could not immediately be reached for comment on the bankruptcy filing. Judge Neil W. Bason is currently listed as assigned to the case.

The total number of creditors is listed as between 1 and 49. Additional details regarding the bankruptcy and the private company’s financial situation have not been made public.

Despite being a single-entity company that’s building in Hawaii, Hawaii Ocean Plaza is registered in Alhambra, California.

The lot, where the development project is currently listed as “permanently closed” on Google, is in a prime real estate area of Honolulu.

Related: Hotel minutes from Disneyland shuts in Chapter 11 bankruptcy