Author

admin

Browsing

var adServerUrl = “”;
var $el = $( “#video_container-891887” );
var permalink = $el.closest(‘.snet-single-article’).data(‘permalink’);

$el.after( unescape(“%3Cscript src=”” + (document.location.protocol == “https:” ? “https://sb” : “http://b”) + “.scorecardresearch.com/beacon.js” %3E%3C/script%3E”) );

$( document ).one( ‘ready’, function() {
$( “#video_container-891887” ).SNPlayer( {
bc_account_id: “1704050871”,
bc_player_id: “JCdte3tMv”,
//autoplay: false,
//is_has_autoplay_switch: false,
bc_videos: 6406189254112,
is_has_continuous_play: “false”,
section: “”,
thumbnail: “https://www.sportsnet.ca/wp-content/uploads/2026/10/6406189254112-1024×576.jpg”,
direct_url: “https://www.sportsnet.ca/nhl/video/gotta-see-it-marchenko-beats-ullmark-for-first-goal-as-a-maple-leaf/”
});
});

US stocks ended higher on Friday after weaker-than-expected September jobs data reduced expectations for a Federal Reserve rate hike later this month.

The Dow Jones Industrial Average rose 260 points, or 0.51%, while the S&P 500 gained 0.76% and the Nasdaq Composite advanced 1.19%.

The Nasdaq briefly reached an all-time high during the session before retreating from its peak as Treasury yields rebounded.

Despite Friday’s gains, the Dow and S&P 500 posted weekly declines, while the Nasdaq extended its recent run of gains.

Weak jobs data lifts stocks

The US economy added 29,000 jobs in September, well below the 84,000 increase expected in the Dow Jones consensus and the 90,000 estimate in a Reuters poll.

The unemployment rate rose to 4.2% from 4.1%.

Payroll figures for the previous two months were also revised lower, adding to evidence of weaker labour-market conditions.

The data prompted traders to reduce expectations for an October rate increase.

According to CME FedWatch data cited in the reports, the probability of the Fed leaving interest rates unchanged at its October meeting rose to 77% from around 76% a day earlier.

Reuters data showed that expectations for at least a 25-basis-point rate hike fell to 22.7%, from 24.4% in the previous session and 64.2% a week earlier.

Treasury yields initially declined following the jobs report but later recovered, limiting the gains in equities.

Tech stocks lead market gains

Technology stocks were among the strongest performers as investors increased exposure to risk-sensitive assets.

Nvidia shares reached an all-time high for the first time since May.

CrowdStrike, Palo Alto Networks and AMD also reached record levels.

Megacap stocks including Nvidia and Tesla provided significant support to the S&P 500.

Tesla’s gains helped lift the consumer discretionary sector, which was the best-performing of the 11 major S&P sectors.

Rate-sensitive stocks also advanced. The S&P 500 real estate index gained about 1%, while the small-cap Russell 2000 rose around 1% for its biggest daily gain in a month.

Recent economic data showing resilient activity and slower-than-expected inflation, along with comments from Federal Reserve policymakers cautioning against another rate increase, had already reduced expectations for an October hike earlier in the week.

Weekly losses persist

Despite Friday’s advance, the Dow fell about 1.3% for the week, while the S&P 500 declined around 0.2%.

The Nasdaq gained roughly 0.5% over the week and recorded its third consecutive daily gain.

The Dow and S&P 500 both recorded their fourth weekly decline in the past five weeks, while the Nasdaq posted its fifth weekly gain in the last six weeks.

Outside the technology sector, Nike shares fell after the sportswear company forecast a sharp decline in annual revenue, citing weakness in China.

The company also announced job cuts and changes to its global business divisions.

Data storage stocks also declined. Western Digital and Seagate Technology were among the weakest performers in the S&P 500 technology index.

The declines followed a report that Toshiba plans to double production capacity for hard disk drives used in AI data centres within fiscal 2027.

Oil prices also pulled back after reports that European countries were considering releasing strategic fuel reserves, providing additional support to equities.

The post Dow rises 260 points as weak jobs data lifts US stocks appeared first on Invezz

Updated 2 October 2026: Tesla (NASDAQ: TSLA) was trading at $371.02 at 11:24 ET on 2 October, up 4.8% from Thursday’s $354.11 close (Yahoo Finance quote), after third-quarter deliveries of 486,532 came in 24,558 vehicles above the company-compiled consensus of 461,974.

Verdict: a clean unit beat built on inventory drawdown, with a storage miss underneath. It moves the stock off the bottom of its range but does not settle the $480 vs $268 argument – the Q3 earnings report does that.

Tesla delivered 486,532 vehicles in the third quarter of 2026, beating the 461,974 mean of the 24 analysts Tesla polled itself, and the shares reacted the way a beat on a low bar usually reacts: up roughly 5% in the first two hours of trading. The number is still 2.1% below the 497,099 record of the third quarter of 2025, the last quarter before the US $7,500 clean-vehicle credit expired. Under the headline, Tesla delivered 22,141 more cars than it built and deployed less energy storage than the Street expected.

Key facts

  • Deliveries: 486,532, against a company-compiled consensus of 461,974 (range 421,758 to 482,000) – a beat of 24,558 units, or 5.3% (Electrek, 2 October).
  • Year on year: down 2.1% from 497,099 in Q3 2025. Quarter on quarter: up 1.3% from 480,126 in Q2 2026.
  • Production: 464,391 vehicles, up 2.8% from 451,758 in Q2.
  • Mix: Model 3/Y 478,237 (consensus 450,712); all other models, including Cybertruck, 8,295 (consensus 11,285).
  • Energy storage: 13.7 GWh deployed, below the 15.9 GWh consensus, up from 13.5 GWh in Q2 and 12.5 GWh a year earlier.
  • Year to date: 1,324,681 deliveries through three quarters.
  • Stock: $371.02 at 11:24 ET on 2 October, intraday range $359.41 to $374.36; 52-week range $297.38 to $498.83 (Nasdaq).

What the 486,532 actually says

The beat is real, but it is a beat against a consensus that had already been cut hard. Tesla’s own compilation, published on 29 September, put the mean at 461,974, which was 7.1% below the year-ago quarter. Goldman Sachs had lowered its estimate to 435,000 from 490,000 and Cantor Fitzgerald sat at 421,758, while J.P. Morgan’s 482,000 was the top of the range (Electrek survey, 28 September). Tesla cleared even the highest of those estimates.

The same pattern played out in July, when the compiled mean was 406,024 and Tesla printed 480,126. Two quarters in a row the sell side has underestimated Tesla’s ability to move cars, which is itself information: the consensus process is anchoring on a weaker demand picture than the delivery data shows.

The cars came from inventory as well as from the line. Tesla built 464,391 vehicles and delivered 486,532, so 22,141 units came out of stock. Electrek notes this is the second straight quarter of inventory reduction after Tesla built roughly 50,000 excess vehicles in the first quarter. Clearing inventory is good for cash, but it usually goes hand in hand with price incentives, and that is the margin question the October earnings report has to answer.

The mix also matters. Model 3 and Model Y beat their own consensus line by about 27,500 units, while the “other models” line – Cybertruck, Semi and the remaining S/X – came in roughly 3,000 short of the 11,285 the analysts had pencilled in.

The miss nobody is leading with: storage

Energy storage has been the cleanest growth story in Tesla’s numbers, and this quarter it fell short. Deployments of 13.7 GWh were up 9.6% on a year ago but 13.8% below the 15.9 GWh compiled consensus, and barely above Q2’s 13.5 GWh. The full-year storage consensus in Tesla’s compilation was 56.5 GWh; with three quarters reported, the fourth quarter now has to carry a large share of that figure. For a stock valued well above any car maker, a flat storage quarter is the number the bear side will use.

Why the stock moved, and what it does not change

Tesla came into the print weak. The shares closed at $354.11 on Thursday, down about 21% for the year and trailing every megacap tech peer, and down from $380.12 on 23 September. A stock that had priced in a soft quarter got a quarter that beat every published estimate, so the reaction is mostly relief.

What the delivery report does not change is the valuation gap. On Tesla’s last four reported quarters, diluted GAAP earnings per share sum to $1.08. At $371.02, that is about 344 times trailing earnings. Neither the bull nor the bear target is built on that multiple, but it shows how much of the price depends on robotaxi, Optimus and energy rather than on the 486,532 cars. NHTSA’s audit query AQ26002 on about 1,000 Cybercabs, opened on 3 September, is still open.

Tesla stock scenarios after the delivery beat

Scenario Price vs $371.02 Anchor
Bear $268 -27.8% BNP Paribas Exane, Underperform, target cut to $268 from $280 on 24 September. The case: volumes still below 2025, storage slowing, and a valuation that needs autonomy to deliver.
Base $350 – $400 -6% to +8% The stock holds between Thursday’s pre-print close ($354.11) and the 23 September close ($380.12) plus a margin, until Q3 earnings show whether the inventory drawdown cost gross margin.
Bull $480 +29.4% RBC Capital’s Tom Narayan, Buy, $480 target reiterated 25 September. The case: deliveries have now beaten consensus twice in a row, and the autonomy and energy businesses carry the valuation.

The bear target sits about $103 below the current price and the bull target about $109 above it. That roughly symmetric spread, about 57% of the share price, is the real verdict of the Street: the delivery beat improved the near-term picture without settling the long-term one.

What to watch next

  • Q3 earnings: automotive gross margin ex-credits will show what clearing 22,141 vehicles of inventory cost. Q2 operating margin was 1.4% on $28.236 billion of revenue.
  • Fourth-quarter math: Tesla’s compiled full-year mean of 1,767,255 deliveries now implies about 442,600 in Q4, below the Q3 print. A beat-and-raise of Street estimates is the likely next step for the bulls.
  • Storage recovery: another quarter in the 13-14 GWh band would put the 56.5 GWh full-year consensus out of reach.
  • Cybercab: any NHTSA follow-up to its 21-question Special Order, which was due on 30 September.

Quick take: 486,532 deliveries beat a lowered bar by 5% and lifted Tesla about 5% to $371. Inventory drawdown helped the unit count and storage missed. The range on the stock is still $268 to $480 until the earnings report shows margins.

For the full analyst range set before the print, see our Tesla stock price prediction: $480 bull, $268 bear. For Tesla’s place in the wider stock-linked trading boom, read Nvidia, Alphabet, Apple and Tesla lead Polymarket’s stock-linked trading boom.

FAQ

How many cars did Tesla deliver in Q3 2026?

Tesla delivered 486,532 vehicles in the third quarter of 2026: 478,237 Model 3 and Model Y and 8,295 other models. It produced 464,391.

Did Tesla beat delivery expectations?

Yes. The company-compiled consensus of 24 analysts was 461,974, so Tesla beat by 24,558 units, or 5.3%. It also beat the top of the estimate range, 482,000.

Are Tesla deliveries up or down year on year?

Down 2.1%, from the record 497,099 in Q3 2025. That quarter was boosted by buyers rushing to claim the US $7,500 EV credit before it expired on 30 September 2025. Deliveries rose 1.3% from Q2 2026.

Why did Tesla stock go up today?

Deliveries beat every published estimate after a quarter in which the shares had fallen to $354.11, down about 21% for the year. The stock traded at $371.02, up 4.8%, at 11:24 ET on 2 October.

How much energy storage did Tesla deploy in Q3?

13.7 GWh, below the 15.9 GWh consensus but up from 12.5 GWh a year earlier and 13.5 GWh in Q2.

What are analysts’ price targets for Tesla?

The recent range runs from BNP Paribas Exane’s $268 (Underperform, 24 September) to RBC Capital’s $480 (Buy, 25 September), against a share price of about $371.

Sources: Tesla Q3 2026 production and deliveries release and company-compiled consensus, as reported by Electrek and CNBC (2 October 2026); Tesla Q2 2026 update; Nasdaq and Yahoo Finance price data; RBC Capital and BNP Paribas Exane notes as reported. This article is for information only and is not financial advice. Do your own research before making any investment decision.

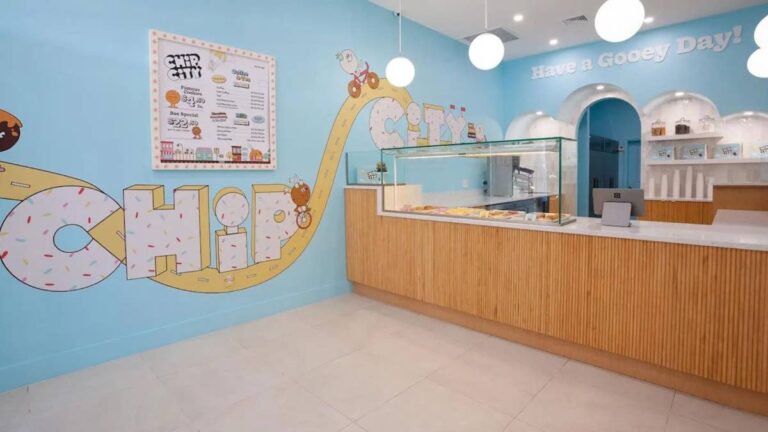
Launched by childhood friends Teddy Gailas and Peter Phillips out of the Queens borough of New York in 2017, Chip City Cookies was one of the early breakaway stars of the “cookie wars” that swept the country as a food craze 10 years ago.

The chain made a name for itself through its large, gooey cookies with original rotating flavors dropped on social media prior to being available in stores. It expanded quickly to a peak of nearly 50 locations across states including New York, New Jersey, Connecticut, Massachusetts, Texas, Virginia, Florida, and Illinois.

But amid the shifting wave of food trends and an economy in which many are watching their spending on artisanal versions of common treats more carefully, the cookie craze appears at a major ebb.

Chip City Cookies abruptly closes all remaining stores

Crumbl, which is another breakaway star and major name in this space, slashed the number of its physical stores by 16% from 2024 to 2025. The 20-year-old New York State cookie bakery The Cookie Factory closed its last remaining brick-and-mortar stores to focus on selling exclusively at supermarkets in August 2026.

While observant fans noticed that Chip City Cookies had closed some stores in states like Connecticut earlier in September, chain president Nicolas Baizan just took to social media to say that it is permanently shuttering its last 22 remaining locations at the end of business hours on Oct. 2.

Read Now: Viral cookie chain leaves key market, closes all stores

“Despite extensive efforts to stabilize our business in the face of significant macro-economic headwinds, we have made the very difficult decision to close all of our Chip City locations,” Chip City Cookies said in its statement. “We are grateful to our dedicated employees and loyal customers who have supported us for the past 10 years.”

Chip City opened during the “cookie wars” phase in 2017 by Teddy Gailas and Peter Phillips.

Chip City

‘Consumers are spending less and their preferences are evolving:’ Chip City Cookies on abrupt closures

Bazin went on to name “a challenging environment” and “consumers [who…] are spending less” as the main factor that “negatively impacted our sales.”

The abrupt collapse of what was once a breakout star in the food world backed by New York restaurateur and Shake Shack founder Danny Meyer sent shockwaves through the industry as well as fans (part of the chain’s success came from its cult following of diehard fans).

Locals near the location on Columbus Avenue in Manhattan’s Upper West Side also reported seeing police officers from the NYPD Evidence Collection Team going inside the shop on the morning of Oct. 2.

More Retail And Travel News:

While Chip City previously told customers in stores that were announced as closing earlier in the month that any pre-purchased gift cards could be used at other locations throughout October, the abrupt shutdown makes it highly unlikely that these will have any use.

The collapse also comes just several days after founder Peter Phillips sued the company. According to the lawsuit, Phillips was to remain with the company until December after Meyer’s Enlightened Hospitality Investments took a majority stake in the brand in March 2026.

Phillips’ suit goes on to claim that the new majority owners pressured him to surrender web domains and sign third-party borrower authorization documents on five small-business loans in order for this agreement to be honored.

Related: Popular chicken chain exits market, closes more locations

US stocks recovered from early losses and closed slighly higher on Thursday as Treasury yields pulled back from multi-decade highs, helping the major indexes close slightly higher.

The S&P 500 gained 0.23% to 7,668.82, while the Nasdaq Composite rose 0.07% to 26,871.60. The Dow Jones Industrial Average added 29.84 points, or 0.06%, to finish at 50,935.89.

The recovery came after the benchmark 10-year Treasury yield briefly climbed to 5.342%, its highest level since April 2002.

The 30-year Treasury yield also reached its highest level in 24 years.

Yields later reversed course as buyers returned to the bond market.

The 10-year and 30-year yields were lower by 6 and 4 basis points, respectively, while the two-year yield fell nearly 10 basis points.

The decline in shorter-dated yields reflected changing expectations around Federal Reserve policy.

The two-year Treasury yield, which is particularly sensitive to expectations for the federal funds rate, was on track for its largest daily decline since August 2025.

Economic data keeps inflation concerns in focus

Stocks had initially come under pressure as economic data pointed to a resilient labour market and continued price pressures.

Weekly initial jobless claims fell to 197,000, below the 200,000 forecast from economists surveyed by Reuters.

The data came ahead of the government’s monthly payrolls report due on Friday.

Meanwhile, the Institute for Supply Management’s manufacturing PMI edged down to 54.5 in September from 54.6 in August.

The report also showed an increase in input prices, adding to concerns about persistent inflation.

However, expectations for an October Fed rate hike weakened further.

Softer-than-expected US inflation data released on Wednesday had already reduced market expectations for another increase.

Markets were pricing a 28.2% probability of at least a 25-basis-point rate hike at the October meeting, down from 68.6% a week earlier, according to CME FedWatch data.

Fed Vice Chair Philip Jefferson indicated that the central bank could be patient before raising rates again after its 25-basis-point increase in September.

Minneapolis Fed President Neel Kashkari, however, said additional rate increases could be needed to restrain the economy into 2027, while remaining uncertain about whether the next move should come this month.

Oil gains as energy stocks outperform

Higher oil prices remained another factor for investors as markets assessed inflation risks and developments in the Middle East.

Brent crude settled more than $4 higher after China suspended fuel exports, raising concerns about tighter global fuel supplies.

WTI crude gained 1.6% to trade above $91 a barrel as investors awaited the next steps from the Trump administration in the Iran conflict.

The rise in crude prices helped the S&P 500 energy sector gain almost 2%, making it the strongest-performing sector among the 11 major S&P sectors.

Technology stocks also showed strength, with the sector gaining nearly 1%. Software shares advanced following Accenture’s results and outlook.

Micron Technology also remained in focus after reporting strong results and a better-than-expected revenue forecast.

The company also announced $32 billion in customer commitments under supply agreements, supporting continued investor interest in the AI trade.

The post Dow edges higher as US stocks recover after Treasury yields hit 24-year high appeared first on Invezz

Traditional financial strategies have long relied on prices, filings, market data, and customer records. As more financial activity moves onto blockchains, another source of information is becoming useful. 

On-chain analytics can show how assets move between wallets, where funds are concentrated, and how participants interact with blockchain networks. This data can add context that may not appear in traditional systems. 

It can support risk reviews, compliance work, market research, and monitoring of tokenized assets. This article explains five ways institutions can use on-chain analytics and what readers stand to gain from applying these insights effectively.

Key Takeaways

  • On-chain data can add transaction-level visibility to traditional financial analysis.
  • Wallet and asset flows can provide useful signals for digital-asset risk assessment.
  • Blockchain activity can strengthen existing transaction monitoring and compliance processes.
  • On-chain behavior can complement price, volume, and other market indicators.
  • Address attribution should be verified before it informs important decisions.
  • Cross-chain coverage matters when assets and funds move between networks.

What Is On-Chain Analytics in TradFi?

This concept is the process of examining data recorded on a blockchain to identify useful patterns and relationships. 

On-chain analytics can include transaction flows, wallet activity, asset balances, and interactions with blockchain-based services. For TradFi institutions, the information can complement existing financial and customer data rather than replace it.

Blockchain records can provide a visible trail of transactions and asset movements on supported public networks. 

Traditional financial data often comes through banks, brokers, exchanges, filings, and other intermediaries. Combining both sources can give institutions a broader view of activity.

On-chain analytics can help identify fund movements, wallet relationships, asset concentrations, transaction patterns, and exposure to known entities or risks. The usefulness depends on data quality and the ability to correctly link blockchain addresses to relevant entities.

Banks, asset managers, custodians, and other financial firms are increasingly dealing with digital assets and tokenized products. As this activity grows, institutions need ways to monitor transactions and exposure across blockchain networks while connecting those findings to existing financial controls.

Why On-Chain Analytics Matters for TradFi Strategies

Here is why it is important:

1. Faster Access to Market Activity

Blockchain transactions are recorded as activity occurs, giving analysts access to current information on supported networks. This can help teams monitor changes in flows, balances, and participation without waiting for periodic reports or statements.

2. Greater Visibility Into Digital-Asset Exposure

Institutions can use transaction and wallet data to understand where digital assets are held and how they move across networks and services. This can add detail to exposure assessments, especially when the activity involves multiple wallets or counterparties.

3. Stronger Risk and Compliance Monitoring

Blockchain intelligence can extend existing controls into digital-asset activity. Teams can investigate transaction patterns, screen relevant addresses, and trace funds when needed. These signals can then feed into established case management and compliance processes. 

4. Better Understanding of On-Chain Markets

Blockchain activity can provide additional context for market research. Changes in token flows, holder behavior, or activity around specific assets may reveal developments that are not obvious from price data alone. These signals should be assessed alongside traditional market indicators.

5 Ways On-Chain Analytics Can Improve Your TradFi Strategy

Here is how it can enhance your strategy:

1. Improve Digital-Asset Risk Monitoring

Track wallet balances, asset movements, concentration, and exposure across relevant networks. Changes in these areas can give risk teams additional signals when reviewing digital-asset positions or counterparties. 

This information can complement existing exposure reports and help teams investigate significant changes more quickly.

2. Strengthen AML and Transaction Monitoring

Blockchain records allow teams to trace transaction flows and investigate links between addresses, services, and known entities. 

This can strengthen existing financial crime controls by adding blockchain evidence to customer and transaction reviews. It works best when combined with established AML processes rather than used alone.

3. Track Market and Investor Behavior

Monitor movements in token balances, transaction activity, and participation across relevant networks. These signals can help analysts understand how market participants are using an asset or ecosystem. 

When combined with price, volume, liquidity, and other financial data, they can provide another layer of market research.

4. Improve Due Diligence and Counterparty Analysis

Examine how a wallet interacts with exchanges, protocols, issuers, bridges, and other addresses before making a risk assessment. This can add transaction-level evidence to conventional due diligence. 

However, address attribution is not always certain, so findings should be verified against reliable off-chain information.

5. Monitor Tokenized Assets and On-Chain Financial Activity

As securities, funds, and other financial assets are represented on blockchains, transaction records can provide visibility into transfers, holders, and activity around those instruments. 

Analytics can support monitoring alongside the legal, operational, and compliance controls already required for the underlying financial products.

What TradFi Institutions Should Check Before Using On-Chain Analytics

Before adoption, institutions should check whether the analytics system fits their data, workflow, and control requirements.

1. Data Coverage and Quality

Confirm that the provider covers relevant networks, assets, transaction types, and historical data with reliable and consistent information.

 2. Entity Attribution Methods

Check how wallet addresses are linked to known entities and how uncertain or incorrect matches are identified and handled.

3. Cross-Chain Visibility

Ensure the system can track relevant activity across multiple blockchains, especially when assets move between different networks.

4. Integration With Existing Systems

Check whether analytics can connect with existing risk, compliance, investigation, and reporting systems without creating unnecessary manual work.

5. Data Governance and Auditability

Review how data is sourced, updated, stored, and documented so teams can explain important decisions when required.

Conclusion: Making On-Chain Data Useful

TradFi institutions should start with a clear business need rather than collecting blockchain data without a purpose. Identify the decisions that could benefit from on-chain signals, then select data sources that provide the required network and asset coverage. 

Combine those findings with trusted off-chain information before acting on them. Institutions should also test alert quality and attribution accuracy, then connect useful signals to existing risk and compliance workflows. 

As digital-asset activity expands, review the data coverage and monitoring rules regularly to keep the strategy relevant and effective.
Contrary to the popular belief that physical bookstores and print books are dying, the latest industry data paints a different picture.

In 2025, print formats accounted for 50.6% of publishers’ revenue, versus 14% that came from digital formats, according to the Association of American Publishers. At the same time, physical retail revenue increased 7.2% to $6.7 billion. 

In 2025, far more Americans had read a print book (64%) than an e-book (31%), although readership of printed copies has declined over the last decade, while e-book readership has grown, the Pew Research Center noted.  

But on college campuses, the picture looks different. The latest data shows that digital is now the preferred course-material format, ahead of print. 

Some 37% of college students prefer digital course materials, compared with 32% who prefer print, making digital the preferred format for the third consecutive year, a 2026 National Association of College Stores (NACS) survey of 11,177 college students revealed. 

To adapt to these shifts, a major name in the U.S. higher-education space had to make a difficult decision and close 68 physical stores in a single quarter. 

Barnes & Noble Education shutters 68 locations 

Barnes & Noble Education, which operates more than 1,050 physical and virtual campus bookstores, recently reported fiscal 2027 first-quarter financial results, revealing revenue of $290.6 million, up $2.4 million year over year. 

“The increase in revenue was primarily driven by growth in BNC First Day programs, partially offset by the impact of store closures, including exits from certain less profitable locations,” the company stated in a press release. 

First Day Complete is the company’s institution-wide program that gives students required course materials, both physical and digital, at a discounted price, with the cost billed through the college as a course fee or included in tuition.

The college bookstore giant also reported closing 88 stores during the 13 weeks ended Aug. 1, 2026, while opening 34. Of those 88 closures, 68 were physical locations, while 20 were virtual, according to the company’s official Form 10-Q filing with the Securities and Exchange Commission (SEC). 

Based on the document, 40 of those closures were tied to two multi-campus contracts. 

While the bookstore giant didn’t disclose which contracts, one potentially relevant development is Kentucky Community and Technical College System’s decision to move its campuses to BibliU beginning in 2026.

Barnes & Noble Education Q1 closures key highlights: 

  • Net reduction: 54 stores (45 physical, 9 virtual)
  • Total footprint fell from 1,116 to 1,062
  • Physical footprint fell from 647 to 602

Gross comparable store sales, a metric that excludes closed stores, rose $10.7 million, or 3.7%, year over year.

Barnes & Noble Education closed 68 locations in a single quarter.

Boston Globe / Getty Images

Barnes & Noble Education store closures are part of a shifting strategy 

“Store closures are the result of both lost accounts due to competitive dynamics and proactive decisions to close underperforming stores, including one of the multi-campus contracts,” Barnes & Noble Education stated in its Form 10-Q filing.

The latest data suggests college bookstores are changing as students increasingly access course materials online, in digital formats, and through institutional programs.

BNC First Day revenue increased 9% to $124.7 million, as noted in the filing, suggesting that while the company is shrinking its store footprint, it is also growing its affordable-access business.

According to its quarterly report, the company continues to generate strong momentum in First Day Complete.

In fall 2026, First Day Complete will be offered across 263 campuses, covering more than 1.43 million eligible students, about 26% more than in fall 2025. Because of the program’s seasonality, its financial impact will be reflected mainly in the second and subsequent quarters, the company said.

What Barnes & Noble Education store closures mean for students 

Students increasingly shop online: 62% of those who buy course materials buy at least some from their campus store, and more reported buying from it online than in person, NACS found. 

Students’ top reasons for preferring digital include not having to “carry a physical book around,” access on multiple devices, the ability to copy, paste, or print, easier navigation and reading, and immediate access after purchase.

Affordability is another reason access programs matter.

Related: 101-year-old grocery chain closes 27 stores  

College students spent an average of $338 on required course materials during the 2025-26 academic year, according to NACS, roughly half the $701 average recorded in 2007-08. NACS also found that 54% of students were satisfied with course-material access programs that provide materials at below-retail prices.

That helps explain the appeal of First Day Complete, which also shifts the bookstore’s role toward institution-wide distribution.

Programs like this, and growing demand for digital materials, mean fewer stores don’t automatically translate into a smaller student reach, though lost accounts do shrink it.

How Barnes & Noble Education became a college bookstore giant

Barnes & Noble Education traces its roots to 1965, when Leonard Riggio opened the Student Book Exchange in New York City’s Greenwich Village. In 1968, he opened the first on-campus, contract-managed bookstore at Queensborough Community College, according to Barnes & Noble Education.

In 1971, Riggio acquired the Barnes & Noble trade name. The company went on to expand its college bookstore business across the U.S., building a large network of campus stores over the following decades. 

The college business became a separate company in 2015, when Barnes & Noble completed the spin-off of Barnes & Noble Education. At the time, the company operated 724 campus stores serving colleges and universities and more than 5 million students and faculty, according to its SEC filing.

Today, the company operates a very different business, with physical bookstores representing only part of its model as it expands digital course materials and programs such as First Day Complete.

Related: Low-key luxury retailer closes 16 stores

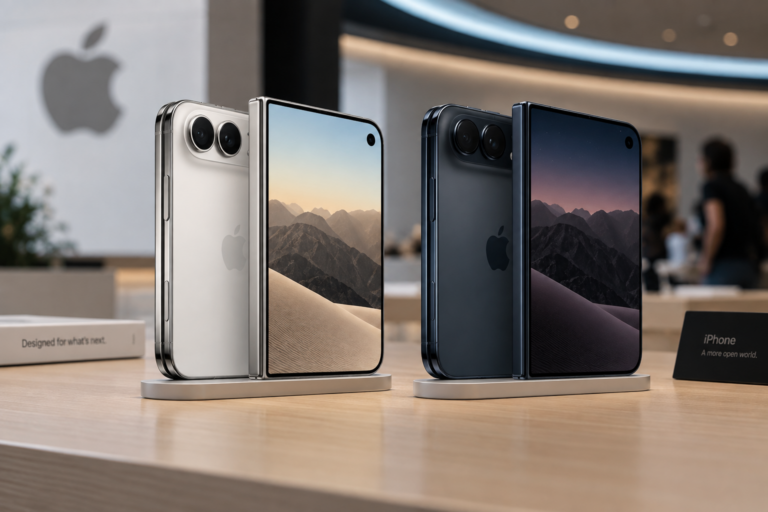
Apple stock AAPL gained 2% on Wednesday after Counterpoint Research estimated that the company could sell 6 million units of its upcoming iPhone Duo this year, while UBS said wait times for the iPhone 18 Pro and Pro Max remain relatively unchanged.

The iPhone Duo will be Apple’s first foldable smartphone, with pre-orders scheduled to begin on Oct. 16 ahead of its Oct. 23 release.

However, UBS said its data showed limited changes in iPhone availability across more than 30 geographies, potentially indicating that demand for the existing Pro models has not accelerated significantly.

Counterpoint estimates 6M iPhone Duo sales

Counterpoint Research said procurement for panels used in the iPhone 18 Pro, Pro Max and Duo is modestly higher than procurement for the iPhone 17 lineup.

Panel procurement for the Pro and Pro Max models is up 2% year over year, with the remaining increase attributed to the iPhone Duo.

The foldable smartphone starts at $1,999 for the 256GB version and goes up to 2TB.

Counterpoint expects Apple to sell about 6 million Duo units this year.

The device has a design similar in size to a passport and features two rounded corners.

Apple describes it as its thinnest iPhone, with an aerospace titanium frame and a 7.6-inch Super Retina XDR display.

The display is 50% larger than that of the iPhone 18 Pro Max and 80% larger than the iPhone Pro.

UBS says iPhone wait times remain ‘flattish’

While the Duo sales estimate provided a potential catalyst for Apple shares, UBS said wait times for the iPhone 18 Pro and Pro Max have remained relatively stable.

“UBS Evidence Lab data that tracks iPhone availability across 30+ geographies suggests that wait times were relatively unchanged on a [week-over-week] basis,” UBS analyst David Vogt wrote in a note to clients.

“The Pro in the US was the only notable delta, declining by ~2 days [week-over-week],” Vogt added.

According to Vogt, average wait times are also broadly in line with last year’s levels.

The Pro in the US is down two days year over year, while the Pro in China is up two days. The Pro Max in China is down four days.

Vogt said the relatively unchanged wait-time gap for the Pro Max in China could indicate that some consumers are waiting for the Duo next month.

He expects existing Pro Max users seeking upgraded specifications, particularly in China, could make up the initial market for the new form factor.

Vogt has a Neutral rating on Apple and a $296 price target.

Apple prepares new smart-home products

Separately, Apple is reportedly preparing to expand further into the smart-home market with a new home hub expected to launch on Oct. 13.

According to Bloomberg News, the device is expected to feature a roughly 6-inch square display that can be placed on a countertop or mounted on a wall.

It will be designed to control connected home products, make video calls, play music, and display photos.

The hub is also expected to recognize household members through voice or facial recognition and display personalized information, including calendars, messages and contacts.

A visitor mode will hide personal information.

Bloomberg also reported that Apple plans to introduce an updated HomePod mini and a new Apple TV set-top box, with both expected to retain their current designs while receiving faster processors to support Apple’s artificial intelligence features.

The products are expected to showcase Apple’s revamped Siri assistant, which uses large language models and is designed to handle more complex requests and control apps and smart-home devices.

Apple has been seeking to expand in the smart-home market, where Amazon and Google have established larger presences.

The company is also working on a home-security camera and other smart-home products, according to Bloomberg.

The post Apple stock is rising today: here's why appeared first on Invezz