Author

admin

Browsing

While the approximately 8,000 registered travel agencies operating in the U.S. in 2026 can seem like a big number, it is significantly lower than the peak 35,000 businesses that sold trips and tours during the 1990s.

If the rise of online booking platforms has been gradually whittling away the need for centralized agencies outside of certain niche or ultra-luxury segments, the spike in jet fuel prices and an uncertain economic outlook in 2026 have served to hasten the momentum more recently.

Some recent travel companies that ended up shutting down operations in 2026 for good include Trav Expert, Groupia, Golf Villa Rentals, Salamander Voyages, Travel Bespoke, Regen Central, Set Sail Cruises, Yourtravelshop.com, Ski Yodel, Wayfairer Travel, and TS Travels Group among others.

Sunshine Tours shuts down after 45 years

A longtime Virginia travel industry name and community staple that was founded in 1982 by husband-and-wife team Carroll and Joyce Stone, Sunshine Tours is the latest to announce their exit from the market.

The company named the “rising cost of fuel, lodging, and overall tour expenses, along with the decline in passenger counts” as the reason to shut down a business selling travelers bus tours across the United States and Canada.

Related: What to do for the most luxurious travel experience in Dublin

“After much consideration, we have made the difficult decision to close our business effective immediately,” Sunshine Tours wrote in a post that it put out on multiple social media channels. “There were several factors that led to this outcome, but the biggest contributing issues were the rising cost of fuel, lodging, and overall tour expenses, along with the decline in passenger counts. We understand as a ‘luxury’ and non-essential business, travel is often one of the first expenses people cut back on when budgets tighten. Please know we are devastated by this decision.”

This means that any tours scheduled for the coming weeks and months will be canceled while anyone who put down a deposit or paid for the cost of the trip is urged to contact the company at 540-674-9517 or sunshinetours1982@gmail.com.

Sunshine Tours sold bus tours to different parts of the U.S. and Canada.

Shutterstock

“Refunds for all tours will be processed based on the decisions of legal counsel”: Sunshine Tours

While Sunshine Tours has not officially filed for bankruptcy, its statement that “refunds for all tours will be processed based on the decisions of legal counsel” suggests that its financial position may not be one in which it is able to provide them.

The other option is for affected travelers to go through their credit card issuer or travel insurance.

More Travel News:

“We also understand that you have paid your deposits or balances for an upcoming tour and that you are owed a refund,” Sunshine Tours wrote further. “At this time, we are working with legal counsel to determine the best course of action for everyone affected. Refunds for all tours will be processed based on the decisions of legal counsel during this process. Please note this will not be an overnight process, and we do not yet have a timeline for when refunds will be issued.”

These travel agencies filed for bankruptcy in 2026:

  • AVG Travels: The Melbourne-based travel agency selling cheap vacation packages to travelers in Australia and New Zealand sent more than 200 customers an email saying that the trips were canceled before entering bankruptcy in May 2026.
  • GoPlay Sports: In April 2026, the men’s basketball team of the University of Dallas was left without a planned trip to compete in the United Kingdom after Boston-based GoPlay Sports Tours LLC accepted two payments of $30,000 and then went unreachable.
  • Havantur: Havantur was forced to shut down its main European office in France at the beginning of 2026 after tourist numbers to the Caribbean country plummeted due to U.S. military actions in Venezuela and threats against the country.
  • Vegas Vacations and North America Destinations: Two travel agencies in the Canadian province of British Columbia, Vegas Vacations and North America Destinations, were shut down by regulators within a few days of each other in January 2026 after multiple travelers complained of buying trips and receiving invalid plane tickets and hotel bookings.

Related: Popular luxury travel company abruptly cancels all trips

SanDisk stock SNDK has gained 500% this year so far. While the memory market has been notoriously cyclical, SanDisk is attempting to reduce its exposure to the traditionally cyclical NAND memory market through a new long-term agreement business model.

Under these agreements, the company commits to delivering specified volumes of products over multiple years, while customers commit to purchasing those volumes.

Pricing can include fixed and variable components, with financial guarantees providing additional protection if customers fail to meet contractual obligations.

According to the company’s fiscal 2026 10-K, SanDisk expects these new business models, or NBMs, to become its predominant way of doing business.

The company said the structure should improve revenue predictability, production planning and supply assurance, although it does not eliminate risks related to demand, market conditions or execution.

SanDisk has signed multi-year agreements with eight data-center customers, including three US hyperscalers.

The agreements have a minimum total contract value of $93.9 billion.

They are expected to cover 50% of the company’s bit shipments in fiscal 2027 and 67% in fiscal 2028.

The company’s CFO Luis Visoso said the agreements include pricing floors and ceilings, with floor pricing supporting gross margins of around 80%.

The contracts therefore provide SanDisk with greater visibility into both future volumes and profitability.

Kioxia joint venture supports capital efficiency

SanDisk also benefits from its long-standing manufacturing partnership with Kioxia Holdings.

The companies have extended their joint venture framework at Kioxia’s Yokkaichi plant in Japan through December 2034.

The partnership, which has operated for more than 25 years, allows the companies to jointly develop technologies and manufacture flash-based memory wafers.

Their combined manufacturing footprint accounts for 33% of global wafer production.

The company has attributed its capital efficiency to research and development innovation and the reuse of manufacturing tools.

This structure could help SanDisk manage the capital requirements associated with expanding memory production while sharing manufacturing resources with Kioxia.

High-bandwidth flash adds potential AI upside

SanDisk is also pursuing opportunities tied to artificial intelligence through high-bandwidth flash, or HBF.

The company and SK hynix jointly established the HBF standard to address memory-capacity constraints associated with high-bandwidth memory.

According to SanDisk’s investor presentation, HBF can provide eight to 16 times higher memory capacity at a given bandwidth. The technology is particularly aimed at high-context AI inference workloads.

SanDisk has completed the design of its first HBF chip and remains on track for a launch in 2027, followed by mass production in 2028.

The technology has received support from major cloud and AI companies, including Alphabet, Meta Platforms and Tenstorrent. Nvidia adoption remains pending.

Importantly, the potential contribution from HBF is not included in SanDisk’s current fiscal 2028 to fiscal 2030 projections, which target a mid-to-high-teens revenue compound annual growth rate.

From a valuation perspective, SanDisk trades at a higher forward EV/EBITDA multiple than its memory semiconductor peers.

The company’s one-year forward multiple is cited at 6.3 times, compared with a peer average of 4.1 times.

Lynx Research has also issued bullish price targets, setting a $2,450 target for SanDisk and $1,325 for Micron.

The firm argued that the extreme volatility seen in May and June had eased, with institutional buying becoming more deliberate.

Overall, SanDisk’s long-term contracts, manufacturing partnership with Kioxia and potential HBF opportunity provide several factors investors are watching as the company seeks to balance memory-market cyclicality with rising AI-related demand.

The post Why investors see more upside for SanDisk's 500% rally appeared first on Invezz

Lululemon beat its own earnings guidance by more than 60% and the stock fell 17.4% in a single session. That is not a typo, and it is the cleanest illustration this year of how little a headline EPS number means on its own. lululemon athletica inc. (NASDAQ: LULU) closed at $100.61 on Friday 4 September 2026, down from $121.77, after touching $97.99 intraday – the first time the shares had printed below $100 since May 2018. The stock is down 51.6% in 2026 and 80.3% from its December 2023 closing peak of $511.29. A brand that people still queue for has become, in the phrase circulating on Reddit this weekend, a perfect example of how “a great brand can be a terrible stock.”

Here is the part almost none of the coverage led with. Diluted EPS came in at $2.92 against company guidance of $1.76 to $1.81 – but $0.86 of that was a one-off refund of tariffs. lululemon received $134.5 million of International Emergency Economic Powers Act refunds in the quarter, plus $4.1 million of interest, after US courts struck the IEEPA tariffs down. Strip it out and EPS was roughly $2.06 against $3.10 a year earlier, a 33% decline. The same refund flattered gross margin by 560 basis points and operating margin by 560 basis points. Reported gross margin rose 200bp to 60.5%; underlying, it fell around 360bp. Reported operating margin fell 190bp to 18.8%; underlying, it fell about 750bp. The “beat” was a cheque from the US government, and the company’s outlook explicitly assumes it does not repeat.

Key facts

  • -17.4% in one day – LULU closed at $100.61 on 4 September 2026, down from $121.77, on 37.1 million shares
  • $97.99 – intraday low, the first sub-$100 print since May 2018 (last close below $100: $98.95 on 15 May 2018)
  • $134.5m – IEEPA tariff refunds recognised in Q2, worth $0.86 per share, or 29% of reported EPS (lululemon 8-K, 3 Sep 2026)
  • -9% comparable sales, with Americas comps -12% and international comps -3%
  • $12.20 to $8.74 – FY2026 EPS guidance midpoint from March to September, adjusting the latest figure for the one-off refund: a 28% cut in under six months
  • $688.3m – spent on share buybacks in the first half of fiscal 2026, while the stock halved
  • 8 September – the day incoming CEO Heidi O’Neill starts, four business days after the crash
LULU daily closes to 4 September 2026, and the FY2026 EPS guidance midpoint at each of the company’s three 2026 outlook updates. Source: FinanceFeeds, from closing prices and lululemon’s SEC filings.

What actually happened in the quarter

For the second quarter of fiscal 2026, which ended 2 August, net revenue fell 4% to $2.4 billion, or 5% on a constant dollar basis. The split is where it gets uncomfortable. Americas net revenue fell 8%; international net revenue rose 4%. Comparable sales – the measure that strips out new store openings and is therefore the honest read on whether existing shops are busier – fell 9% overall, and 12% in the Americas. International comps fell 3%.

Income from operations fell 13% to $453.7 million. Net income fell to $329.2 million from $370.9 million. Across the first half, net income is down 23.5%, from $685.5 million to $524.3 million. The company ended the quarter with $1.4 billion of cash, inventories down 1% in dollars and 7% in units, and 825 stores after opening nine net new ones.

None of that, on its own, explains a 17% single-day fall. Retail stocks routinely absorb a soft quarter. What they do not absorb is the guidance.

The number that did the damage

Track lululemon’s own fiscal 2026 outlook across three filings and the story writes itself.

Outlook set on FY2026 revenue FY2026 diluted EPS
17 March 2026 $11.350bn – $11.500bn (+2% to +4%) $12.10 – $12.30
4 June 2026 $11.000bn – $11.150bn (-1% to 0%) $10.95 – $11.15
3 September 2026 $10.350bn – $10.500bn (-5% to -7%) $9.48 – $9.73

In under six months the revenue outlook has been cut by roughly $1.0 billion at the midpoint and moved from growth of 2-4% to a decline of 5-7%. The EPS midpoint has gone from $12.20 to $9.61 – and the September figure includes the $0.86 of one-off tariff money. Remove it and the underlying guidance is about $8.74, which is 28% below where the year started.

The third-quarter guide is starker still: revenue of $2.290bn to $2.320bn, a decline of 10% to 11%, with EPS of $0.93 to $0.98. That is the first double-digit revenue decline lululemon has guided to, and it is the number the market actually traded on. A soft quarter is a data point. A guide that says the next quarter will be materially worse than the one that just disappointed is a trend.

The Americas problem is ten quarters old, and accelerating

This is the part that turns a bad quarter into a structural argument, and the person who has been making it loudest is the man who founded the company.

In a statement filed with the SEC on 18 March 2026, founder Chip Wilson wrote that “Fourth quarter 2025 Americas comparable sales represent the eighth consecutive quarter of decreased or flat results, and the outlook for fiscal year 2026 indicates no meaningful change in trajectory.” Two quarters have been reported since. Q1 2026 Americas comparable sales fell 5%. Q2 2026 Americas comparable sales fell 12%. By the founder’s own count, that streak now stands at ten consecutive quarters – and the sequence over the last three is -1%, -5%, -12%. The decline is not flattening. It is steepening.

International is genuinely working: comps there fell only 3% and revenue grew 4% despite a tougher year. But international cannot yet carry the company. The Americas remains the majority of the business, and it is shrinking at an accelerating rate while the company opens stores into it.

A leadership vacuum, filled four days too late

The crash landed in the middle of an unusually thin management structure. lululemon has been run since earlier this year by two interim co-CEOs: Meghan Frank, who is also the chief financial officer, and André Maestrini, who is also president and chief commercial officer. It was Frank who delivered the results, saying the company is “taking a prudent approach with our revised full-year outlook” and that teams remain focused on “strengthening our product offerings, increasing our marketing investments, and maintaining disciplined expense management.”

Maestrini’s line in the same release now reads like unfortunate timing: “We look forward to welcoming our incoming CEO, Heidi O’Neill, next week as we begin an exciting new chapter for the company.” O’Neill, a near-30-year Nike veteran, was named in April and starts on 8 September – four business days after the stock hit an eight-year low. She inherits a guidance cut she did not write.

The C-suite has been thinning elsewhere too. On 13 August 2026 the company disclosed in an 8-K that Ranju Das had “ceased to serve as Chief AI & Technology Officer,” with transition plans in place for his responsibilities.

And Wilson is not a passive observer. He and affiliated entities beneficially own 9,570,851 shares, or 8.6% of the company, and he is running an active proxy campaign – a GOLD universal proxy card, a dedicated campaign website, and three nominees – to force board change. His March statement called the company “in dire need of significant and substantial refreshment of the board of directors” and said he was “prepared to continue the effort for as long as necessary to effectuate the quantum of change required to return lululemon to its premium position.” Notably, his group’s stake has drifted down from 9,904,856 shares in March to 9,570,851 in the 3 September filing, even as the percentage ticked up – because the company’s own buybacks have been shrinking the share count faster than he has been selling.

Why a great brand became a terrible stock

The framing doing the rounds since Friday – one r/NemoMoney post put it as “wild one for anyone who’s ever paid $120 for leggings” – is the right one, and it is worth taking seriously rather than treating as a meme. Brand affection and equity returns are different things, and lululemon has become the textbook case of the gap.

The mechanism is straightforward. A premium apparel business is valued on the assumption that it can hold price and keep growing units. When comparable sales fall 12% in your core market for a tenth straight quarter, the market stops paying for growth and starts paying for cash flow – and it re-rates hard, because the multiple was doing most of the work. lululemon’s stock has fallen 80% from its peak while the business is still highly profitable and generating an 18.8% operating margin. Those two facts are not contradictory; they are what a multiple collapse looks like.

The capital allocation makes the arithmetic worse rather than better. lululemon repurchased 2.2 million shares for $358.3 million in Q1 and 2.7 million shares for $330.0 million in Q2 – $688.3 million in six months, at prices between roughly $120 and $180, into a stock that has since traded at $97.99. Buybacks into a falling multiple destroy value in exactly the way they create it into a rising one, and the company has been doing a lot of it.

There is also a macro layer that has nothing to do with leggings. The tariff refund that flattered the quarter exists because US courts struck down the IEEPA tariff regime – a ruling that moved markets well beyond retail, as we covered when the Supreme Court struck down the tariffs and when the ruling drove a gold rally and dollar caution. For lululemon it produced a $134.5 million windfall that arrives once and then never again, at precisely the moment underlying margins were deteriorating. The refund did not cause the sell-off. It disguised how bad the quarter was, right up until anyone read the footnote.

The consumer backdrop is not helping either. US August payrolls came in strong enough to raise Fed hike odds, which is good news for the economy and bad news for discretionary spending at $120 a pair. And competition at the value end has never been fiercer, with Shein pushing toward a Hong Kong listing. Meanwhile the company that supplied lululemon’s next chief executive is fighting its own repositioning battle, as our piece on Nike’s index and strategy shifts sets out.

Frequently asked questions

Why did Lululemon stock drop 17% on 4 September 2026?

Because of the outlook, not the quarter. lululemon cut its fiscal 2026 revenue guidance to $10.350bn-$10.500bn (a decline of 5% to 7%, from a March guide of 2-4% growth) and guided third-quarter revenue down 10% to 11%. The reported EPS “beat” of $2.92 included $0.86 per share of one-off tariff refunds, so underlying earnings actually fell about 33% year on year.

What were the IEEPA tariff refunds in Lululemon’s results?

lululemon received $134.5 million of International Emergency Economic Powers Act tariff refunds plus $4.1 million of associated interest in the second quarter, after US courts struck the tariffs down. The refund was booked as a reduction in cost of goods sold, adding 560 basis points to both gross and operating margin and $0.86 to diluted EPS. The company’s outlook does not assume any further refunds.

How far has Lululemon stock fallen from its high?

LULU closed at $100.61 on 4 September 2026, down 80.3% from its closing peak of $511.29 on 29 December 2023, and down 51.6% so far in 2026. The intraday low of $97.99 was the first sub-$100 print since May 2018; the last close below $100 was $98.95 on 15 May 2018.

Is Lululemon losing customers in the US?

The comparable sales data says yes, and has for some time. Americas comparable sales fell 12% in Q2 2026, 5% in Q1 2026 and 1% in Q4 2025. Founder Chip Wilson stated in a March 2026 SEC filing that Q4 2025 marked the eighth consecutive quarter of decreased or flat Americas comps; the two quarters reported since have both declined, taking the run to ten.

Who is running Lululemon right now?

Until 8 September 2026 the company is led by two interim co-CEOs: Meghan Frank, who is also CFO, and André Maestrini, who is also president and chief commercial officer. Heidi O’Neill, previously a near-30-year Nike executive, was named CEO in April 2026 and takes over on 8 September. The company also disclosed on 13 August that its Chief AI & Technology Officer had left.

What is Chip Wilson’s fight with the Lululemon board about?

Wilson, the founder, and affiliated entities hold 9,570,851 shares – 8.6% of the company – and are running a proxy campaign for board change, with three nominees and a GOLD universal proxy card. In a March 2026 statement filed with the SEC he described lululemon as “in dire need of significant and substantial refreshment of the board of directors” and said he was prepared to continue “for as long as necessary.”

Why does the stock keep falling if the brand is still popular?

Because brand affection and equity returns are different things. lululemon still earns an 18.8% operating margin, but a premium multiple is paid for growth, and Americas comparable sales have now declined for ten consecutive quarters at an accelerating rate. When growth stops, the multiple compresses – which is why an 80% share price decline can sit alongside a business that remains solidly profitable.

This article is analysis and information only. It is not investment advice and contains no price targets or forecasts.

Lululemon stock has grossly underperformed the broader markets in the last five years. While the S&P 500 index trades near record levels, LULU stock is down almost 80% from all-time highs.  

Notably, the stock tanked 17% after its fiscal Q2 2027 (ended in July) results, as a lackluster report forced several analysts to lower price targets. 

JPMorgan analyst Matthew Boss slashed his price target on the athletic apparel maker by 38% to $95 from $154, a $59 drop. However, Boss maintained his “Neutral” rating on LULU stock.

The price cut came right after Lululemon (LULU) posted second-quarter results that missed expectations. 

Revenue fell short of consensus, and international sales weakened more than what analysts expected.

Boss told investors the company’s third-quarter earnings outlook sits about 60% below Wall Street consensus, according to the Fly. That’s a steep gap, which helps explain why the firm moved so aggressively on its target.

Why Lululemon stock is down in 2026

Lululemon has built its brand on premium leggings, yoga wear, and a loyal community of shoppers. 

For years, that formula delivered strong growth in North America and even faster growth in China.

That momentum has stalled.

In the second quarter, total net revenue fell 4% to $2.4 billion, and comparable sales fell 10%. North America, still the company’s biggest market, saw comparable sales sink 12%.

Related: One of retail’s once-hottest stocks just imploded 18% overnight

China mainland, once a key growth driver, is wrestling with slowing sales. Revenue in the region rose 4% and declined 2% when adjusted for currency. Comparable sales in China dropped 8% year over year. 

Management pointed to a mix of problems, as negative online commentary hurt brand sentiment in China. A softer Tmall shopping event also added pressure. 

In North America, traffic slowed, and some new product launches simply did not connect with shoppers.

Lululemon sales are expected to fall over the next 12 months

Cheng Xin / Getty Images

JPMorgan’s Lululemon stock price target explained

Boss based his new $95 price target on a company still working through real challenges. 

A few numbers stand out from the earnings report that likely shaped his view:

  • Full-year revenue guidance now sits at $10.35 billion to $10.5 billion, down 5-7% from last year.
  • Full-year earnings per share guidance dropped to $9.48 to $9.73, well below last year’s $13.26.
  • Third-quarter revenue is expected to be between $2.29 billion and $2.32 billion, a decline of 10-11%. 
  • Third-quarter earnings per share guidance came in at just $0.93 to $0.98, compared to $2.59 a year ago
  • Operating margin for the third quarter is expected to be near 6.5%, down sharply from 17% last year

Lululemon’s profit margins are expected to decline rapidly over the next 12 months. As revenue is forecast to fall, marketing costs and store investments will remain elevated, driving the bottom line lower. 

Lululemon is spending more on brand campaigns and product development while revenue moves in the opposite direction. 

Lululemon’s plan to turn things around

To be fair, Lululemon is focused on a strategic turnaround. 

The company is chasing its better-performing styles, cutting SKUs to declutter stores, and leaning harder into marketing in the back half of the year.

More Bank Stock Resets:

Chief Financial Officer and interim co-Chief Executive Meghan Frank addressed the traffic problem during the company’s earnings call, stating:

“We’re seeing the pressure in traffic. We’re also seeing negative year over year conversion, but we’re not seeing that worsen.”

Frank added that the company is investing in marketing tied to major events like the U.S. Open and the fall marathon season in New York, Chicago, and Toronto, hoping to rebuild brand excitement.

Lululemon is also bringing in new leadership. Heidi O’Neill joins as chief executive, and management said she will take a fresh look at strategy once she settles in.

Is LULU stock undervalued right now?

A price target cut of this size sends a clear signal. JPMorgan believes Lululemon’s recovery will take longer than many hoped, and the stock’s valuation needs to reflect that reality.

Boss kept his Neutral rating rather than downgrading further, which suggests he sees the stock as fairly priced at current levels rather than a stock to avoid entirely. Still, a $59 cut to a price target is a significant move by Wall Street standards.

Related: Lululemon makes big cuts to one kind of store

Given consensus estimates compiled by TIKR, Lululemon is forecast to report a free cash flow of $699 million in fiscal 2028, down from $1.64 billion in fiscal 2024. However, free cash flow is projected to improve to $2.94 billion in fiscal 2031. 

LULU stock can almost triple from current levels within the next four years if it trades at 10x forward FCF. However, it needs to flawlessly execute its near-term plans and consistently beat Wall Street estimates. 

For everyday investors, the lesson here is simple. 

Even well-known brands with loyal customers can struggle when a product misses the mark, and international markets hit unexpected headwinds. 

Lululemon still has a strong balance sheet and a global footprint, but the next few quarters will show whether its turnaround plan can actually restore growth.

Anthropic, the giant company in the artificial intelligence (AI) space, is planning to launch the biggest IPO in the coming weeks. As this happens, more details, including banker selection and prospectus release date are coming out.

Goldman Sachs and Morgan Stanley scoop major roles

One of the closely-watched move whenever a company as large as Anthropic is going public is the selection of bankers who will lead the process. In this case, there are reports that Morgan Stanley and Goldman Sachs will be the ones to do this. Morgan Stanley will have the “lead left” role, while Goldman Sachs will be the stabilization agent, ensuring that the stock trades well after its IPO.

Other banks expected to participate in this process will be Barclays and JPMorgan. Eventually, all these companies will likely share over $500 million in fees. In the last SpaceX IPO, they shared a pool of $500 million, with Goldman Sachs and Morgan Stanley taking $100 million each. 

Anthropic prospectus may come as soon as this week

Another important aspect is the filing of the prospectus, which is normally known as the S1. This is an important document that shares all the vital details in a company. It includes details such as its business process, profits, revenues, and its free cash flow. 

The document is vital because Anthropic has been a private company and has not been obligated to release any documents. With it going public, it will now need to provide more information to help investors make solid decisions. 

The prospectus will also help it during its roadshow, a process where the management talks to investors. According to the FT, this prospectus will be filed with the SEC as early as this week.

Anthropic total addressable market (TAM)

Anthropic has made several important announcements in the past few months. For example, the management sees the total addressable market at $30 trillion, higher than SpaceX’s $28 trillion. 

The most recent disclosures also showed that its revenue continued soaring this year, with the revenue run rate hitting $65 billion at the end of July. That was a sevenfold increase from a year ago, and is higher than what OpenAI made.

Anthropic has overtaken OpenAI by focusing on its models, which are the most advanced in the industry. This growth helps it charge more money than OpenAI by focusing on corporate clients. 

The risk, however, is that its growth is coming at an enormous cost, with the company spending billions of dollars a month. It is paying SpaceX over $1.5 billion a month for computing capacity and has inked more deals recently.

The upcoming Anthropic IPO will benefit some of its biggest investors. Amazon’s stake in the company will be over $400 billion thanks to its $8 billion investment. Other companies set to benefit are Google and Nvidia.

The post More details of the mega Anthropic IPO are coming out: here’s what we know appeared first on Invezz

The consensus reading of AMD is that it is winning the accelerator war slowly and the only question is how much share it takes from Nvidia. That framing misses where the money is actually going. AMD closed at $477.57 on 4 September 2026, up 4.69%, and guided third-quarter gross margin to approximately 56% – identical to the 56% it had just delivered – on revenue guided 13% higher sequentially and into the richest product mix the company has ever shipped. Instinct accelerators and Helios racks carry AMD’s highest selling prices in its history. A mix shifting toward them should lift blended margin mechanically. The guide says it will not. Something is absorbing that margin before it reaches AMD’s income statement, and it is not Nvidia.

It is memory. In the same window that AMD’s gross margin sat pinned at 56%, Micron’s went from 37.7% to 84.6% and its guidance calls for roughly 86%. These are not two separate stories about two semiconductor companies. They are one story told from opposite ends of the same bill of materials. High-bandwidth memory is consumed per accelerator, it is supply-constrained, and its price is set by a supplier with pricing power that AMD does not currently have over its own customers. The memory makers are taxing the accelerator makers, and AMD’s flat margin guide is the receipt. That is the fact that should drive an AMD valuation, and it is almost entirely absent from the sell-side framing of the stock.

Key facts

  • AMD closed at $477.57 on 4 September 2026, up 4.69%, and 17.8% below its 52-week closing high of $580.91 – stockanalysis.com daily closes, retrieved 5 September 2026
  • Second-quarter 2026 revenue was a record $11.5bn, up 50% year on year, with GAAP gross margin of 54% and non-GAAP gross margin of 56% – AMD Q2 2026 results, 4 August 2026
  • Data Center revenue more than doubled year on year and reached 58% of total company revenue – same filing
  • Third-quarter guidance is revenue of approximately $13bn plus or minus $300m, about 41% year-on-year growth, with non-GAAP gross margin of approximately 56%, unchanged sequentially – same filing
  • GAAP net income was $2.3bn on diluted EPS of $1.38; non-GAAP EPS was $1.66 – same filing
  • On 17 August 2026 AMD closed a four-tranche senior notes offering maturing 2029, 2031, 2033 and 2036, underwritten by Barclays, BofA Securities, Citigroup, J.P. Morgan, Morgan Stanley and Wells Fargo – AMD Form 8-K, 17 August 2026
  • Research and development ran $2.53bn in the quarter, 21.9% of revenue – AMD Q2 2026 Form 10-Q, filed 5 August 2026 (FinanceFeeds calculation)

What is actually happening inside the margin line

AMD’s second quarter was, on its own terms, excellent. “We delivered an excellent quarter, with record revenue and profitability as Data Center revenue more than doubled year-over-year,” said Dr Lisa Su, AMD chair and chief executive, in the results release. “We enter the second half with strong momentum as EPYC demand accelerates, Instinct deployments scale and Helios begins to ramp.”

The composition matters more than the total. Jean Hu, AMD executive vice president, chief financial officer and treasurer, put the concentration plainly: “Revenue increased 50% year-over-year to a record $11.5 billion, driven by continued strength in our Data Center business, which represented 58% of company revenue in the quarter.”

So a majority of AMD’s revenue now comes from a segment that grew more than 100% year on year, and the blended gross margin still will not move. There are only three explanations. Either the data-centre products carry a lower gross margin than the corporate average, which would be surprising given their pricing. Or input costs are rising fast enough to offset the mix benefit. Or AMD is discounting to win placements. The memory-cost evidence points hard at the second, and we have separately documented Nvidia raising AI server prices by more than 15% specifically on memory costs, which tells you the pressure is industry-wide rather than an AMD execution failure.

The distinction matters enormously for the valuation. An execution problem is fixable by AMD. A structural transfer of margin to the memory suppliers is fixable only when memory supply loosens, which is outside AMD’s control and, on current industry capacity plans, unlikely before calendar 2027.

The balance sheet just changed character

On 17 August 2026 AMD closed a four-tranche senior notes offering maturing in 2029, 2031, 2033 and 2036, executed through a Third Supplemental Indenture and underwritten by six of the largest banks on Wall Street. The filing is signed by Jean Hu as chief financial officer.

The interesting part is that AMD did not obviously need the money. This is a company generating billions in quarterly operating cash flow with a modest debt load by megacap standards, and the stated use of proceeds is the standard general-corporate formula rather than a named acquisition or project. A company in that position raising multi-billion-dollar term debt across four maturities is doing one of two things: pre-funding a capital commitment it has not yet announced, or insuring against a capital market that might be less friendly in eighteen months.

Either reading is a change in character for a business whose entire structural advantage over Intel was being asset-light. AMD outsources fabrication to TSMC precisely so that it does not carry the capital intensity that has crushed Intel’s returns. Adding term debt narrows that distinction at the margin, and it does so at coupons set in a higher-rate world than the one in which AMD’s existing paper was issued.

The valuation, stated honestly

There is no reading of AMD that makes it cheap. Annualise the second-quarter GAAP diluted EPS of $1.38 and you get roughly $5.52; against $477.57 that is about 87 times GAAP earnings (FinanceFeeds calculation). Annualise the non-GAAP $1.66 and you get $6.64, or about 72 times. With approximately 1,632.5 million shares outstanding as of the Q2 10-Q cover date, the market capitalisation is roughly $780bn.

This is the single most important thing for a reader to internalise: the bear case for AMD is not a business failure, it is a re-rating. Even at $310, a 35% decline from spot, AMD would trade at roughly 47 times annualised non-GAAP earnings. That is still a growth multiple. The stock does not need anything to go wrong operationally to fall by a third; it only needs the market to decide that 70 times is the wrong number for a company whose gross margin will not expand.

Scenario Level What has to be true
Bull $700 Gross margin breaks above 56% as memory supply loosens or AMD reprices, Instinct wins a second hyperscaler at scale, and the market keeps paying a premium multiple for accelerating data-centre share
Base $540 Revenue compounds toward the guided $13bn quarterly run-rate and beyond, margin stays near 56%, and the multiple slowly compresses as growth is delivered rather than anticipated
Bear $310 Margin stays pinned, the AI capital-expenditure cycle shows any sign of digestion, and the multiple resets to roughly 47x – no operational failure required

The research spending nobody is comparing

Put AMD’s income statement beside Micron’s and one line separates them more sharply than revenue, margin or growth. AMD spent $2.53bn on research and development in the quarter, equal to 21.9% of revenue. Micron, in its most recent reported quarter, spent $1.32bn, equal to 3.2% of revenue (FinanceFeeds calculations from each company’s Form 10-Q).

AMD is spending nearly seven times as much of every revenue dollar on engineering as the company capturing the margin. That is not an indictment of AMD’s spending, which is what buys the roadmap that produced 50% revenue growth. It is an observation about where economic rent is accruing in this cycle, and the answer is uncomfortable for anyone holding accelerator equities: the returns are landing with the supplier that is capacity-constrained, not the designer that is innovation-constrained.

The historical parallel is the personal-computer industry of the 1990s, where the companies designing and assembling the machines competed away their margins while Intel and Microsoft, each a bottleneck, took the profit pool. Bottlenecks earn the rent. In 2026 the bottleneck is not logic design, where AMD, Nvidia and a growing roster of in-house hyperscaler teams all compete. It is memory, where three companies control effectively all supply and are visibly not racing each other to add it.

For AMD the strategic question that follows is whether it can move the bottleneck – through packaging, through architectural efficiency in how much memory a given workload requires, or through securing long-term supply on fixed terms the way its own largest customers are now trying to do with it.

The concentration risk that sits under everything

AMD’s data-centre growth is a function of a small number of very large buyers. That is true of every accelerator vendor, and it is the structural feature of this cycle that gets least attention when things are going well.

Concentrated demand cuts in both directions. It delivered the doubling that Lisa Su described, and it means a single customer’s decision to pause, re-phase or dual-source has an outsized effect on a quarter. It also transfers negotiating power. When supply of accelerators is scarce, the vendor sets terms. When it is not, the hyperscaler does, and hyperscalers have shown across a decade of infrastructure procurement that they will design their own silicon rather than accept a vendor’s margin indefinitely.

Layer the memory constraint on top and the picture sharpens. AMD is squeezed between suppliers with pricing power and customers with the scale and engineering capacity to build alternatives. It is executing extremely well inside that squeeze – the 50% revenue growth is real and the share gains are real – but the squeeze is why 50% revenue growth produced no margin expansion at all.

What happens next

First, the third-quarter margin print is the whole event. Revenue of roughly $13bn is close to assured given guidance and visible demand. The number that moves the stock is gross margin. Anything above 56% validates the bull case that the memory tax is temporary. Anything at or below it confirms that a richer mix cannot outrun input costs, and the market will start applying that to 2027 estimates.

Second, watch for the use of the August debt proceeds. Multi-billion-dollar raises with no stated purpose get a purpose within two or three quarters. If it turns out to be a large capacity prepayment or a supply-securing commitment, that is a bullish signal about visibility and a bearish one about capital intensity, and investors will have to decide which they weight more.

Third, memory pricing is now an AMD input worth tracking directly. The clearest leading indicator for AMD’s gross margin over the next four quarters is not AMD’s own commentary; it is the contract pricing being set by Micron, SK Hynix and Samsung. We have tracked DDR5 contract prices up nearly 500%, and the first quarter in which that curve flattens is the first quarter AMD’s margin can expand.

Our numbers: bull $700, base $540, bear $310, against a spot of $477.57. What would change our mind on the bear case is a gross-margin print above 57% with memory costs still elevated, which would prove AMD has pricing power it has not yet demonstrated. What would change our mind on the bull case is a hyperscaler publicly committing to in-house silicon for a workload AMD currently serves. For the other side of this trade, our Nvidia analysis covers the incumbent whose margins have so far absorbed the same input shock rather better.

Frequently asked questions

Why is AMD’s gross margin not rising when its product mix is improving?
Because input costs are rising at least as fast as the mix benefit. High-bandwidth memory is consumed per accelerator and its price has risen sharply, with Micron’s gross margin going from 37.7% to 84.6% over the same period. AMD guided third-quarter non-GAAP gross margin to approximately 56%, unchanged, despite guiding revenue 13% higher sequentially.

Is AMD expensive at $477.57?
On any conventional measure, yes. Annualised second-quarter GAAP EPS of $1.38 implies roughly 87 times earnings, and the non-GAAP figure implies about 72 times. The bear case at $310 still leaves the shares near 47 times annualised non-GAAP earnings, which is why we describe the downside as a re-rating rather than a collapse.

Why did AMD raise $4.75bn of debt in August 2026?
The Form 8-K filed on 17 August 2026 documents a four-tranche senior notes offering maturing 2029 through 2036, with the standard general-corporate-purposes language and no named use. AMD generates substantial operating cash flow, so the raise most plausibly pre-funds an unannounced capital commitment or insures against less favourable future funding conditions.

How concentrated is AMD’s data-centre business?
Data Center represented 58% of total company revenue in the second quarter of 2026 and more than doubled year on year, according to CFO Jean Hu. That concentration is the source of the growth and the main single-quarter risk, because a small number of very large customers control the ordering pattern.

What is the most important number in AMD’s next results?
Gross margin, not revenue. Revenue of approximately $13bn is well telegraphed by guidance. Whether gross margin breaks above 56% determines whether the memory cost pressure is a temporary tax or a structural feature of this cycle, and that single line drives the 2027 earnings path.

This article is analysis and information, not investment advice. Scenario levels are the author’s estimates based on company filings and are not price targets or recommendations. Trading and investing carry risk, including the total loss of capital. Figures were verified against primary sources on 5 September 2026 and may have moved since.
The Walt Disney Company is pulling back from another part of its business, marking a significant change for customers in several markets.

The move follows years of changes to Disney’s retail footprint, including the closure of hundreds of physical stores and a greater emphasis on other ways of selling its merchandise.

Now, another piece of that strategy is coming to an end, although Disney has not explained why it is making the latest change.

In 1996, Disney launched the Disney Store website, marking the official entry of The Walt Disney Company into e-commerce.

Disney is closing its online Disney Store

The Walt Disney Company (DIS) is shutting down its Disney Store websites serving Australia, New Zealand, Singapore, and Malaysia.

Customers in those markets will have until Sept. 30, 2026, to place orders. The affected websites will then cease operations at the end of the day, with the Australia and New Zealand storefront officially closing on Oct. 1 local time.

Disney Store Australia and New Zealand are served through DisneyStore.com.au, while customers in Singapore and Malaysia use DisneyStore.asia.

Disney has notified customers that orders placed by the Sept. 30 deadline will continue to be fulfilled. Sold-out products are not expected to be restocked before the closure, while existing return windows and product support policies will continue to be honored after the websites shut down.

The company alerted customers through an “Important Update” message on the affected Disney Store websites.

Although the online storefronts are closing, Disney merchandise will remain available through authorized retailers in Australia, New Zealand, Singapore, and Malaysia. The company has also confirmed that the closure does not affect its Disney Store websites in other markets, including the U.S., U.K., Japan, China, South Korea, the Philippines, and the Middle East.

Disney has not publicly provided a specific reason for ending online Disney Store operations in these four markets.

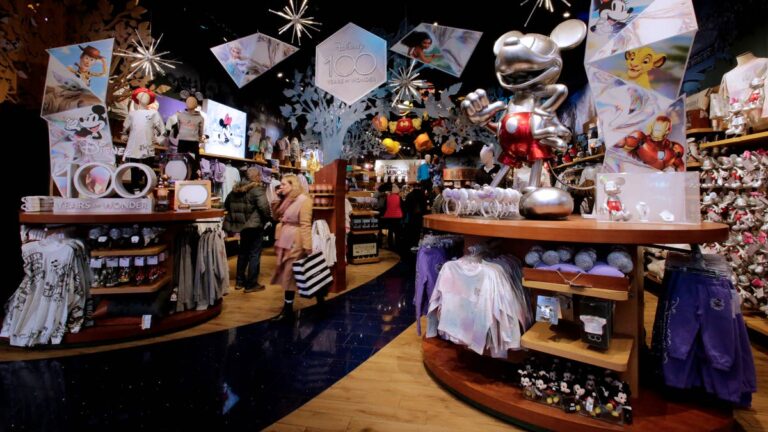
Disney shuts down its online store operations across several international markets.

VIEW press / Getty Images

Disney has reduced its Disney Store physical retail footprint

The online shutdown comes after years of reductions to Disney’s brick-and-mortar retail presence.

In 2021, Disney shared plans to close at least 60 Disney Store locations in the U.S. and Canada as it shifted its focus more toward e-commerce. The company ultimately shuttered dozens of North American locations as part of the broader restructuring of its retail business.

Here’s some of my previous coverage of store closures:

The closures also extended into international markets.

Disney continued reducing its physical retail presence in subsequent years, including the closure of Disney Store locations at Walt Disney World and the company’s last remaining European retail operations in early 2026.

The Disney Store footprint today is considerably smaller than it was several years ago, with the company’s remaining 23 retail locations concentrated in select markets and Disney parks, according to the Disney Store locator.

Why Disney is closing physical and online stores

Disney has not said that declining merchandise demand is the reason for the latest online closures. In fact, the company’s merchandise business has continued to grow.

In the third-quarter fiscal 2026 earnings report, Disney said revenue from merchandise licensing and retail increased 8% to nearly $1.06 billion. The company attributed the increase primarily to a 10% rise in merchandise licensing revenue, partially offset by a 2% decline in merchandise retail revenue.

That distinction is important because the latest Disney Store shutdowns do not necessarily indicate a decline in demand for Disney merchandise. Instead, the closures are another example of Disney adjusting how and where it sells its merchandise.

For shoppers in Australia, New Zealand, Singapore, and Malaysia, however, the change means the end of a direct online shopping option from Disney.

Disney has not disclosed whether the decision is tied to profitability, operating costs, logistics, local market conditions, or another factor.

For now, the company has only confirmed the closure and directed customers toward authorized retailers for future purchases.

Related: Disney closes iconic store after 33 years