BNB cryptocurrency can be expected to rise further toward the next resistance level 750.00 (former support from the start of October).
BNB reversed from key support level 705.00
Likely to rise to resistance level 750.00
BNB cryptocurrency recently reversed up from the support zone between the key support level 705.00 (which reversed the price twice in September, as can be seen from the daily BNB chart below), lower daily Bollinger Band and the 38.2% Fibonacci correction of the upward impulse from the start of July. The upward reversal from this support zone created the daily Japanese candlesticks reversal pattern Bullish Engulfing, which stopped the earlier minor ABC correction b – that belongs to the short-term correction B from the start of October.
Given the oversold daily Stochastic, clear daily uptrend and the relative strength of BNB against the cautious crypto sentiment seen today, BNB cryptocurrency can be expected to rise further toward the next resistance level 750.00 (former support from the start of October).
The subject matter and the content of this article are solely the views of the author. FinanceFeeds does not bear any legal responsibility for the content of this article and they do not reflect the viewpoint of FinanceFeeds or its editorial staff.
The information does not constitute advice or a recommendation on any course of action and does not take into account your personal circumstances, financial situation, or individual needs. We strongly recommend you seek independent professional advice or conduct your own independent research before acting upon any information contained in this article.
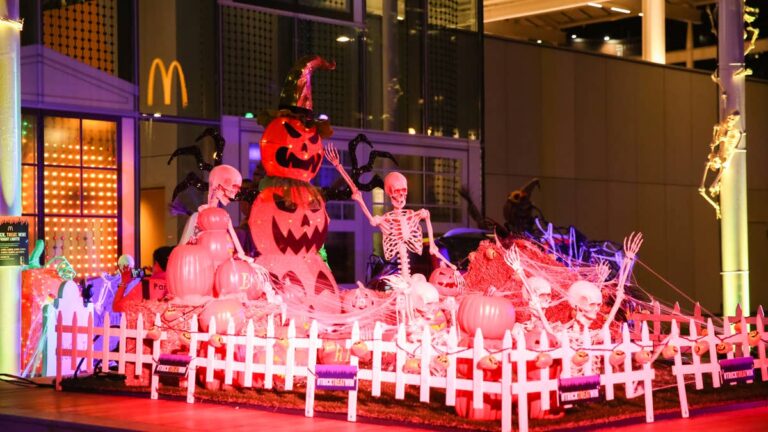
For most American families, Halloween at McDonald’s (MCD) has meant one thing: a plastic pail called a Boo Bucket that outlasts the Happy Meal and treats inside.
The chain first offered the promotion in 1986 and brought it back annually starting in 2022 after a six-year hiatus, but this year’s edition carries a twist collectors are already circling.
Starting today, October 20, McDonald’s is rolling out its first-ever Disney-branded Boo Buckets, according to a press release, and they are available at all participating U.S. locations. This makes them the first major licensed-character Boo Buckets since 2016.
Meet the five villains hiding inside the Happy Meal
The 2026 lineup features Jafar from Aladdin, Ursula from The Little Mermaid, Scar from The Lion King, Cruella de Vil from 101 Dalmatians, and Maleficent from Sleeping Beauty. Each bucket arrives with a villain-themed lid and a sticker sheet filled with movie details, so kids and adults can personalize the pail, according to McDonald’s.
McDonald’s leaned into the drama. “This spooky szn, we’re entering our villain era,” the company said in a statement, calling the lineup “inspired by Disney’s most notorious scene-stealers,” Good Morning America reported.
The chain also pitched the full set as a chase, saying, “There’s a Boo Bucket for every kind of Villains fan,” according to McDonald’s announcement.
McDonald’s has celebrated Halloween with its customers for decades, and this year it is doing it with the return of the Boo Buckets.
Why 40 years of nostalgia makes this launch feel different
Boo Buckets debuted in 1986 as part of McDonald’s original Halloween Happy Meal, Tasting Table reported. 2026 marks the promotion’s 40-year anniversary, and the Villains edition finally gives millennial and Gen X parents a reason to visit for themselves.
Last year’s set featured Ghost, Pumpkin, and Goblin (the classic trio) plus new Cat and Zombie designs, the Disney Food Blog noted.
Mike Bullington, who serves as McDonald’s archivist, points to millennial nostalgia and multi-generational family traditions as what makes the pails stick in consumers’ minds.
Across decades of alternating Halloween promotions, the buckets have remained deeply anchored in pop culture because parents who collected them as children in the 1980s and 1990s now pass the tradition down to their own kids.
“The pails have always been the most popular” seasonal item because they swap out a temporary plastic toy for a highly reusable piece of functional holiday memory, Bullington noted in an interview with The Hustle.
This immense nostalgic demand directly drives the secondary market. Complete sets of the newly launched Disney Villains Boo Buckets are commanding opening prices of $100 or more on resale forums this week, a massive premium over the standard $5.00 Happy Meal retail price.
For example, at the time of writing, active listings on eBay feature full sets starting at $104.95, while individual character buckets like Maleficent and Scar are drawing opening asks of nearly $30.00 each.
What McDonald’s isn’t telling you about completing the set
Completing all five Villains means buying at least five separate Happy Meals, and McDonald’s has not confirmed whether customers can request a specific villain at the counter or drive-thru. Distribution is largely random, so trading with family and coworkers may be the most reliable path to a full set.
Two other blind spots are the exact Happy Meal price, which varies by location, and how much inventory each store receives. The buckets are strictly “while supplies last,” Taste of Home reported. In recent years, popular designs have cleared shelves days before Halloween night, so grabbing a specific villain this week might be better than waiting.
The business bet behind the buckets, and what it means for MCD stock
McDonald’s is leaning on nostalgia for a reason. CEO Chris Kempczinski has repeatedly flagged a strained customer base. “It’s really kind of a two-tier economy,” Kempczinski told CNBC in September 2025, noting middle- and lower-income customers are “feeling under a lot of pressure right now,” according to CNBC.
Mark Zandi, chief economist at Moody’s Analytics and a leading voice on household finance for over two decades, agreed: “It really is a tale of two different households.”
That strain shows up in the stock price. McDonald’s is trading at $245.73 at the time of writing, up 1.26% on the day and 4.43% over the past five sessions, yet still down 18.97% year-to-date and well below its 52-week high of $341.75.
The company carries a market cap of $173.89 billion and a 3.14% dividend yield, giving long-term holders some income cushion. McDonald’s earns most of its revenue from franchise royalties and rent collected from its 45,699 systemwide restaurants, so even modest weekly changes in traffic move cash flow.
The Villains launch pairs with McDonald’s broader “McValue 2.0” push of $3 items and $4 breakfast combos. The real test comes October 28, when McDonald’s reports third-quarter earnings and investors see whether Disney villains on a plastic pail boosted traffic.
The Nasdaq Composite rose on Monday as investors returned to technology and artificial intelligence-related stocks following last week’s sharp selloff, while markets looked ahead to earnings from major US companies.
The tech-heavy index gained 1.1%, while the S&P 500 advanced 0.4%. The Dow Jones Industrial Average finished slightly below the flatline.
The rebound followed a difficult week for US equities, with the S&P 500 falling nearly 2% and the Nasdaq declining 4.5%.
Both indexes recorded their biggest weekly losses since late June.
The information technology sector also posted its worst weekly performance since April 2025.
Investors have become increasingly concerned about the cost of financing AI infrastructure and whether future earnings growth will justify the substantial investments being made across the sector.
Chip stocks recover as semiconductor index ends losing streak
Semiconductor stocks helped support the market recovery.
The Philadelphia Semiconductor Index ended an eight-session losing streak during which it had fallen approximately 15.7%, marking its longest run of declines since October 2008.
The recovery followed heavy selling in technology stocks last week, when investors reassessed the financial risks associated with the AI investment boom.
The technology sector was the most net-sold global sector, according to Goldman Sachs, with hedge funds selling a record proportion of their technology holdings.
CoreWeave’s stock plunged more than 25% last week amid concerns about its debt burden, reported at around $50 billion.
The company’s credit default swaps also reached distressed levels, reflecting growing unease in the corporate bond market.
AI financing concerns remain a key market risk
Investor concerns intensified after reports that Anthropic generated $16.8 billion in third-quarter revenue, up from $11.6 billion in the second quarter.
Although revenue increased, the figures prompted questions about the pace of growth relative to the scale of investment in AI infrastructure.
Market participants are increasingly assessing whether AI-related companies can generate sufficient returns on capital to justify their borrowing and infrastructure spending.
The recent pressure on CoreWeave has also raised questions about the resilience of AI investments in an environment of higher interest rates.
If earnings growth moderates, concerns about debt financing could leave the broader market more vulnerable to further volatility.
Other cloud computing companies, including Nebius and Iren, outperformed CoreWeave on Monday.
Oil prices and corporate earnings remain in focus
Developments in energy markets added another source of uncertainty for investors. Attacks on shipping and energy infrastructure in the Persian Gulf, alongside continued strikes involving Russia and Ukraine, have raised concerns about prolonged supply disruptions.
US West Texas Intermediate crude futures settled 2.06% higher at $103.50 a barrel. Brent crude futures, meanwhile, fell 0.41% to $109.41 a barrel.
Higher oil prices can add to inflationary pressures and complicate the outlook for interest rates.
Investors are also preparing for a busy week of corporate earnings.
Meta Platforms and Tesla are scheduled to report results on Wednesday, while SpaceX is due to report on Tuesday.
The results could help investors assess the outlook for technology spending, AI-related investment, and corporate profitability as markets attempt to recover from last week’s losses.
Global markets face inflation pressures, central bank divergences, Middle East energy supply disruptions, and tech sector turbulence affecting risk assets.
Persistent Inflation Pressures and Central Bank Policy Divergence
Recent economic data has confirmed that the inflation tightness building since the summer is far from transient. Hotter-than-expected US Consumer Price Index (CPI) and Producer Price Index (PPI) reports have reinforced expectations that the Federal Reserve will implement a 25-basis-point interest rate hike at its December 9 meeting, following an anticipated pause on October 28. This hawkish outlook stands in sharp contrast to other central bank trajectories. In Canada, headline inflation rose to 3.1% year-over-year in September, missing forecasts and pushing institutions like Scotiabank and the Bank of Montreal to call for a preemptive rate hike to narrow the policy gap with the United States. Meanwhile, the Swiss National Bank maintains its policy rate at 0% while its inflation stays within the 0% to 2% range, further cementing the divergence between the Greenback and its global peers.
Middle East Geopolitics and Energy Supply Disruptions
Geopolitical tensions in the Middle East have served as a primary catalyst for global energy shocks and subsequent pricing volatility. Ongoing conflicts in the Persian Gulf—highlighted by Houthi attacks on the Shaybah oilfield and Yanbu Aramco site, alongside disruptions in the Strait of Hormuz—have kept supply risks elevated and fed directly into broader global price data. West Texas Intermediate (WTI) crude initially rallied past $99.00 on unconfirmed reports of US strikes and restricted maritime traffic. However, prices later retreated after US President Donald Trump signed an order temporarily waiving specific Russia sanctions and tariffs on the largest buyers of Russian crude, providing alternative supply pathways for nations like India and temporarily easing upward pressures.
Tech Sector Volatility and Risk-Asset Sentiment Shifts
Global equity markets experienced significant turbulence driven by a synchronized correction in technology stocks and broader risk-off sentiment. The tech-heavy Nasdaq suffered steep losses, exacerbated heavily by severe financial distress and soaring debt yields at AI infrastructure provider CoreWeave. Rather than dragging down the broader currency, this tech sector unwind prompted foreign investors to rotate out of equities and back into safe-haven US Treasuries and government bonds. Consequently, the shifting risk appetite has influenced broader safe-haven flows, capping the upside for alternative non-yielding assets like Gold while reinforcing the defensive appeal of the US Dollar.
Top economic events for next week:
10/20/2026 01:15:00 – PBoC Interest Rate Decision: This medium-impact Chinese central bank decision dictates monetary policy direction and borrowing costs for the world’s second-largest economy, heavily influencing regional market sentiment and commodity demand.
10/20/2026 06:00:00 – Employment Change (3M): As a high-impact UK labor metric, this report offers crucial insights into job growth trends, directly shaping the Bank of England’s upcoming policy decisions regarding interest rates.
10/20/2026 06:00:00 – Claimant Count Change: This high-impact UK release tracks changes in jobless claims, providing a timely snapshot of labor market health and economic stress facing British workers and businesses.
10/20/2026 06:00:00 – ILO Unemployment Rate (3M): This key high-impact UK unemployment measure evaluates overall labor resource utilization, serving as a primary indicator for wage pressures and broader economic stability.
10/20/2026 09:00:00 – ZEW Survey – Economic Sentiment: This medium-impact European survey gauges institutional investor and analyst outlooks on economic recovery, providing forward-looking sentiment direction for the Eurozone.
10/20/2026 12:30:00 – Housing Starts (MoM): Tracking new residential construction projects, this medium-impact US data release measures consumer confidence, real estate sector strength, and broader economic momentum.
10/21/2026 06:00:00 – Consumer Price Index (YoY): This high-impact UK inflation reading measures annual price changes across consumer goods, playing a pivotal role in determining household purchasing power and central bank policy paths.
10/21/2026 06:00:00 – Core Consumer Price Index (YoY): By stripping out volatile food and energy costs, this high-impact UK metric provides a clearer picture of underlying structural inflation trends for policymakers.
10/21/2026 16:30:00 – ECB’s President Lagarde speech: This high-impact address by the European Central Bank President provides vital commentary on monetary policy direction, inflation outlooks, and economic health across the Eurozone.
10/21/2026 14:30:00 – EIA Crude Oil Stocks Change: Tracking weekly US petroleum inventories, this report directly impacts global crude pricing dynamics, supply-demand balances, and energy sector equities.
The subject matter and the content of this article are solely the views of the author. FinanceFeeds does not bear any legal responsibility for the content of this article and they do not reflect the viewpoint of FinanceFeeds or its editorial staff.
The information does not constitute advice or a recommendation on any course of action and does not take into account your personal circumstances, financial situation, or individual needs. We strongly recommend you seek independent professional advice or conduct your own independent research before acting upon any information contained in this article.
To accomplish this, AT&T vowed to “work diligently” to resolve fiber internet service outages lasting 20 minutes or more and wireless outages lasting 60 minutes or longer, with affected customers receiving an automatic credit equal to one day of service.
The company also promised more customer deals, a five-minute target for connecting callers with tech support experts, and same-day or next-day technician appointments for fiber internet equipment assistance.
AT&T promises customers better tech support
Amid heightened wireless competition, AT&T is now expanding its “America’s Best Guarantee” to “deliver a faster, simpler experience,” according to an Oct. 15 press release. This includes doubling down on its promise to speed up tech support for its customers.
The carrier is now guaranteeing that customers who call AT&T will be connected to a live expert within “5 minutes or less,” and if not, they will be offered a callback at a time they choose.
Also, customers who pair AT&T Fiber or AT&T Internet Air and wireless will have “one dedicated technical expert to assist from start to finish.” It said that if it falls short of these promises, the “Guarantee proactively makes it right with a benefit.”
AT&T said it chose to expand its guarantee after a recent survey by Harris Poll found that 60% of Americans flagged being transferred from one agent to the next as a top pet peeve. Also, more than 3 in 4 Americans said 15 minutes is the most they’re willing to wait to be connected to customer support.
“Customers want support that is simple, fast, and transparent,” said Jenifer Robertson, executive vice president of AT&T Consumer, in the press release.
“This is about more than speed — it’s about removing friction and earning trust in every interaction,” she continued. “We’re setting a clear standard for the experience customers should expect and holding ourselves accountable when we miss it.”
AT&T has expanded its AT&T Guarantee with new promises to customers.
The move from AT&T comes after a recent J.D. Power survey found that the carrier falls behind its top rivals in customer satisfaction.
According to the survey, the average customer satisfaction score for postpaid mobile network operators is 612. T-Mobile ranks first place with an above-average score of 636, while Verizon takes second place with a 606 score, and AT&T ranks third with 596.
Several mobile virtual network operators (MVNOs) surpassed most of the big three wireless carriers in customer satisfaction.
In the MVNO postpaid segment, the average customer satisfaction score is 641. Consumer Cellular ranks No. 1 in this category with a score of 720, followed by Google Fi Wireless (673) and Spectrum Mobile (627).
Carl Lepper, an industry analyst and senior director of TMT and utilities practice at J.D. Power, said in the survey release that the big three wireless carriers have been ramping up their efforts to improve the customer experience “across multiple fronts,” which is successfully boosting customer satisfaction throughout the industry.
He said the use of artificial intelligence in customer support is one of the factors contributing to this shift.
“One trend to watch is the increased presence of AI in the phone-based customer support function, which is driving high levels of customer satisfaction when it works, but is currently only working about half the time,” said Lepper.
“Based on how effectively carriers integrate AI into their operations, we could see the technology start to influence the overall customer experience in a meaningful way.”
As AT&T focuses on improving its live customer support, its rivals have been doing the same while increasingly incorporating AI.
For instance, last year, Verizon began leveraging Google Cloud’s AI to help resolve customer issues. The technology also updates customers via the My Verizon app, text messages, or callbacks on how those issues are being addressed.
In addition, the carrier also began allowing customers to speak with a live agent 24/7 and access 24/7 live chat support.
On the other hand, T-Mobile has been making its customers more reliant on its T-Life app for support and key account changes. For example, it embedded an always-on artificial intelligence assistant into the app last year to help customers address account issues or questions about offerings.
Also, a leaked internal memo in May revealed that T-Mobile is aiming to make customers and employees 100% dependent on the T-Life app to conduct phone upgrades and add new lines to their accounts.
No. 1 pick Gavin McKenna meets No. 2 Ivar Stenberg as the Toronto Maple Leafs host the San Jose Sharks on Monday. Live coverage on Sportsnet+ begins at 7 p.m. ET / 4 p.m. PT, or follow along with our live tracker.
Anthropic’s potential initial public offering is facing an early test of investor appetite, with some prospective and existing investors reportedly considering a valuation of around $1.5 trillion, below the roughly $2 trillion target previously expected for its November listing.
The reassessment follows a slowdown in the company’s sequential revenue growth and comes as investors grow increasingly concerned about the cost of financing artificial intelligence infrastructure.
A lower valuation could create pressure across AI-related stocks, particularly companies exposed to the enormous spending commitments of leading AI developers.
The figures demonstrate substantial growth, even as some investors question whether the company’s valuation adequately reflects its slowing growth rate and significant future spending requirements.
According to a Reuters report citing people familiar with the matter, some current and prospective Anthropic investors discussed a valuation of approximately $1.5 trillion during the company’s investor day in San Francisco on Wednesday.
That would represent a $500 billion reduction from the roughly $2 trillion valuation investors had previously expected for the planned November share sale.
The discussions followed disclosures that Anthropic’s revenue growth had slowed sequentially in the third quarter.
Revenue more than doubled from the first quarter to $11.6 billion in the second quarter, before rising 45% to $16.8 billion in the third quarter.
Although the latest growth remained substantial, the deceleration disappointed some investors who had expected the company to sustain its earlier momentum.
Anthropic’s financial performance is particularly important because the company has committed to enormous infrastructure spending.
According to the company’s IPO prospectus, it has pledged to spend at least $518 billion over a decade on cloud services, computing and infrastructure, Reuters had reported in September.
The prospectus also showed a loss of $42 billion in 2025 and projected further spending for the upcoming AI buildout.
Last year, revenue surged twelvefold to nearly $4.6 billion, while the company recorded an operating loss exceeding $8 billion, excluding certain liability write-downs.
These figures highlight the challenge facing investors: Anthropic is growing rapidly, but its future value depends partly on its ability to turn that growth into sustainable financial returns while meeting substantial computing costs.
A lower IPO valuation could therefore reflect a reassessment of the price investors are willing to pay for that growth, rather than a rejection of the company’s business altogether.
Slowing growth does not necessarily signal weak AI demand
The central question is whether Anthropic’s slower sequential growth reflects weakening demand for AI or increasing competition from alternative providers.
One possibility is that customers are shifting spending towards competitors, including OpenAI, which launched its Astra model in early September, or other AI services.
Meta Platforms could also capture a larger share of the market.
Such a shift would not necessarily be negative for the broader AI industry.
If overall spending continues to increase, one provider’s slower growth could be offset by stronger demand elsewhere.
The more concerning possibility would be that businesses are reducing their AI investments altogether.
However, available usage data suggests that adoption continues to expand.
OpenRouter, a start-up that helps developers route requests across AI models, reported that weekly token consumption reached 172 trillion as of the previous week, up from 46.7 trillion at the end of June.
Tokens are the basic units of text and other data processed by AI models.
Wedbush Securities analyst Matt Bryson also argued that Anthropic’s results should not automatically be interpreted as evidence of slowing AI spending.
In a note to clients, Bryson said annualising revenue trends over very short periods can be misleading, particularly when based on indirect reports.
He also pointed to increased competition from alternatives to Anthropic, including Muse and Copilot, while noting that Anthropic still achieved 45% sequential revenue growth.
Bryson added that Wedbush had not seen indications of slowing hardware demand.
He cited rising GPU rental prices, including for older systems, and said concerns about financing costs and foundation-model growth did not appear to be affecting AI demand or supply-chain dynamics.
Cheaper AI models could benefit cloud and infrastructure firms
Another explanation for Anthropic’s slower growth is the increasing use of open AI models, which are generally less expensive and can be adapted for more efficient applications.
Improvements in hardware efficiency can also reduce the cost of processing AI tokens.
This creates a potential shift in how value is distributed across the AI industry.
Anthropic and OpenAI spend heavily on developing advanced, or frontier, models.
If customers increasingly turn to cheaper alternatives, these developers could face pressure to justify their spending and valuations.
Cloud providers and companies supplying computing infrastructure, however, could still benefit from rising overall usage.
Amazon, Microsoft and Alphabet’s Google operate cloud businesses that can host a range of AI models.
Greater use of open models could generate additional demand for their computing services without requiring them to share the revenue generated by developing those models.
Gavin Baker, chief investment officer of Atreides Management, said in a post on X on Thursday that
“Open-source growing much faster than either Anthropic or OpenAI. Modal tripled since May and is 15x YoY per yesterday’s announcement. Open-source tokens generate more revenue and profit for the hyperscalers/neoclouds than frontier tokens. *Every* open source inference cloud I am aware of is growing faster both sequentially and YoY than either Anthropic or OpenAI. And their combined compute spend is becoming material.”
The argument points to a potential divergence within the AI trade.
Investors may become more selective about which companies capture the financial benefits of growing AI adoption, rather than treating all AI-linked businesses as beneficiaries of the same investment cycle.
Nevertheless, the distinction should not be overstated.
Anthropic and OpenAI remain important sources of spending on cloud computing, chips and networking equipment.
A sharp deterioration in their financial prospects could still affect the companies supplying their infrastructure.
The open AI models also remain heavily influenced by Chinese providers, despite efforts by Meta and Nvidia to strengthen the position of US-developed alternatives.
What a lower Anthropic valuation could mean for AI investors
A scaled-back IPO valuation could weigh on sentiment if investors interpret it as evidence that expectations for AI growth have become excessive.
The concern is particularly relevant amid a broader technology selloff that has hurt chipmakers, AI infrastructure companies and neocloud providers.
CoreWeave’s recent share and bond declines illustrate the market’s sensitivity to the financing requirements of the AI buildout.
A disappointing Anthropic listing could add to concerns about whether the sector’s enormous spending commitments can generate sufficient returns.
Anthropic’s IPO is also important because investors increasingly view the anticipated listing, followed by a potential OpenAI offering, as a test of demand for major AI companies in public markets.
Yet a lower valuation could also represent a more cautious pricing of future growth, rather than the collapse of the AI investment thesis.
At $1.5 trillion, Anthropic would still command an enormous valuation for a company founded in 2021.
Friday’s Bank of England headlines did not produce the FTSE 100’s week. London missed the chip trade. The cash index closed Friday 16 October 2026 at 10,881.90. Dow Jones, via Morningstar, puts the week at 329.85 points, or 3.13 percent, the largest one-week gain since the week ending 2 April 2026, and puts Friday itself at 41.55 points, or 0.38 percent. The Evening Standard prints the same close and the same 41.55 points, then rounds the day to 0.4 percent and the week to 3.1 percent. This article does not average those percents.
The miss is the clock. Take 41.55 off 329.85 and 288.30 points were already in before Friday’s close. Bailey spoke on Friday in Bangkok, so he cannot explain Monday through Thursday. Scottish Mortgage and Polar Capital Technology fell while defense rose. From 9 October to 16 October, QQQ fell 5.52 percent and the UK ETF EWU rose 3.20 percent. Neither is the cash index. The closes used here are Friday’s official prints.
Key facts
FTSE 100 closed Friday 16 October 2026 up 41.55 points, 0.4 percent, at 10,881.90. The week was up 3.1 percent. FTSE 250 closed at 24,533.90, up 0.5 percent on the day and 1.3 percent on the week. AIM all-share closed at 773.12, up 1.1 percent on the day and down 0.4 percent on the week. Source: Evening Standard, Jeremy Cutler, 16 October 2026.
Dow Jones puts that close at 10,881.90, up 329.85 points, or 3.13 percent, on the week, and up 41.55 points, or 0.38 percent, on the day. Largest one-week gain since the week ending 2 April 2026. Off 0.26 percent from the record close of 10,910.55 on 27 February 2026. Year to date up 950.52 points, or 9.57 percent. Source: Dow Jones, 16 October 2026, via Morningstar.
Bailey in Bangkok: “To the extent we have seen evidence, it’s quite subdued,” and “It’s too early.” Ahead of the Middle East conflict, “the market was pricing a couple of cuts, and I thought that was probably pretty reasonable.” Source: the Standard, 16 October 2026.
NatWest fell 1.2 percent and Lloyds fell 0.9 percent. The Standard, citing the Guardian, said Chancellor John Healey is poised to tax banks more heavily in the 28 October budget. Reversing the bank-surcharge cut would raise upwards of £2 billion a year. Source: the Standard, 16 October 2026.
EWU closed at $48.01, up $1.49, or 3.20 percent, from $46.52 on 9 October. QQQ closed at $709.80, down $41.47, or 5.52 percent, from $751.27, and down 2.50 percent on Friday. Source: Nasdaq files saved 18 October 2026. Both are ETFs.
Hargreaves Lansdown’s FTSE 100 page, fetched Sunday 18 October, still showed 10,881.90 and a change of 41.55. The market was closed. Source: Hargreaves Lansdown.
The Bank of England’s latest decision in the X timeline fetched here, 17 September 2026: “The Monetary Policy Committee voted 6-3 to keep the interest rate at 3.75%.” Source: Bank of England on X. Not a Friday index comment.
A separate Friday FX note said 54 of 63 economists in a Reuters survey look for a 25 basis point Bank hike in November. Source: FinanceFeeds. The Standard’s pound quote was $1.3339.
What just happened, and why the obvious reading is wrong
The obvious reading is that Bailey calmed inflation and London rallied more than 3 percent. The order is wrong. The week is 329.85 points. Friday is 41.55 of them. A reader who stops at “up 3.1 percent” and “quite subdued” has joined two clocks.
The two week percents are one division. Dow Jones prints 10881.90. Take 329.85 off 10,881.90 and the implied 9 October close is 10,552.05. Divide 329.85 by 10,552.05 and the result is 3.126 percent. Dow Jones rounds to 3.13 percent. One decimal place is 3.1 percent, the Standard’s print. Averaging them would invent a third number. The title uses the Dow Jones 3.13 percent and names that source.
The day splits the same way. Take 41.55 off 10,881.90 and the implied Thursday close is 10,840.35. Divide 41.55 by 10,840.35 and the result is 0.383 percent. Dow Jones rounds to 0.38 percent. The Standard rounds the same points to 0.4 percent. Both pages agree on the points and the close.
Dow Jones also says the index is up 231.57 points, or 2.17 percent, over three sessions, the largest three-day gain since 28 July 2026, and up for two weeks running. Friday is 41.55 of those points. Wednesday and Thursday are the other 190.02.
Friday is not a record. The record close in that note is 10,910.55 on 27 February 2026. The gap is 28.65 points, or 0.263 percent, printed as off 0.26 percent. Year to date the note says up 950.52 points, or 9.57 percent. From a 52-week low of 9,354.57 on 17 October 2025 the rise is 16.33 percent. A claim that Friday was the highest close since 25 August 2026 was not in the fetched data talk and is dropped.
The Standard’s New York paragraph is a separate trap. It says the Dow was up 0.2 percent, the S&P 500 was 0.4 percent lower, and the Nasdaq Composite fell 1.2 percent, “at the time of the closing bell in London on Tuesday.” The word Tuesday is in the sentence. Those three percents are not used here as Friday’s US closes. The US comparison in a saved file is QQQ.
Who is exposed
Three cash books, not one. FTSE 100 holders mark 10,881.90. FTSE 250 holders mark 24,533.90, a smaller week at 1.3 percent. AIM holders mark 773.12 and a down week of 0.4 percent. “London was up” is a large-cap sentence.
Inside the FTSE 100 the mix is the exposure. Babcock rose 3.6 percent, up 33.4p at 961.8p. WPP rose 3.1 percent, up 12.3p at 412.7p. Weir rose 2.6 percent, up 68p at 2,682p. BAE Systems rose 50p to 1,983.5p. Kingfisher rose 9.7p to 348.8p. Those are defense, advertising, engineering, and retail, not chip foundries.
The chip spillover that does sit in the index showed up in the trusts. Scottish Mortgage fell 50p to 1,545p. The prior price is 1,595p, so the day is 3.13 percent down. That 3.13 is a one-day trust move, not the index’s 3.13 percent week. Polar Capital Technology fell 11.5p to 635p, or 1.78 percent. AstraZeneca fell 252p to 12,446p.
Banks are a tax book, not a Bailey book. NatWest fell 1.2 percent, down 8p at 666p. Lloyds fell 0.9 percent. The Standard gives no Lloyds price, so none is invented. Citing the Guardian, it says Chancellor John Healey is poised to tax banks more heavily in the 28 October budget. One option is reversing Jeremy Hunt’s cut to the bank surcharge, which the Standard says would raise upwards of £2 billion a year. The surcharge is 3 percent on top of 25 percent corporation tax, cut from 8 percent when corporation tax rose from 19 percent. Customers are not the Friday sellers. Holders marking a leak are.
On the FTSE 250, THG rose a further 9.1 percent. Man Group added 1.1 percent after assets rose to $270.9 billion, with net inflows of $10.1 billion. Iofina fell 9.1 percent on a guidance cut.
EWU at $48.01 is a US-listed claim on UK equities, not a FTSE 100 future. Its week was 3.20 percent against the cash index’s 3.13 or 3.1. QQQ fell 5.52 percent on the week and 2.50 percent on Friday, from $728.00 to $709.80. In the saved EWU file the high is $49.39 on 25 August, so Friday’s $48.01 is 2.79 percent under that ETF high, not 0.26 percent under the cash record. The US chip week is in the Nasdaq week’s own note and in the session when every chip-index name fell. Those pages are not a second print of 10,881.90.
What the tape actually shows
Every row is the fetched Standard, the fetched Dow Jones data talk, or a Nasdaq file saved for this piece. Implied closes are labeled. The chart is EWU. It does not plot 10,881.90.
Print
Source and date
Figure
What it is not
FTSE 100 Friday
Evening Standard, 16 Oct 2026
10,881.90, up 41.55 points, 0.4 percent
Not the week. Not the 0.38 percent day.
FTSE 100 week
Dow Jones via Morningstar, 16 Oct
Up 329.85 points, or 3.13 percent
Not an average with 3.1 percent.
Before Friday
Arithmetic on the Dow Jones lines
288.30 points, 87.4 percent of the week
Implied Thursday close 10,840.35.
Record
Dow Jones, 16 Oct 2026
10,910.55 on 27 Feb. Friday is 0.26 percent under it
Not a new high.
FTSE 250 and AIM
Evening Standard, 16 Oct
24,533.90, week up 1.3 percent. AIM 773.12, week down 0.4 percent
Not the FTSE 100.
EWU
Nasdaq file, 16 Oct close
$48.01, week up 3.20 percent from $46.52
Not 10,881.90.
QQQ
Nasdaq file, 16 Oct close
$709.80, week down 5.52 percent. Friday down 2.50 percent
Not the Nasdaq 100 level. Not the Standard’s Tuesday line.
Nasdaq daily closes for the iShares MSCI United Kingdom ETF (EWU) from January through 16 October 2026. The ETF closed at $48.01, up $1.49 from $46.52 on 9 October. This is the ETF, not the FTSE 100 cash index. FinanceFeeds chart from the file saved 18 October 2026.
EWU’s Friday bar is $48.01 against Thursday’s $47.76, up $0.25, or 0.52 percent, on 747,653 shares. A 0.52 percent ETF day does not confirm a 0.38 percent or a 0.4 percent index day. From 9 October the ETF path was $46.70, $46.82, $46.91, $47.76, then $48.01. QQQ went from $751.27 to $709.80, a drop of $41.47. Friday alone was $18.20. A story that London followed a rising Wall Street on Friday needs a US tape that rose. This file does not have one.
What Bailey, Pill, Warsh, and the banks said
Bailey’s words are narrower than the rally headline. At the IMF meeting in Bangkok he said evidence of second-round effects was limited. “To the extent we have seen evidence, it’s quite subdued,” he said, adding, “It’s too early.” The Standard reports, not in quotation marks, that policy was already restrictive. On the path before the conflict the quotation is: “the market was pricing a couple of cuts, and I thought that was probably pretty reasonable.” He added that the economy was “more resilient than we expected it to be.” The cuts line describes a market from before the conflict. It is not a promise from 10,881.90.
Huw Pill, the chief economist, is earlier in the week and is not directly quoted. The Standard says he said the four hikes priced into money markets look overdone. That stays a paraphrase, and it is not Friday’s story. Four hikes looking overdone is not the same sentence as a couple of cuts having looked reasonable before the conflict. One is the market now. The other is the market then.
Kevin Warsh, the Federal Reserve chair, would not match that specificity. “I don’t prejudge meetings,” he said to IMF managing director Kristalina Georgieva. “I don’t believe in saying now what I might do at the meetings that we have in the balance of the year.” The Standard says UBS notes he has been “loath” to give explicit guidance. That word is the paper’s report of UBS, not a Warsh sentence.
The Bank’s X account, in the timeline fetched here, last posted a decision on 17 September 2026: “The Monetary Policy Committee voted 6-3 to keep the interest rate at 3.75%.” That is the level under the “already restrictive” paraphrase. No October vote is in that timeline.
Emmanuel Cau, a Barclays strategist, supplied the equity sentence, and it is about AI, not Threadneedle Street. He suggested the “best of the AI trade may be over, yet we wouldn’t throw the baby out with the bathwater. BigTech earnings will be key.” He also said “the maturing phase of the cycle means it is no longer a one-way trade, which comes with lower valuation and more dispersion.” Dispersion is the Friday tape: Babcock up 3.6 percent, Scottish Mortgage down about 3.1 percent on the day, the index up a fraction. The Standard names Meta and Tesla next week, plus IBM and Texas Instruments. Its Tesla line, down 1.0 percent, sits in the paragraph that says “on Tuesday,” so it is not used as Friday’s close. Babcock, WPP, Weir, NatWest, and Lloyds appear as prices, not as quotes. Man Group’s fetched line is the $270.9 billion asset update, not a comment on Bailey.
The rate path, the tax, and a chip week
Friday’s gain and Friday’s rate talk point different ways, and neither is the whole week. “Quite subdued” and “too early” argue against treating second-round inflation as already proved. Pill’s paraphrase argues against the hawkish end of the market. The pre-conflict cuts line is a third clock. A November hike survey is a fourth.
That survey is in a separate Friday FinanceFeeds FX note. It says 54 of 63 economists expect a 25 basis point hike in November, with sterling above $1.3350. The Standard’s pound in the equity report was $1.3339, up from $1.3254. Two prints, and this article does not pick a fix. A hike survey and a governor describing an older cut path were both on Friday’s pages. The FTSE 100’s week was mostly in the market before either paragraph.
The tax is what showed up in relative prices. NatWest and Lloyds fell while the index rose. The £2 billion figure is the Standard’s account of the Guardian, dated to 28 October, with the surcharge at 3 percent now and 8 percent before Hunt’s cut. The CAC 40 rose 0.3 percent and the DAX rose 1.0 percent.
A Wednesday US CPI figure of 3.7 percent was not in the Friday pages used here, so it is dropped. Sharecast and Reuters did not load. The numbers above are the Standard, the Dow Jones data talk, and the ETF files.
What happens next
Monday 19 October is the next London session. The Standard’s calendar has ITM Power and Tristel results, China GDP and retail sales overnight, and Canadian inflation. None of that is Bailey. If the 3.13 percent week was a defensive bid that finished with Friday’s 0.38 percent, Monday does not need another 40-point day to confirm a speech. If Scottish Mortgage and Polar Capital Technology keep falling while Babcock does not, the chip spillover is still a trust story. The causal chain is QQQ’s 2.50 percent Friday drop: a further US chip leg hits the trusts first and the FTSE 100 last.
The following week is the slate Cau named, Meta and Tesla first. If those reports extend the QQQ decline, London’s lack of that revenue is why a 3.13 percent UK week and a 5.52 percent ETF decline can share five sessions. If the reports stop the decline, the test is Cau’s dispersion line, not a new index high. The cash index is still 28.65 points under 10,910.55.
28 October is the budget date in the Standard. The chain runs through NatWest and Lloyds. A surcharge reversal on the scale described gives Friday’s bank declines a fiscal source. A budget that leaves the 3 percent surcharge alone makes Friday a leak. The index can still be up 950.52 points on the year either way. November is only a survey horizon: 54 of 63 economists in the FX note. The last Bank post in the fetched timeline remains the 17 September hold at 3.75 percent.
This is not financial advice.
Frequently asked questions
Did Bailey’s inflation line do that, or did London miss the chip trade?
London missed the chip trade. Friday was 41.55 points of a 329.85-point Dow Jones week, so Bailey’s Friday lines cannot be the 3.13 percent. Defense rose, Scottish Mortgage and Polar Capital Technology fell, and QQQ fell 5.52 percent from 9 October. The FTSE 100 closed at 10,881.90 because of what it holds.
Why does one page say 3.1 percent and another 3.13 percent?
They are one move with two roundings. Dow Jones prints 329.85 points, or 3.13 percent, to 10,881.90. Divided by the implied prior close of 10,552.05, that is 3.126 percent, which rounds to 3.13 and, to one decimal, to the Standard’s 3.1. Friday is 0.38 percent or 0.4 percent on the same 41.55 points. This piece does not average them.
What did Andrew Bailey actually say in Bangkok?
The Standard quotes him: “To the extent we have seen evidence, it’s quite subdued,” and “It’s too early.” He called policy already restrictive only as a paraphrase. Before the conflict, “the market was pricing a couple of cuts, and I thought that was probably pretty reasonable.” The economy was “more resilient than we expected it to be.” None of that is the week’s 329.85 points.
Did UK banks fall because a new tax is law?
No statute was fetched. The Standard, citing the Guardian, said John Healey may tax banks more heavily on 28 October. Reversing the surcharge cut was put at upwards of £2 billion a year. The surcharge is 3 percent, down from 8 percent, on top of 25 percent corporation tax. NatWest fell 1.2 percent and Lloyds 0.9 percent. That is a headline, not an act.
Is the chart the FTSE 100 at 10,881.90?
No. Nasdaq’s API does not return the cash index, and an official daily table did not download. The chart is EWU, the iShares MSCI United Kingdom ETF, at $48.01 on 16 October, up 3.20 percent from $46.52 on 9 October. That series is not 10,881.90, and it is not the index’s 0.26 percent gap to the February record. The index level stays in the prose.
What is the next date that can change this close?
Monday 19 October is the next London session, with China data, Canadian inflation, and results from ITM Power and Tristel. On 28 October the surcharge option enters the budget or it does not. A November hike is a 54-of-63 survey, not a vote. The last fetched Bank post is still the 17 September hold at 3.75 percent.
I think buying a car should be exciting. But the process can quickly turn into a headache. Between comparing prices, negotiating with salespeople, and figuring out financing. What starts as a simple purchase can feel like a full-time job. And when the monthly payments finally come into focus, the excitement can fade pretty quickly.
Plenty of shoppers are trading the dealership lot for a screen. Carvana (CVNA) sold 197,325 vehicles in the second quarter, up 38% from a year earlier, on record revenue of $7.38 billion versus $6.91 billion expected, with net income of $513 million.
CEO Ernie Garcia called it the company’s 10th straight quarter of industry-leading growth and profitability in its Q2 earnings statement.
In a letter to shareholders, Ernie also said that “our runway is huge,” noting Carvana holds only 2% market share of used retail and 1.5% of all automotive retail. However, higher interest rates are clouding the profit picture.
The stock shows the strain. Carvana shares are down 30.30% year-to-date and 14.67% over the past 12 months, according to Yahoo Finance. Its second-quarter guidance also fell short of some Wall Street expectations, according to a CNBC report.
Carvana reports third-quarter results Oct. 28 after the market closes. Morgan Stanley cut its adjusted EBITDA estimate 2% to $797 million from $816 million. It models EBITDA per car down about $325 from a year ago at $3,759.
Why higher rates hit Carvana’s financing profit
The culprit is a line Wall Street calls Other GPU, or other gross profit per unit. It captures profit per car beyond the sale itself, including the spread Carvana earns when it makes auto loans and later sells to investors. When benchmark rates climb faster than the annual percentage rates (APRs) customers pay, that spread shrinks.
The two-year Treasury yield has risen about 80 basis points since the second quarter, while APRs in Carvana’s latest securitization rose 23 basis points, Morgan Stanley noted. Management has said each basis point of rates not passed on to customers costs roughly $4.50 per car. That implies a gross hit near $365 per car before offsets.
Morgan Stanley models third-quarter Other GPU of $2,565, down $100 from the prior quarter, and $2,450 in the fourth quarter. Q4 is the bigger debate, but the bar may be more manageable than it appears. That is about $130 and $210 below consensus. It says its math may overstate the damage because public securitizations are only 25% to 30% of loan sales and reflect loans written before the latest rate rise.
When I look at car financing, the monthly payment is what catches my attention first. A small change in interest rates might not sound like much on paper, but spread over several years, it can make an otherwise affordable car feel expensive.
That math lands on real people. Car buyers feel higher interest rates in their monthly payments, while Carvana faces a tougher decision about how much of that added cost to pass on to customers and how quickly. Morgan Stanley also flags consumer credit concerns as a near-term earnings risk.
Some 48% of Carvana customers are very likely to buy again, versus 45% for CarMax (KMX).
Morgan Stanley calls the quarter a potential “clearing event.” Its investor conversations show Street estimates for fourth-quarter Other GPU need to come down, which has kept some buyers on the sidelines. Once expectations reset, the focus can return to growth. The bank still expects year-over-year growth in EBITDA per car in the fourth quarter.
Its third AlphaWise survey of about 2,000 consumers offers the case for patience. Carvana-only users rose to 43% from 31% in September 2025, while CarMax-only users fell to 37% from 44%.
Some 48% of Carvana customers are very likely to buy again, versus 45% for CarMax (KMX). Carvana leads on trusted brand (56% to 52%), vehicle selection (55% to 40%), and customer service (54% to 49%), though CarMax has narrowed the gap on price.
The $88 target comes from a 15-year discounted cash flow model using a 12% cost of capital, 2.5% terminal growth, and a 13.2% exit EBITDA margin.
Carvana shareholders’ letter shows that Garcia’s own targets are 3 million cars a year and a 13.5% adjusted EBITDA margin by 2030 to 2035. Risks include the auto credit cycle, margin sustainability, capital raises, and tougher competition.
For investors, Morgan Stanley’s message is that the question has shifted. The key is less about whether Carvana can avoid near-term GPU pressure and more about whether management can establish a credible baseline for financing economics, while keeping its growth story intact. A clean reset on Oct. 28 could clear the path for the stock.