Author

admin

Browsing

US stocks ended lower on Monday as renewed military hostilities between the United States and Iran pushed oil prices higher and revived concerns about inflation and monetary policy.

The decline came as investors prepared to close out a volatile August, with all three major indexes still on track to post monthly gains.

The Dow Jones Industrial Average dropped 380.22 points, or 0.71%, to 53,179.77.

The S&P 500 fell 0.36% to 7,684.37, while the Nasdaq Composite declined 0.16% to 26,360.91.

The renewed weakness followed the first direct exchange of fire between the US and Iran in a month.

Higher crude prices and rising Treasury yields added to pressure on equities, while investors continued to assess Federal Reserve Chair Kevin Warsh’s recent hawkish comments on inflation.

Oil prices rise as US-Iran tensions escalate

US Central Command confirmed that the US struck two rocket launchers on Iran’s Larak Island on Sunday.

The strike was the first publicly acknowledged US attack on Iranian positions since late July. Iranian state media reported that Tehran responded by attacking US bases in Jordan.

The renewed hostilities increased concerns about oil supplies as the conflict affected shipments through the Strait of Hormuz.

West Texas Intermediate crude rose nearly 3% to $85.76 a barrel, while Brent crude futures gained almost 3% to $90.49.

Energy stocks benefited from the rise in crude prices. Halliburton and Valero Energy advanced, while the S&P 500 energy sector posted solid gains.

The increase in oil prices also contributed to higher longer-dated Treasury yields, adding to pressure on stocks.

Investors remained focused on whether sustained energy costs could contribute to broader inflation and affect the Federal Reserve’s interest-rate decisions.

Fed rate hike bets increase

Markets are increasingly pricing in the possibility of a September rate increase following Warsh’s comments at the Jackson Hole symposium.

Warsh said recent inflation readings, although better than expected, had not demonstrated a meaningful improvement in underlying trends.

His comments came after mixed economic data, with July consumer inflation showing relatively mild price pressures while the Personal Consumption Expenditures reading was hotter than expected.

Financial markets were pricing in more than a 65% probability of a 25-basis-point rate hike at the end of September, according to the CME FedWatch tool.

Investors will receive additional economic data this week, including the August employment report on Friday. Manufacturing and services data are also scheduled, potentially providing further clues about the economy and the Federal Reserve’s policy outlook.

Stocks finish August with monthly gains

Despite Monday’s declines, the major indexes closed positive in August. The Dow was up more than 1% for the month and posted its fifth consecutive monthly advance.

The S&P 500 and Nasdaq were up about 2% and 3%, respectively.

Technology stocks led the monthly gains, with the S&P 500 technology sector rising nearly 6%.

Nvidia climbed more than 9%, while Microsoft and Micron Technology gained 10% and 15%, respectively.

The month was nevertheless marked by volatility as inflation concerns pushed Treasury yields to multi-year highs.

The Treasury Department announced plans to increase debt repurchases, but long-term yields remained elevated.

Elsewhere, GameStop shares rose after the company said it would use cash to fund about 27% of a previously announced $1.4 billion debt exchange, avoiding further share dilution.

The post Dow falls 380 pts as Iran conflict lifts oil prices and rate hike concerns appeared first on Invezz

Zcash cryptocurrency can be expected to fall further to the next support level 750.00 (low of the previous correction iv).

  • Zcash reversed from key resistance level 883.00
  • Likely to fall to support level 750.00

Zcash cryptocurrency today reversed down from the resistance zone between the key resistance level 883.00 (which stopped the previous sharp upward impulse wave iii in the middle of August, as can be seen from the daily Zcash chart below) and the upper daily Bollinger Band. The downward reversal from this resistance zone stopped the earlier minor impulse wave v – that belongs to the intermediate impulse wave (3) from the start of June.

Given the strong daily uptrend and the moderately bearish sentiment that can be seen across the crypto markets today, Zcash cryptocurrency can be expected to fall further to the next support level 750.00 (low of the previous correction iv).

The subject matter and the content of this article are solely the views of the author. FinanceFeeds does not bear any legal responsibility for the content of this article and they do not reflect the viewpoint of FinanceFeeds or its editorial staff.

The information does not constitute advice or a recommendation on any course of action and does not take into account your personal circumstances, financial situation, or individual needs. We strongly recommend you seek independent professional advice or conduct your own independent research before acting upon any information contained in this article.

Another Mexican restaurant chain is pulling out of a major U.S. market, reversing an expansion that began just over a year ago.

The exit comes after the chain introduced a new restaurant format in the area, expanded that concept to additional locations, and positioned the market as an important part of its growth strategy.

Now, all of its remaining restaurants in the area have closed.

Founded in 2003 in Fort Worth, Texas, Fuzzy’s is a Mexican restaurant chain known for its tacos and margaritas. Dine Brands Global Inc. (DIN) acquired Fuzzy’s in late 2022, expanding into the fast-casual segment.

Fuzzy’s closes all Houston restaurants

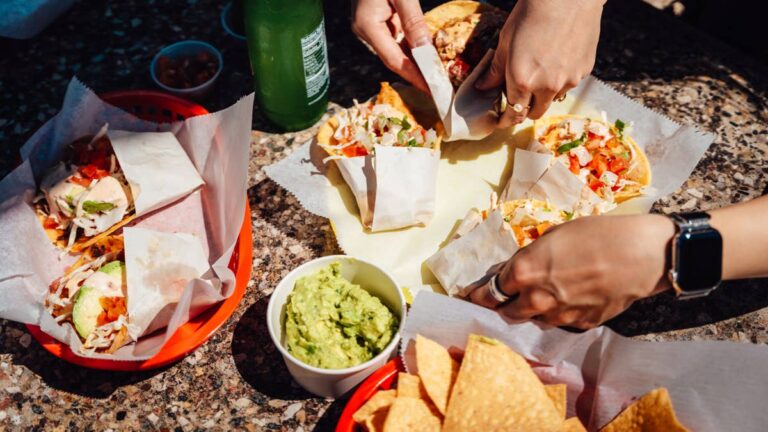
Fuzzy’s has closed all of its remaining restaurants in the Houston area, ending the chain’s presence in the market.

The impacted locations include:

  • Katy: 613 S. Mason Rd
  • Kingwood: 4360 Kingwood Dr.
  • Sugar Land: 1912 Wescott Ave. Ste. 250

The three restaurants were operated by Fuzzy’s franchisee Nazarian Global Enterprises (NGE Group). NGE did not issue a detailed public statement regarding the closures.

Fuzzy’s returns to Houston

The shutdown comes just over a year after Fuzzy’s introduced its new hospitality-driven model in Sugar Land.

NGE opened the first Houston restaurant under the new concept in June 2025. Called Fuzzy’s Tacos and Margs, the location introduced a full-service dining experience, technology enhancements, and a revamped menu. The concept was designed to blend elements of fast-casual and full-service dining.

Unlike traditional Fuzzy’s locations, where guests order at the counter and collect their food at a pickup window, the Sugar Land restaurant offered tableside service. Guests could take a seat while a server, known as a “Tacotender,” took their order.

The new format aimed to put hospitality at the center of the experience while simplifying the process for customers.

“We’re excited to pilot this new model that puts hospitality front and center while simplifying the overall experience for our guests,” Fuzzy’s President Patrick Kirk said in a company announcement at the time.

Kirk said the new model was intended to help the brand find a balance between fast-casual and full-service dining, with a streamlined menu, new taco offerings, and an expanded margarita lineup.

The concept then expanded to Kingwood in November 2025 and Katy in December of the same year.

Fuzzy’s closes all its restaurants in the Houston area.

Oscar Wong / Getty Images

Fuzzy’s previous closures

The Houston restaurants are not the only Fuzzy’s locations to close over the past year.

The chain had previously attempted to establish a presence in Houston, opening a Fuzzy’s Taco Shop location in the area in 2016 before eventually leaving.

Fuzzy’s ended June 28, 2026, with 97 restaurants, down significantly from the 113 locations it had at the same time the previous year, according to its second quarter of fiscal 2026 earnings report.

The chain’s net system sales also declined more than 5.3% during the quarter, while traffic decreased. Franchise revenue fell 0.7%, which Dine Brands attributed in part to the reduction in the number of restaurants.

However, same-store sales rose 4.6% during the quarter, helped by menu price increases.

Dine Brands CEO John Peyton said during the company’s latest earnings call that off-premise sales remained an important contributor to Fuzzy’s performance.

“Off-premise remains a meaningful and consistent contributor to the brand’s quarter-over-quarter improvement,” Peyton said.

He also said Dine Brands was encouraged by Fuzzy’s performance during the first half of the year and remained focused on building on that momentum.

The Houston closures come as Fuzzy’s continues to operate restaurants across the broader footprint, despite the decline in its total restaurant count over the past year.

Mexican restaurant chain closures

While the reason behind Fuzzy’s shutdowns remains unclear, the closures come as several Mexican restaurant chains have faced financial challenges, closures, or restructuring efforts.

Here’s some of my previous coverage of Mexican restaurant closures:

  • Gringos Locos: Closed all of its Orlando-area restaurants in August 2026.
  • On the Border Cantina Mexican Grill & Cantina: Closed all remaining locations in June 2026.
  • Del Taco: Closed several restaurants and exited multiple markets following separate franchisee bankruptcies.
  • Taco Giro: Closed seven of its restaurants following multiple ICE raids across various locations in December 2025.

Related: Popular Mexican restaurant adds new menu, new store concept

The Kospi Index has come under intense pressure in the past few months as top constituents like Samsung Electronics and SK Hynix lost momentum and as wary South Koreans pare back their leveraged bets. It dropped to 6,788 on Friday, down by 27% from its highest point this year.

South Koreans ditch their leveraged bets

The Kospi Index embarked on one of the best bull runs since 2025 when the new president pledged to push it to the 5,000 mark. His statement coincided with the artificial intelligence boom that led to a surge in data center spending in the US and other countries. 

The boom led to a surge in demand for products made by companies like Samsung and SK Hynix. Indeed, the two companies have recently released strong financial results and announced a significant increase in share buybacks and dividends. 

Samsung will spend $80 billion in buybacks, while SK Hynix will spend nearly $30 billion. Despite this, the two stocks have dropped by 32% and 44% from their highest levels this year. 

This trend pushed more South Koreans to embrace leveraged bets in South Korean stocks. Most notably, the decision to allow leveraged stock trading led to a frenzy.

Now, however, there are signs that this trend is reversing as South Koreans lost billions of dollars. According to Bloomberg, the volume of leveraged Samsung and SK Hynix traded has dropped to 4% of the June peak. 

They are also set to have the first monthly outflows since they were approved. This action is mostly because of the ongoing regulatory tightening and the losses traders experienced as the two stocks dropped. This performance has led to a sharp decline in Kospi’s volatility.

Key South Korean data ahead

The Kospi Index also wavered after the South Korean Central Bank decided to hike interest rates last week. It hiked rates for the second consecutive meeting, citing the elevated inflation. This inflation has been caused by the US-Iran war and the soaring wages in Samsung, SK Hynix, and their suppliers.

There will be some important macro numbers later this week. On Monday, South Korea will release the latest retail sales and industrial production numbers, which will shed color on the state of the economy. Analysts expect these numbers to show that retail sales and industrial production rose in July.

The other key macro data to watch will be South Korea’s exports and imports numbers. Economists expect the report to show that exports jumped by 62.6% in August, while imports jumped 24.7%, leading to a trade surplus of over $30.7 billion.

The Kospi Index will also react to the latest consumer inflation report on Wednesday. That report will help to determine whether the central bank will hike interest rates again.

Kospi Index technical analysis

Kospi Index chart | Source: TradingView

Technicals suggest that the Kospi Index is at risk of more downside in the near term. It has slowly formed a rising wedge pattern, a common bearish reversal sign. This wedge is forming after it dropped sharply from the all-time high of 9,387. As such, there are signs that this is a bearish flag pattern.

The index remains below the 50-day Exponential Moving Average, a sign that bears are in control for now. Therefore, the most likely scenario is where it drops to the key support level of 6,000 points.

The post Kospi Index at a crossroads as Samsung, SK Hynix leverage bets reverse appeared first on Invezz

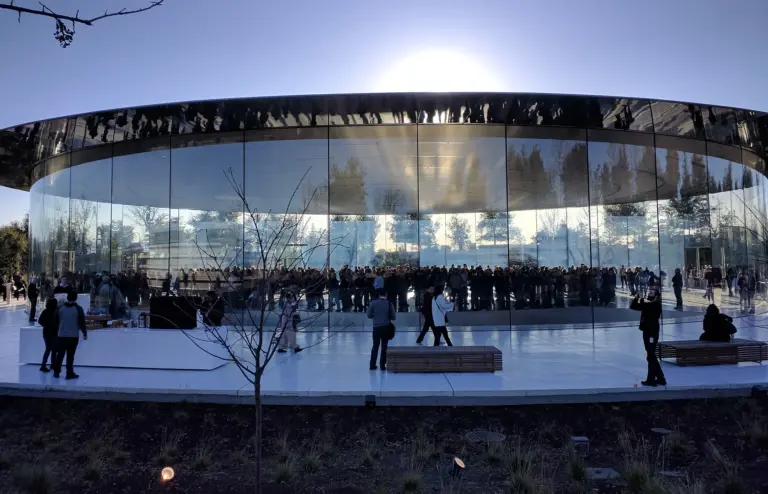
The interesting thing about Apple’s next fortnight is not the foldable. On 1 September John Ternus becomes chief executive, ending the longest and most lucrative CEO tenure in corporate history, and on 9 September he walks onto the stage at the Steve Jobs Theater to launch a new product category. Apple closed 28 August at $319.70, a $4.67 trillion company that has gained 37.5% in twelve months. Yet the reallocation everyone expects the new CEO to make has already happened. In the nine months to 27 June 2026, Apple’s research and development spending rose 32.5% to $34.0 billion while share buybacks fell 12.0% to $62.1 billion. Tim Cook’s final act was to start dismantling the financial machine he is famous for building. Any Apple stock prediction that treats 9 September as the catalyst is looking at the wrong document.

Here is why that matters more than a hinge. For fifteen years the Apple equity case has been an algorithm: convert modest revenue growth into strong earnings-per-share growth by relentlessly shrinking the share count. That algorithm is what supports a multiple of 36.7 times earnings on a hardware company. A year ago Apple spent $2.75 buying its own stock for every $1 it spent on research. Today that ratio is $1.82. It has compressed by a third in twelve months, and it compressed under Cook, before the engineer took over. The bull case is that Apple is finally buying its way back into the AI conversation. The bear case is that the EPS algorithm justifying the multiple is being quietly retired. Both readings are supported by the same 10-Q.

Key facts: Apple in seven numbers

  • R&D up 32.5%, buybacks down 12.0% over the first nine months of FY2026 versus the same period a year earlier: $34.0bn against $25.7bn, and $62.1bn against $70.6bn. Source: Apple Inc. Form 10-Q, quarter ended 27 June 2026.
  • Q3 FY2026 revenue $109.4bn, up 16%, with iPhone revenue up 22% and gross margin of 50.06%, the strongest quarterly margin in the company’s recent history. Source: Apple Form 10-Q and Q3 results, 30 July 2026.
  • The stock still fell 7.35% on 31 July, its worst session of the past year, after Apple guided the current quarter on “supply constraints” despite beating on both lines. Sources: Apple Q3 results; StockAnalysis closes.
  • Consensus price target $324.45, just 1.49% above spot, across 44 analysts, with a range of $215 to $400. Strong Buy ratings have fallen from 25 in March to 19 in August. Source: S&P Global via StockAnalysis, 28 August 2026.
  • Apple trades at 36.7 times trailing and 34.9 times forward earnings, on free cash flow of $136.7bn and a shareholder yield of 2.46%. Source: StockAnalysis, 28 August 2026.
  • The foldable needs roughly $2,399 to hold Apple’s margin targets, according to Fubon Research, in a year when DRAM contract prices are up more than 75% and smartphone bills of materials are rising 5% to 7%. Source: Arthur Liao, Fubon Research.
  • Prediction markets put a foldable iPhone shipping before 2027 at 94.3% on more than $410,000 of volume, but price the whole of September as a coin flip: 50.0% that Apple touches $336, 49.5% that it touches $304. Source: Polymarket, 30 August 2026.

What the last quarter actually showed

Strip away the guidance and Apple’s operating performance is the best it has been in years. Over the first nine months of FY2026 revenue rose 16.2% to $364.4 billion, gross profit rose 21.7% to $178.8 billion and net income rose 20.0% to $101.5 billion. Gross margin expanded from 46.8% to 49.1% across the nine months and touched 50.06% in the June quarter. For a company that spent the early 2020s being described as ex-growth, a 16% revenue line with expanding margins is a genuine re-acceleration.

The market’s response on 31 July was to mark the stock down 7.35%, its worst day in twelve months, because Apple guided the September quarter on supply constraints. That reaction tells you what the stock is priced for. At 36.7 times earnings, a beat is the assumption and any friction is the news. We covered the mechanics of that session in our report on how Apple beat by every measure and fell 6% on two words.

Underneath, the composition of spending changed materially. R&D of $34.0 billion over nine months already exceeds Apple’s entire FY2025 research budget of $34.6 billion, and now runs at 9.3% of revenue. Buybacks fell for the first time in years. The share count still shrank, from 14.687 billion at 17 April to 14.594 billion at 17 July, but the rate of shrinkage is slowing. Apple did not announce a strategy change. It simply moved the money.

Why a hardware engineer changes the capital question

Cook’s Apple was an operations company. He came from supply chain, and his defining financial achievement was converting a maturing product business into an earnings compounder through scale, margin discipline and the largest buyback programme in history. Ternus is not that. He joined Apple in 2001, ran Hardware Engineering from 2021, and is the executive who ships silicon and enclosures.

Cook said as much in the succession announcement: “John Ternus has the mind of an engineer, the soul of an innovator, and the heart to lead with integrity.” Ternus’s own line was “I am profoundly grateful for this opportunity to carry Apple’s mission forward,” and Arthur Levinson, moving from non-executive chairman to lead independent director, described Cook’s tenure as having “transformed Apple into the world’s best company.”

Read those quotes as a capital-allocation signal rather than a press release. Engineers build. Apple has spent five days demonstrating exactly that, introducing the M6 and M5 Ultra on 25 August in a launch Apple framed around AI compute, a story that drew more than 1,300 points and 1,290 comments on Hacker News. Combine new silicon, an all-new Siri shipped at WWDC in June, and R&D running a third higher year on year, and the direction is unambiguous. Apple is spending. FinanceFeeds set out the strategic inheritance in our piece on how Ternus inherits Apple’s AI position.

The question is where the money comes from. Apple generates $136.7 billion of free cash flow a year and holds $39.5 billion of cash and equivalents. It cannot fund a hyperscaler-scale AI build and maintain a $90 billion annual buyback simultaneously. Something gives, and the nine-month figures show which one is already giving.

The margin problem hiding inside the foldable

The second pressure point arrives on 9 September. Apple is expected to launch the iPhone 18 Pro and Pro Max alongside its first foldable, widely reported as the iPhone Ultra, at the Steve Jobs Theater. Prediction markets put a foldable shipping before 2027 at 94.3%, so the product is close to a certainty. The economics are the open question.

Arthur Liao of Fubon Research models the foldable at about $2,399 and is explicit that this price is what the device needs “to cover the materials costs and hit Apple’s margins” rather than a premium land-grab. Liao notes DRAM contract prices up more than 75% against the fourth quarter of 2024 and total smartphone bills of materials rising 5% to 7% in 2026, with the foldable’s OLED panel, hinge and lightweight internals adding further cost. Ming-Chi Kuo’s range is $2,000 to $2,500.

That is the tension. Apple just posted a 50.06% gross margin, and the flagship product of its next cycle is priced to defend margin rather than expand it, in a component cycle that is running against it. Our reporting on TSMC raising chip prices by up to 10% covers the other half of that squeeze. A first-generation foldable at low volume and thin margin is a rounding error on a $466.8 billion revenue base in year one. It matters because it sets the cost trajectory for the category Apple has chosen as its next growth engine.

Apple’s share price to 28 August 2026 against the $375 bull and $235 bear cases, with the 31 July guidance drop marked, and the nine-month shift from buybacks into R&D. Sources: Apple Inc. Form 10-Q for the quarter ended 27 June 2026; daily closes via StockAnalysis.

The long-term case: one number times another

Apple’s valuation reduces to two variables, and the incoming CEO influences both. Forward earnings per share of roughly $9.20, and a multiple of 34.9 times. Everything else is commentary.

The bull case, and how we get to $375. The re-acceleration is real: revenue up 16.2%, net income up 20.0%, iPhone up 22% in the June quarter. If Apple carries that into FY2027, earnings per share reaches roughly $11.00. Hold today’s forward multiple of about 34 times, which the market has demonstrably been willing to pay, and the result is approximately $375. This requires no multiple expansion at all. It requires only that the foldable extends the iPhone cycle, that the new Siri closes enough of the AI gap to stop the narrative discount, and that Apple’s spending produces products rather than press releases. That sits below the Street high of $400 and comfortably above the $335 median.

The bear case, and how we get to $235. Earnings per share stalls at about $9.20 as buybacks keep shrinking, component costs bite and the foldable dilutes hardware margin. Then the multiple does the damage. If the market concludes that Apple is now a capital-intensive AI builder rather than a capital-returning compounder, 34.9 times is the wrong multiple; something nearer 25.5 times, close to Apple’s own longer-run median, is more defensible. That combination gives approximately $235. Note that this is not a catastrophe scenario. It assumes Apple’s revenue holds and only the market’s willingness to capitalise it changes. The Street’s own low target is $215, which is 33% below spot, so a $235 bear case is not an outlier view.

What the market actually expects. Polymarket’s September ladder for Apple is thin but continuously quoted, and it is remarkably symmetric: a 50.0% chance the stock touches $336 during the month against a 49.5% chance it touches $304, with only 8% on reaching $368 and 8% on falling to $256. A new chief executive and an entirely new product category, and the market is pricing a plus or minus 5% event with almost no tail. That is either complacency or a correct assessment that neither the handover nor the foldable changes the earnings power of an iPhone franchise this large. It is worth deciding which before 9 September rather than after.

The signal the sell side is sending

One number deserves more attention than it is getting. The consensus price target across 44 analysts is $324.45, which is 1.49% above where the stock trades. In practice Wall Street is saying Apple is worth roughly what it costs. That is unusual, and it is a marked change: Strong Buy ratings have fallen from 25 in March to 19 in August, Strong Sell ratings have risen from one to three, and total coverage has thinned from 48 analysts to 44.

This is the opposite of what we found when we ran the same exercise on Nvidia, Amazon and Tesla, where consensus targets sat well above spot. On Apple the Street has stopped underwriting further upside, at the exact moment the company is changing chief executive and entering a new product category. A stock priced at fair value by its own analyst base has no valuation cushion if execution disappoints, and no ceiling imposed by scepticism if it does not.

What happens next: three predictions

One: the foldable’s price is the real headline on 9 September. If the iPhone Ultra launches at or above $2,399, Apple is protecting margin and the bull case survives intact. If it launches materially below $2,000, Apple is buying category share at the expense of the 50% gross margin, and the market will treat that as a strategy change, not a bargain.

Two: the buyback line in the FY2026 fourth-quarter release is the number to read first. Nine-month repurchases are already down 12.0%. If the full-year figure lands below $80 billion while R&D exceeds $45 billion, the reallocation is confirmed as policy rather than timing, and the EPS algorithm that supports 36.7 times earnings needs re-underwriting. Apple reports FY2026 results in late October, and that is a bigger event for the multiple than the keynote.

Three: Ternus gets roughly two quarters of grace. New chief executives are judged on their first full product cycle, not their first keynote. The March 2027 window, when the standard iPhone 18, the 18e and the Air 2 are expected under Apple’s new staggered launch strategy, is when the market will form a view on whether the handover changed anything. Until then the stock trades on the same two variables it always has.

Tim Cook took over from Steve Jobs on 24 August 2011, and hands over almost exactly fifteen years later. He leaves a company with better growth than when the year started, a record gross margin, a shipped Siri, new silicon and a foldable on the launch pad. He also leaves it spending a third more on research and 12% less on its own stock, at a multiple built on the opposite behaviour. That is the inheritance, and it is a more interesting one than a hinge.

Frequently asked questions

When does John Ternus become Apple CEO?

1 September 2026. Apple announced on 20 April 2026 that Tim Cook would become executive chairman and John Ternus, previously senior vice president of Hardware Engineering, would become chief executive. Ternus joined Apple in 2001 and joins the board. Cook remains involved in certain areas, including engagement with policymakers. Ternus’s first keynote is the “Surprise and shine” event on 9 September.

What is Apple expected to launch on 9 September 2026?

The iPhone 18 Pro and iPhone 18 Pro Max, plus Apple’s first foldable, widely reported as the iPhone Ultra, alongside new Apple Watch models. Under a new staggered strategy the standard iPhone 18, the 18e and the iPhone Air 2 are expected around March 2027 rather than in September. Prediction markets put a foldable shipping before 2027 at 94.3%.

Is Apple stock overvalued in 2026?

By its own analyst base, roughly fairly valued. The consensus target across 44 analysts is $324.45 against a spot price of $319.70, an implied upside of 1.49%. Apple trades at 36.7 times trailing earnings and 34.9 times forward earnings. The bull argument is that 16.2% revenue growth justifies it; the bear argument is that the multiple was built on buybacks that are now shrinking.

Why did Apple stock fall on 31 July 2026?

Apple beat on both revenue and earnings for the June quarter, with revenue of $109.4 billion up 16% and iPhone revenue up 22%, then guided the following quarter citing “supply constraints.” The stock fell 7.35%, its worst session of the past twelve months. At a multiple in the mid-thirties, the beat was already priced and the guidance was not.

Is Apple behind on AI?

Less than it was. Apple shipped an all-new Siri at WWDC in June 2026 and introduced the M6 and M5 Ultra chips on 25 August in a launch framed explicitly around AI compute. Research and development spending is up 32.5% year on year over nine months. The open question is not effort but scale: Apple’s capital expenditure remains far below that of the hyperscalers it competes with on AI, and closing that gap would require money currently returned to shareholders.

What would move Apple to the $375 bull case?

Earnings per share reaching roughly $11.00 in FY2027 while the market holds today’s forward multiple of about 34 times. That needs the foldable to extend the iPhone replacement cycle, the new Siri to neutralise the AI-laggard discount, and gross margin to hold near 50% despite rising component costs. No multiple expansion is required, which is what makes it a credible rather than a heroic case.

This article is for information only and is not investment advice. The $375 bull case and $235 bear case are FinanceFeeds estimates derived from Apple’s own filings and published consensus data, not price targets. Prices are as of the 28 August 2026 close. Primary sources: Apple Inc. Form 10-Q for the quarter ended 27 June 2026; Apple Newsroom on the CEO transition; Apple Q3 FY2026 results; StockAnalysis consensus and valuation data.

My wife and I bought our mattress roughly five houses and 13,000 miles ago. It’s a “Bob-O-Pedic” purchased from Bob’s Discount Furniture in Newington, Conn., that we brought with us to West Palm Beach, Fla., and have moved to multiple homes.

It’s more than 10 years old, which exceeds the suggested life of a mattress, although much of the advice about when to replace your mattress comes from companies that make mattresses.

“The most obvious sign of getting a new mattress is if it starts to droop or sag. Mattresses bear your entire body weight for a minimum of 8 hours every day,” according to Nectar Sleep.

“…Due to such reasons its natural for the mattress to sag over the due course of time. This may usually start at the edges where they begin to wear out and slowly spread to the sides and enter until your mattress loses all its firmness.”

That hasn’t happened with our mattress, so we have never even considered replacing it, and that speaks to a problem currently impacting the mattress industry.

Replacing a mattress is broadly discretionary. It’s something people can put off, and with the economy struggling, many have. That has led to numerous Chapter 11 filings in the industry, and another popular chain, No Bull Mattress & More, has joined that list with its own Chapter 11 bankruptcy filing.

No Bull Mattress files Chapter 11 bankruptcy

No Bull Mattress & More, a mattress retailer with stores in North Carolina, South Carolina, and New Jersey, has filed for Chapter 11 bankruptcy protection, according to court documents found on PacerMonitor.

The company’s legal entity, Mattress Warehouse of Charlotte Inc., filed a voluntary Chapter 11 petition Aug. 24 in the U.S. Bankruptcy Court for the District of South Carolina, according to bankruptcy records. The case number is 26-03863-jd.

Owned by John S. Madden, Mattress Warehouse of Charlotte operates under the No Bull Mattress & More banner located in North Charleston, S.C., according to Furniture Today.

The company lists assets of $374,535 in personal property, and total liabilities of more than $2.82 million. More than $756,000 of that comes from nonpriority unsecured claims. The filing indicates the company has $178,055 in mattresses, beds, sheets, and other bedding for sale, along with floor models, according to the bankruptcy petition.

No Bull Mattress & More has not shared whether it’s closing any stores as part of its Chapter 11 reorganization efforts.

The retailer operates six stores in South Carolina, three stores in North Carolina and one location in New Jersey, according to its website.

In the bankruptcy filing, the company showed a steep decline in gross revenue over the past two years, with 2026 sales for the first eight months listed at $825,414, down from more than $1.9 million in 2024.

The mattress industry has struggled

In most cases, consumers have significant discretion when it comes to replacing a mattress. That allows them to put off the purchase when times are tight.

That, however is not the biggest problem facing the industry, according to Mike Magnuson CEO of GoodBed.com

“We’ve created a market that, by pure accident, is unfortunately giving consumers the impression that all of our products are the same,” Magnuson said at the SleepNXT conference. “Commodity products continue to steal share in this market.”

Using Better Sleep Council research, Magnuson highlighted a sharp decline in consumers’ perceived value of mattresses. Inflation-adjusted expectations of what consumers planned to pay for a mattress fell 15% between 2016 and 2022, while willingness to pay dropped 18%, Furniture Today reported.

“That’s against a backdrop where we all believe people are more and more conscious of the benefits of sleep,” he said. “Notwithstanding that, we see them valuing this product less.”

The industry broadly struggled in 2025, according to attendees at last year’s High Point Market industry event.

“Business has been challenging overall, and many retailers are reporting that their sales are down anywhere from 2% to 5% or more for the year,” the exhibitors told Bedding News Now.

More Bankruptcy:

They painted a portrait of a generally difficult year for mattress retailers.

“In general, 2025 has been a challenging year for retailers,” said Derek Leishman, national sales director for Mlily. “There has been geopolitical uncertainty, a back and forth on tariffs, and the country’s biggest employer, the federal government, is shut down. With all of that, consumers may be holding off on purchases until things get better.”

Some consumers have delayed purchasing a mattress.

Shutterstock

Mattress retailers face an expense problem

RTM Nexus CEO Dominick Miserandino thinks there’s an easy explanation behind why many mattress chains have struggled or filed Chapter 11 bankruptcy.

Look, mattress chains are failing for one simple reason: you can’t pay strip-mall rent on a product people buy once every decade. Their big defense has always been ‘customers need to try before they buy.’ But laying on a bed for two awkward minutes under fluorescent lights with a commission salesman hovering over you isn’t testing a mattress,” he told TheStreet.

That advantage has largely been replaced by another type of trial that actually gives you more peace of mind.

“Direct-to-consumer brands completely neutralized that by giving people a 100-night trial in their own bedroom with free returns. When consumers can test a bed at home for three months, paying massive markups just to lay on a floor model for three minutes makes zero sense,” he added.

Demand has also dropped as consumers choices have risen, according to Miserandino.

“Once the housing market froze and inflation hit big-ticket items, foot traffic vanished, leaving these chains trapped in high-rent leases for showrooms nobody needs anymore,” he shared.

Multiple mattress brands have filed Chapter 11 bankruptcy

It’s a market that has led to a number of Chapter 11 bankruptcy filings, including some major names in the space.

  • Serta Simmons Bedding: Chapter 11 filed January 2023. The mattress manufacturer filed a prepackaged Chapter 11 restructuring after years of heavy debt. It emerged from bankruptcy in June 2023, with its debt substantially reduced and ownership transferred to lenders, according to Retail Dive.
  • Factory Mattress/Southwest Mattress Sales: Subchapter V Chapter 11 filed June 7, 2024. Austin-based Southwest Mattress Sales, which operates Factory Mattress
    and Factory Mattress Sales, filed under Subchapter V. The company subsequently had its reorganization plan confirmed in May 2025, Inforuptcy reported.
  • Metro Mattress Corp.: Chapter 11 filed Sept. 4, 2024. The New York-based mattress retailer filed Chapter 11. The case was ultimately dismissed in January 2026, according to Inforuptcy.
  • American Mattress/AFM Mattress Co.: Chapter 11 filed July 2025. American Mattress’ parent company, AFM Mattress Co., filed Chapter 11. The filing covered 52 stores in Illinois and Indiana; stores in Michigan, Florida, and Missouri were operated by non-debtor affiliates. The company cited a difficult business environment, election-year uncertainty, and costly mattress-vendor product line changes and showroom resets, reported Furniture Today.
  • Landmark Furniture/Mattresses For Less: Chapter 11 filed Nov. 9, 2025. Brenmark Inc., doing business as Landmark Furniture and Mattresses For
    Less, filed Chapter 11 in Texas along with Taylors Fine Furniture & Mattress LLC.
    Source: Bankruptcy case information, reported Inforuptcy.
  • Sleep Number: Chapter 11 filed June 2026. Sleep Number filed Chapter 11 with approximately $672 million of debt and entered bankruptcy with a $415 million stalking-horse acquisition agreement from Sleep Country Canada. The company subsequently received court approval for a $701 million total-value sale of its assets, according to Reuters.

Related: Biggest sports bar chain closes locations before football season

Consumers push back mattress purchases

When your car breaks down, you need to fix it, replace it, or find another way to get to work. That’s not the case with mattress purchases.

Toby Konetzny, CEO of South Bay International, told Bedding News Now that consumers have been pulling back on spending at a time when consumer confidence is down.

“Life feels more expensive these days,” he said. “That makes consumers think, ‘I don’t really need a new mattress.’ Products have to be on sale for consumers to buy.”

The data from the the International Sleep Products Association (ISPA) 2026 Mattress Industry Trends Report (MITR) shows a steep decline for the industry.

“Total U.S. mattress market value declined 6.5% year over year, while unit shipments fell 13.2%, underscoring continued softness in consumer demand,” according to the report.

Mary Thorpe, director of industry research and analytics at ISPA, did see some positive signs.

“Looking beyond the headline numbers, the data shows a market where value proved more resilient than unit demand,” she said. “Unit demand remained under pressure in 2025, but pricing discipline and product mix helped limit the decline in dollar value. Manufacturers largely maintained pricing despite lower volumes, while a shift toward larger mattress sizes contributed to higher average unit values.”

ALSO READ: Star Wars legend’s studio liquidated after Chapter 11

As governments and regulators around the world intensify scrutiny of social media’s impact on children, Meta’s landmark US settlement marks a major shift in how technology companies may be held accountable for the way their platforms are designed and used.

Meta has agreed to overhaul parts of Instagram and Facebook in the United States and pay up to $18 billion to settle a landmark lawsuit brought by dozens of states that accused the social media giant of deliberately designing its platforms to addict children and exposing young users to serious mental health harms.

The settlement, reached Wednesday, brings a major California trial to an end and marks the first time in the United States that Meta has been forced to change key features of the everyday social media experience as part of a legal agreement.

The deal requires Meta to introduce a series of safeguards for users under 18, including default limits on daily usage, restrictions on nighttime access and changes to how content and notifications are presented to teenagers.

Officials described it as the biggest state consumer-protection settlement outside the tobacco settlements of the 1990s.

Meta faces its biggest US settlement yet

The size of the agreement underscores the growing legal pressure facing Meta and the wider social media industry over the impact of online platforms on children.

Meta’s payment is more than 12 times the previous highest settlement recorded over the past four years.

That benchmark was set by Meta itself in 2024, when it agreed to pay $1.4 billion to settle a separate case.

The latest agreement also represents the largest settlement ever reached with a single company through the New York attorney general’s office.

The previous record was a $7.4 billion settlement reached in 2022 with Purdue Pharma and the Sackler family over the opioid crisis.

The lawsuit alleged that Meta intentionally incorporated addictive features into Instagram and other products while failing to adequately warn the public about potential risks to young users.

The states argued that the company knew its products could contribute to harmful experiences among children but continued to prioritize engagement.

The settlement does not simply impose a financial penalty.

It requires changes to the products themselves, potentially establishing a new template for how technology companies can be held responsible for the design of services used by children.

Measures put in place for teenagers’ use

Under the agreement, Meta will automatically apply several protections to users under 18 on Instagram and Facebook in the US.

The most significant change is a default two-hour daily usage limit. Teenagers will be able to disable the restriction only with permission from a parent.

Meta will also introduce a default Night Mode that blocks access to its applications between midnight and 6 a.m.

During those hours, teenagers will not be able to post or view content through Feed, Stories, Explore or Reels.

The company is also introducing a School Mode feature that will mute notifications by default between 8 a.m. and 3 p.m.

Certain communications will remain accessible. Direct messages and alerts relating to account security or safety will not be blocked under the school-time restrictions.

The changes extend beyond limits on how long teenagers can use the platforms.

Meta said it would also introduce greater controls over algorithmic feeds and autoplay, while users will have options to hide the number of likes and reactions appearing on posts.

The company will also disable cosmetic surgery and extreme makeup filters for teenage users.

Taken together, the measures represent a substantial intervention in the design of Instagram and Facebook, two products whose growth has historically relied heavily on maximizing engagement and keeping users active on their platforms.

How the settlement could have global consequences

Although the agreement applies to Meta’s US operations, its significance is unlikely to stop at the country’s borders.

Governments around the world are already looking for ways to reduce children’s exposure to harmful online content and limit the amount of time young people spend on social media.

Australia has taken the most aggressive approach so far.

It became the first country to introduce a nationwide ban on social media access for children under 16 late last year.

Australian Communications Minister Anika Wells said Meta’s latest changes demonstrated that social media companies already have the ability to protect children from potentially addictive features.

Australian Communications ​Minister Anika Wells said in an email to Reuters that social media companies “have the tools at their disposal to protect young people from their addictive features but have chosen not ​to use them”.

Australian officials said Meta’s decision to restrict teenage use of its platforms in the US showed that companies could implement stronger safeguards for young people online.

In the Philippines, an official told Reuters that Meta had also pledged to strengthen protections for young users there.

South Korea’s media regulator went further, arguing that some of Meta’s new measures should be extended to young users worldwide rather than being limited to individual markets, Reuters reported.

The international response could add pressure on Meta to standardize some of its protections across countries, particularly as governments increasingly coordinate their approaches to children’s online safety.

Social media companies face a growing legal backlash

The Meta settlement comes during a particularly difficult year for social media companies.

In the spring, Meta lost two high-profile court cases involving allegations that its products, including Instagram, harmed young users.

Other major platforms, including YouTube, TikTok and Snapchat, have also faced similar litigation, with companies settling some cases while thousands of lawsuits remain pending.

TikTok this week reached a separate $400 million settlement with the US Justice Department over allegations that it illegally collected children’s data.

At the same time, US states have been passing their own restrictions on children’s social media use.

The regulatory pressure is no longer confined to the US.

Britain, Canada, Denmark, Indonesia and New Zealand have indicated that they intend to follow Australia’s lead on restricting social media access for younger users.

France has also pursued restrictions, although a law that would have banned children under 15 from social media was blocked this month on constitutional grounds.

The growing patchwork of regulations could eventually make it more difficult for social media companies to maintain different safety standards in different countries.

Evidence from lawsuits could fuel further regulation

The significance of Meta’s settlement may extend beyond the specific restrictions imposed on Instagram and Facebook.

Legal proceedings against Meta have brought internal documents and communications involving employees and executives into the public domain.

Those materials could become valuable to researchers, lawmakers and regulators examining how technology companies design products and assess their potential harms.

“There’s clearly an enormous momentum shift here in the United States and globally in the public’s assessment of social media platforms and the broader tech industry,” said Jim Steyer, CEO of Common Sense Media, a nonprofit research and advocacy organization, in an NPR report.

Isabel Sunderland, policy lead for technology reform at Issue One, a bipartisan nonprofit focused on political reform, said the settlement could have a broader impact on lawsuits, legislation and regulation.

She pointed to internal documents and communications that have emerged during the federal trial in Oakland, as well as earlier trials in California and New Mexico state courts this year.

“They’re also opening up huge troves, thousands of documents of discovery that is hugely important for researchers, for lawmakers to be able to write better policy, for the public to understand what their relationship to technology looks like, and how technology companies are designing their products,” she said in the NPR report.

That evidence could prove particularly important as lawmakers attempt to determine whether existing consumer-protection and privacy laws are sufficient to address the risks associated with algorithm-driven platforms.

“Legally, the settlement does not create a precedent in the way a ​court decision would. But it will matter in practice. Other states and plaintiffs now have another indication that these cases can survive substantial legal challenges, reach trial, and create very significant financial exposure for Meta,” said Daryl Lim, a professor at Penn State Dickinson Law.

Whistleblower testimony puts Meta’s internal practices under scrutiny

One of the most significant pieces of evidence to emerge during the federal trial came from former Meta engineer and whistleblower Arturo Béjar.

Béjar testified that he had been involved in internal studies examining how frequently users encountered harmful content, including bullying, self-harm and violence.

According to his testimony, Meta did not publicly release the results of those studies. Instead, the company published other metrics focused on violations of its content policies.

Béjar argued that those measurements did not capture the extent of harm experienced by users and created “a false impression of safety.”

The dispute highlights one of the central issues at the heart of the litigation: whether technology companies’ public measurements adequately reflect the risks users face on their platforms.

Sunderland said the evidence surrounding how companies make decisions could prove particularly valuable to lawmakers.

“The decision-making process of the companies has been a huge piece of evidence that we’ve pulled out from these trials,” Sunderland said.

She argued that the information could help lawmakers draft new legislation and give regulators greater insight when responding to technology companies’ challenges to laws after they are enacted.

A new test for Meta and the wider industry

For Meta, the settlement removes the immediate threat of a major trial while imposing significant changes on two of its most important platforms.

The financial cost is substantial, but the longer-term implications could be even more consequential.

The company will have to demonstrate that its new restrictions can be implemented effectively without undermining the broader user experience. It will also face questions over whether similar protections should eventually be extended beyond the US.

For the rest of the technology industry, meanwhile, the settlement offers a warning that regulators and courts are increasingly looking beyond content moderation and data privacy and examining the design of the products themselves.

The case could also encourage other states and countries to pursue similar restrictions and settlements.

Meta’s agreement therefore represents more than a costly resolution to one lawsuit. It signals a broader shift in how governments view social media companies and their responsibilities toward younger users.

As regulators gain access to more internal evidence and lawmakers face growing public pressure to act, the industry’s long-standing emphasis on engagement could face increasingly stringent limits.

The settlement may ultimately prove to be a turning point — not only for Meta, but for the way governments regulate social media platforms built to keep users coming back.

The post How Meta’s $18B teen safety settlement could reshape social media regulation appeared first on Invezz
Most silver price targets are guesses dressed as models. Ours are not, and the reason is one dataset: over the last twelve months the gold/silver ratio has traded from 44.1 to 89.1. That is not a forecast range — it is the range the market actually printed, twice over, inside a single year. Multiply those two extremes by today’s gold price and you get the entire realistic distribution for silver without assuming anything the market has not already done. Silver settled at $67.79 in the front-month future on 28 August 2026, with spot XAG/USD at $66.50. Our 12-month framework is $100 bull, $80 base, $45 bear, and every one of those numbers is a ratio the market has traded at within the last twelve months.

Here is the arithmetic, because it is the whole article. Gold futures settled at $4,529.90 on 28 August. At a gold/silver ratio of 44.1 — the level printed in January 2026 — silver is $102. At the long-run average ratio of 55 to 60, silver is $76 to $82. At 89.1, the twelve-month high printed last September, silver is $51. The ratio sits at 66.8 today. So the bull case does not require gold to rally; it requires only that silver closes the gap it closed eight months ago. And the bear case does not require an economic collapse; it requires only that the ratio returns to where it was a year ago. This is why silver is a fundamentally different instrument from gold: at a constant gold price, the ratio alone spans $51 to $102.

Key facts

  • Silver front-month settled at $67.79 on 28 August 2026; spot XAG/USD was $66.50, a 1.9% contango — Yahoo Finance and gold-api
  • Trailing 12-month silver range: closing low $40.20 (29 Aug 2025), closing high $115.08 (26 Jan 2026). Silver is 41.1% below that high
  • Gold/silver ratio today: 66.8. Twelve-month range 44.1 to 89.1; long-run average 55 to 60
  • Gold futures settled at $4,529.90, down 1.73% on 28 August; silver fell 2.36% the same session
  • Industrial demand is on track to exceed 720 million ounces in 2026, the highest in Silver Institute records, against a structural deficit now running six consecutive years
  • Solar photovoltaic demand has grown from roughly 50 Moz in 2015 to a projected 175-185 Moz in 2026 — but thrifting could cut it by around 30%, roughly 60 MozCarbon Credits
  • Published end-2026 forecasts cluster in a $75-$100 range, with J.P. Morgan among the houses publishing a formal silver outlook
  • The Warsh Fed has removed its 2026 rate-cut projection; his Jackson Hole debut hit precious metals and mining equities

The bull case: $100 (+50.4% from spot)

The bull case is a ratio-compression case. Hold gold at $4,529.90 and take the ratio back to 44.1 — where it closed in January 2026 — and silver is $102. Round it to $100 and you have a target that requires precisely zero new information about gold.

What drives compression is the industrial bid, and this is where silver stops behaving like a precious metal. Industrial demand is on track to exceed 720 million ounces in 2026, the highest figure in Silver Institute records, and the market has run a structural deficit for six consecutive years. A six-year deficit is not a cyclical tightness; it is a market drawing down above-ground stocks continuously. When investment demand arrives on top of that — as it did in January — the move is violent, because there is no inventory cushion to absorb it. Silver printed $115.08 on 26 January 2026. That is the proof of concept.

The second bull leg is that silver is already rallying off its trough. It bottomed near $58 at the end of July and has climbed roughly 14% since, a move FinanceFeeds flagged when bulls set their sights on $71.85 resistance in mid-August. That level has not yet been cleared, and it is the first real test on the path higher.

The third leg is structural and underappreciated: market plumbing is being built for a bigger silver bid. CME extended its 24/7 trading push into silver after strong weekend demand for gold futures. Continuous access does not create demand, but it removes the friction that historically capped retail and Asian participation between sessions.

The base case: $80 (+18.0% from spot)

The base case is ratio mean reversion and nothing more. The long-run gold/silver ratio sits at 55 to 60. At gold’s current $4,529.90 that maps to $76 to $82. Call it $80.

This is also roughly where the published forecasts cluster — the range for end-2026 runs from about $75 to $100, with at least one model putting silver near $88 by Q4. Our $80 sits at the conservative end of that band deliberately, because the bullish forecasts generally assume gold keeps rising, and the Warsh Fed makes that assumption harder to hold.

The base case’s honest weakness is the solar number. Photovoltaic demand has been the growth engine, rising from roughly 50 Moz in 2015 to a projected 175-185 Moz in 2026. But silver-thrifting technologies could cut that by around 30% — roughly 60 million ounces year over year. That is a genuinely large subtraction from the most-cited bull argument, and it is the reason we do not simply extrapolate the deficit forward. A structural deficit that has run six years can close if the largest demand category engineers itself smaller. The base case assumes thrifting bites but does not eliminate the deficit.

The bear case: $45 (-32.3% from spot)

The bear case is the mirror of the bull: ratio expansion back toward 89.1, the level printed in late August 2025. At today’s gold price that is $51; assume gold also softens to around $4,000 on a hawkish Fed and you land near $45. The trailing 12-month closing low of $40.20 sits below that, so $45 is inside the observed range, not beyond it.

The mechanism is monetary. Silver pays no yield, so it is priced off real rates, and the Warsh Fed has removed its 2026 rate-cut projection. When the Fed turned hawkish in June, silver fell 2.94% in a session — the steepest decline among precious metals. It happened again in August: Warsh’s Jackson Hole debut lifted the dollar and hit mining equities, and silver settled 2.36% lower on 28 August while gold fell 1.73%.

Note the pattern in those two numbers, because it is the core risk in owning silver rather than gold: silver falls harder than gold on the same headline, in both directions. That is what a ratio that can travel from 44 to 89 in twelve months means in practice. The 2.36%-versus-1.73% split on 28 August is a small, live example of the same high-beta behaviour that produced a 41% drawdown from the January high.

Combine hawkish policy with 60 Moz of solar thrifting and the bear case does not need a recession. It needs only the investment bid to leave while the industrial bid shrinks.

Silver versus gold: the same trade at different leverage

The most useful way to hold this is not “is silver going up” but “what leverage am I buying to the same macro.” Gold, as set out in our gold price prediction, is a Fed-and-central-bank story: real rates, dollar, and the official-sector demand that has underpinned it. Silver shares all of that and adds an industrial demand cycle on top, with roughly 40% less market depth to absorb flows.

That is why the ratio is the right lens. In the twelve months covered by the chart above, gold’s own range was wide but orderly. Silver’s was $40.20 to $115.08 — a 186% peak-to-trough spread on the same macro inputs. An investor who is right about the Fed and wrong about position size loses more in silver than in gold even when the directional call is correct.

The practical framing: if your conviction is about monetary policy alone, gold expresses it with less noise. Silver only earns its extra volatility if you also have a view on the industrial side — specifically on whether solar thrifting closes the six-year deficit. That is the question the whole silver bull case now rests on, and it is answerable with data over the next few quarters rather than being a matter of opinion.

Why the four-figure silver forecasts keep missing

A note on forecast quality, because silver attracts worse analysis than almost any other liquid asset. FinanceFeeds has published silver scenarios repeatedly through 2026, and the record is instructive: a June page carried a $150 bull, a late-June page $106, a July page $90, and a July 31 page $110. Silver is $66.50. Every one of those bull cases has so far proved too high, and they were published within six weeks of each other by the same desk against a spot price that barely moved.

The failure mode is always the same. Analysts extrapolate the deficit — six consecutive years, industrial demand at a record, above-ground stocks drawing down — and conclude that price must follow, because in a physical shortage it eventually must. The flaw is not in the logic but in the timing: a structural deficit tells you the direction of the long-run pressure, and nothing at all about the twelve-month path. Silver spent 2026 falling 41% from its January high while the deficit persisted the entire time. Deficits are a necessary condition for a silver bull market, not a sufficient one.

That is precisely why we anchor on the gold/silver ratio instead. The ratio is a relative-value measure, so it is bounded by observed history in a way that “the market is short 200 million ounces” is not. It has printed 44.1 and 89.1 within twelve months, which gives a disciplined floor and ceiling rather than an open-ended extrapolation. A $150 target implies a gold/silver ratio of 30 at today’s gold price — a level not seen since 1980, and not once in the last four decades. Stating the target as a ratio makes the implausibility obvious in a way that stating it as a dollar price does not.

Apply the same test to our own numbers. The $100 bull implies a ratio of 45.3, printed eight months ago. The $80 base implies 56.6, the middle of the long-run band. The $45 bear implies 100.7 at an unchanged gold price, which is above the twelve-month high — which is why the bear case explicitly assumes gold also softens toward $4,000, bringing the implied ratio back to 88.9 and inside the observed range. Every scenario survives the ratio test. That is the minimum bar a silver forecast should have to clear, and most published ones do not.

What would change our mind

Bullish trigger. A clean break of the $71.85 resistance level flagged in August, confirmed by the gold/silver ratio falling below 60 and holding. Ratio compression through the long-run average is the signal that industrial and investment demand are arriving together rather than trading off against each other.

Bearish trigger. The ratio moving back above 75, or hard confirmation that 2026 solar silver demand has fallen by the feared 30%. Either alone is damaging; together they take the base case off the table. Also watch the Silver Institute’s next deficit estimate — a deficit that narrows materially for the first time in six years would break the central structural argument.

The trigger that decides everything. The Warsh Fed’s first actual policy decision rather than its rhetoric. Silver has now sold off twice on hawkish talk. Whether that becomes a durable repricing or a buyable dip depends on whether the talk converts into a hold-or-hike path, and that is knowable on a specific meeting date rather than being permanently ambiguous.

Frequently asked questions

What is the silver price today?

Silver front-month futures settled at $67.79 on 28 August 2026, with spot XAG/USD at $66.50. The trailing 12-month closing range is $40.20 (29 August 2025) to $115.08 (26 January 2026), so silver trades roughly 41% below its 12-month high.

What is the bull case for silver?

Our bull case is $100, about 50% above spot. It requires only that the gold/silver ratio compresses back to 44.1 — the level it printed in January 2026 — at an unchanged gold price. The supporting fundamentals are industrial demand above 720 million ounces in 2026, the highest on Silver Institute record, and a structural deficit now in its sixth consecutive year.

What is the bear case for silver?

Our bear case is $45, about 32% below spot. It requires the gold/silver ratio to expand back toward 89.1, its level in late August 2025, alongside some softening in gold. The drivers are a hawkish Warsh Fed that has removed its 2026 rate-cut projection and the risk that solar thrifting cuts photovoltaic silver demand by roughly 30%, or about 60 million ounces.

What is the gold/silver ratio telling us?

It sits at 66.8, above the long-run average of 55 to 60, which implies silver is cheap relative to gold. But the ratio traded as high as 89.1 within the past twelve months, so “above average” is not the same as “a floor.” The ratio is the single most useful gauge for silver because it strips out the shared macro driver and isolates silver’s own bid.

Is silver a better buy than gold right now?

Silver offers more leverage to the same macro inputs, not a different thesis. Over the last twelve months silver ranged from $40.20 to $115.08 on broadly the same drivers that moved gold far less. If your view is purely about Fed policy, gold expresses it with less volatility. Silver additionally requires a view on industrial demand and solar thrifting.

How does solar demand affect the silver price?

Photovoltaics have been silver’s main demand growth story, rising from roughly 50 million ounces in 2015 to a projected 175-185 million ounces in 2026. However, thrifting technologies that reduce silver loading per panel could cut that by around 30%, roughly 60 million ounces year over year. That is the largest single downside risk to the structural deficit argument.

Related coverage

This article is for information only and is not investment advice. Scenario levels are analysis, not forecasts, and all prices are as of 28 August 2026.